

90.5 cents. That is the price on the no-change leg of the ECB October rate decision, the contract that pays on the change in the deposit facility rate when the Governing Council finishes in Frankfurt on 29 October. The book has turned over $554,682. A 25 basis point increase is priced at 10.5 cents. A cut, or a move of 50 basis points or more in either direction, prints at 0.0005.
That 90.5 is the mid of a one-cent market. The bid is 90 cents, the ask is 91, and the last trade was 91. Eurostat's flash on 2 October put euro-area inflation at 3.8% in September, up from 3.2% in August, with energy at 18.8%. On 10 September in Berlin the council lifted the deposit facility rate by 25 basis points to 2.50%, effective 16 September. Sixteen days before the next press conference, the price says that step stops here.
The 3.8% flash did not reprice the contract into a hike. Christine Lagarde, on 10 September, refused a view on the next meeting. The account published on 8 October told the council to sound like neither a predetermined cycle nor a finished job, and recorded that analyst surveys expected the deposit rate to plateau at 2.50%. Isabel Schnabel, on 30 September, said anchored expectations allow a gradual return to target. The book kept that frame: 10.5 cents on a quarter-point increase. The same day's gamma pull prices the Fed's October contract at 80.5 cents for no change, so the ECB hold is the richer of the two after a hotter European flash. The venue is the ECB October book on Polymarket. Links to Polymarket are affiliate links, from which The Traders Spread may earn a commission at no cost to you.
The numbers in one place
- No change trades at 90.5 cents, bid 90 cents and ask 91, last trade 91 cents, on $244,696 of volume and $11,721 of liquidity — Polymarket gamma-api, retrieved 13 October 2026.
- A 25 basis point increase trades at 10.5 cents, bid 10 and ask 11, last trade 10 cents, on $183,890 of volume and $37,060 of liquidity — Polymarket gamma-api, retrieved 13 October 2026.
- Event volume is $554,682 and event liquidity is $110,325, with the book set to end at 03:59 UTC on 30 October 2026 — Polymarket gamma-api, retrieved 13 October 2026.
- The deposit facility rate is 2.50%, the main refinancing rate 2.65% and the marginal lending rate 2.90%, effective 16 September 2026 — European Central Bank monetary policy decision, 10 September 2026.
- Euro-area HICP inflation was estimated at 3.8% in September, up from 3.2% in August, with energy at 18.8% and services at 3.2% — Eurostat flash estimate, 2 October 2026.
- Staff see headline inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028, and growth at 0.9%, 1.4% and 1.5% — European Central Bank, 10 September 2026.
What the contract actually pays
Resolution is narrower than the phrase "ECB interest rate October" suggests. The market pays on the change, in basis points, in the deposit facility rate produced by the October meeting, relative to the level before it. Official ECB information is the source, including the statement from the meeting on 28 and 29 October. The ECB calendar lists day one on 28 October and, on 29 October, day two plus the press conference. The book can resolve as soon as that statement is out. On the gamma record it ends at 03:59 UTC on 30 October.
If a rate were an upper and a lower bound, the contract uses the change in the upper bound. That clause does not bite. The deposit facility is a single rate, and it is the steering rate. The refinancing rate and the marginal lending rate moved with it on 10 September, to 2.65% and 2.90%. They are 15 and 40 basis points above the deposit rate, and for this contract they do not settle anything.
The three legs at 0.0005 are not empty. The larger cut has about $15,100 of volume, the 25 basis point cut about $25,828, and the larger increase about $85,168. Each shows an ask at 0.001, no bid, and a last trade at 0.001. The no-change leg is the thinnest of the five, at $11,721. Read 90.5 as the mid of 90 and 91.
Add the five yes prices and you get 1.0065, not 1. Each leg is its own book. Our fair values are a distribution, and they sum to 1.
From 2% to 2.50% since June
On 10 September the Governing Council raised all three key rates by 25 basis points. The decision set the deposit facility at 2.50% from 16 September. The stated reason was the conflict in the Middle East, inflation set to stay well above target for an extended period, and the 2% medium-term target. The council said it would stay data-dependent, meeting by meeting, and that it was not pre-committing to a path.
The staff baseline in that statement has headline inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028. Excluding energy and food, the path is 2.5%, 2.6% and 2.3%. The account, out on 8 October, puts the upward revisions at 0.2 percentage points for 2027 and 0.1 for 2028. The 2026 headline figure was left unchanged. Growth is 0.9%, 1.4% and 1.5%. Lagarde said the 2026 growth number had moved from 0.8% to 0.9%, and that second-quarter growth of 0.6% arrived after the cut-off.
What the council saw that day was the August flash, not September's 3.8%. Lagarde said inflation had risen to 3.3% in August, from 2.9% in July, with energy at 14.3% after 10.3%, and inflation excluding energy and food at 2.4%, down from 2.5%. Eurostat's 2 October release prints August at 3.2%, not 3.3%. Energy in that release is still 14.3% for August. The headline tenth moved. The energy shock did not.
Philip Lane proposed the 25 basis point increase. All members supported it, the account says. Raising the deposit rate from 2.25% to 2.50% held across a wide range of scenarios. Underlying inflation had barely moved, and the full effect of the energy shock was still ahead. It was also pointed out that 2.50% sat inside the staff range for a neutral rate, and that the response should stay proportionate. Communication was to stay neutral: not the next step in a predetermined cycle, and not the last increase either.
Lagarde was sharper with the press than the account is on the page. "The decision that we took today – which was, by the way, a unanimous decision,– was a no-brainer. What we will have to do in the future will be determined at each and every meeting." Just before that: "I can assure you that we are not taking a view as to which direction we go at our next meeting." Both lines are in the 10 September transcript. The first explains the hike. The second is the sentence 90.5 cents is leaning on.
Asked about the top of the neutral band, she said the council was not attaching great importance to it, because the band is defined for a time without a shock. The account still records that 2.50% sat inside the staff range. The press conference and the minutes are not the same document.
The commodity levels Lane put in front of the council, from that same account, were oil at $97 a barrel, up 3% since July, European diesel crack spreads above $70 a barrel, and gas at €73 per megawatt hour, 17% above the July meeting. Those are not 13 October spots. This piece has no same-day oil or gas print. They are the shock the council had already hiked into.
Pay had not responded. Unemployment was 6.4% in July. Compensation per employee slowed to 3.3% in the second quarter, from 3.5%, and negotiated wages eased to 2.4%. Unit profits rose from 0.3% to 2.2%. Lending rates to firms were 3.8% in July, up from 3.6% in May. Wages were not delivering a second round. Profits were no longer flat.
Schnabel, on 30 September, said the deposit rate had risen 50 basis points since June, from 2% to 2.5%. September was the second half of that 50. Then the line that governs October: "As long as expectations are firmly anchored and backed up by a track record of delivering on the inflation target, monetary policy can tolerate a more gradual return of inflation to target." The speech is on the ECB site. The next projection round is 16 and 17 December, not the meeting that opens on 28 October.
Five legs, and only two with a price
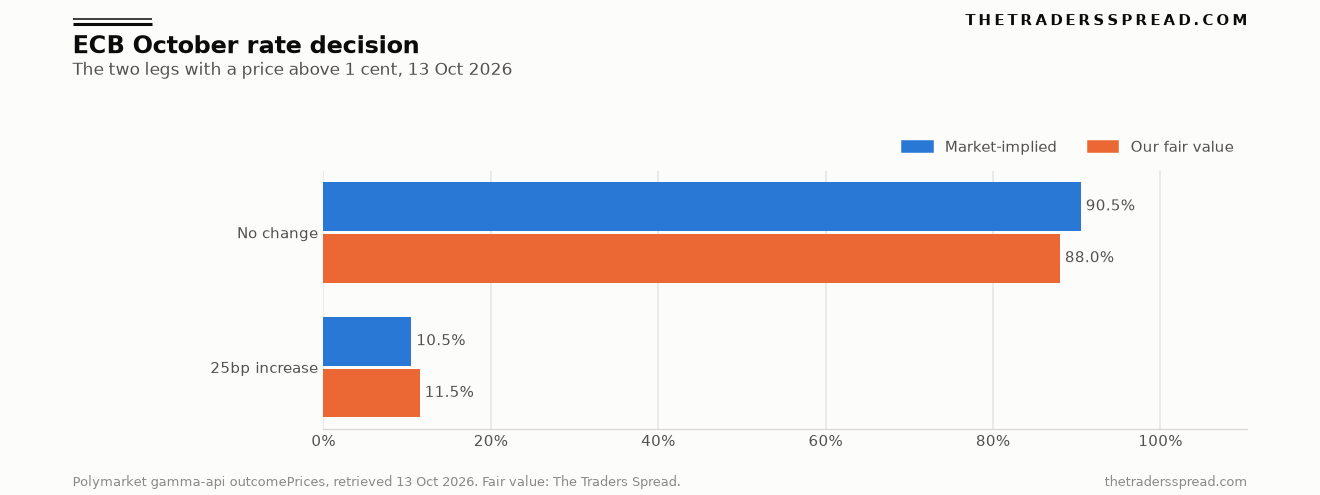
The chart compares the market with our fair value on the two legs above one cent. The other three stay in the table. A bar for 0.0005 would round into a lie at this scale.
| Leg | Yes price | Bid / ask | Last trade | Volume | Liquidity | Our fair value |
|---|---|---|---|---|---|---|
| No change | 0.905 | 0.90 / 0.91 | 0.91 | $244,696 | $11,721 | 0.88 |
| 25bp increase | 0.105 | 0.10 / 0.11 | 0.10 | $183,890 | $37,060 | 0.115 |
| 25bp decrease | 0.0005 | no bid / 0.001 | 0.001 | $25,828 | $27,166 | 0.002 |
| 50bp or larger increase | 0.0005 | no bid / 0.001 | 0.001 | $85,168 | $15,010 | 0.002 |
| 50bp or larger decrease | 0.0005 | no bid / 0.001 | 0.001 | $15,100 | $21,045 | 0.001 |
Every market figure is from the gamma API for ecb-interest-rates-october-2026-20260723225848778, retrieved on 13 October 2026. Volumes are rounded to the dollar from each leg's volume field and sum to the event total. Fair value is ours, not a market price. The no-change leg is the contract that 0.88 refers to.
Two other books, pulled the same afternoon, stop this one being read alone. The Fed's October event prices no change at 0.805 and a 25 basis point increase at 0.195. The November Bank of England event prices a 25 basis point increase at 0.89 and no change at 0.10. Both have their own notes, including the Bank of England November decision. The only use of those prices here is the shape. Washington's October hold is 80.5 cents. Frankfurt's is 90.5. London's November meeting is priced as an increase. Three councils, three distributions, one afternoon.
A US inflation contract is a different question again, a bucket on a CPI print rather than a vote. The note on September CPI odds is about that print. It is not an input to the 0.88. The euro area has its own flash, a full release on 16 October, and its own council.
Why 10.5 cents is the whole argument
At the September meeting the curve and the surveys disagreed. Schnabel's presentation put the priced path at 84 basis points of increases by the end of 2027, against 64 at the July meeting, with a terminal rate above 3%. The Survey of Monetary Analysts had a different median: one last increase, in September, then a plateau at 2.50%. The account says the Bloomberg and Reuters surveys said the same.
Today's 10.5 cent leg is that gap squeezed into one meeting. A curve that wants the deposit rate above 3% by the end of 2027 can want the next 25 basis points on 17 December, when staff publish again, rather than on 29 October. A rich terminal rate and a 90.5 cent October hold can both be true.
Schnabel's test is how this fair value moves. She asked whether energy shifts expectations, whether firms can pass costs on, and whether higher long yields do more work than the baseline assumes. She also said the economy might already be responding more than the projections assume, which leans against a third increase inside six weeks. The flash is unfinished. Headline inflation jumped 0.6 points, services rose from 3.0% to 3.2%, and energy went from 14.3% to 18.8%. There is no September figure yet for inflation excluding energy and food. It arrives on 16 October. The last such reading in a council statement is August's 2.4%.
Eurostat's note on that release says that from 1 January 2026 the aggregate includes Bulgaria. 2026 months are a 21-country series. A tenth can be composition as well as price. It is not a reason to fade 3.8%.
None of this is an exchange-rate call. The September account says the euro rose 1.9% against the dollar between the July and September meetings, and 0.7% in nominal effective terms, and that the rise was one reason conditions had tightened a little. That is a fact about the September dossier. This page has no level for the euro and no path for any dollar cross.
RelatedSerbia Parliamentary Election: Vučić at 60.5%, Fair Higher
Where 90.5 cents sits against 0.88
Our fair probability of no change on 29 October is 0.88. A 25 basis point increase is 0.115. A 25 basis point cut is 0.002, an increase of 50 or more is 0.002, and a cut of 50 or more is 0.001. The no-change price of 0.905 sits above 0.88. On this site that reading is above fair. It describes the gap. It is not an instruction to take a side of the 25 basis point increase leg, or of the hold.
The 0.88 has two steps. Surveys in the September account, and Lagarde's refusal to point at the next meeting, are a hold prior for a meeting with no new projection. We put that prior at 0.93 before the flash. The 2 October print is a 5 point haircut, moved into the quarter-point increase. A 0.6 point jump in the headline is information. It is not a new regime while energy did most of the move and the underlying print is still unpublished. Fifteen points would be the haircut if wages were already accelerating. They were not.
Nothing moves into a cut. A lower deposit rate, against a 3.8% flash, is not an outcome the September account contemplates. Nothing material moves into 50 basis points. Every member backed Lane's 25, not 50. The small probabilities on those legs are there so the distribution sums to 1.
What is left is 2.5 cents, 0.905 against 0.88. The bid-ask on the hold is one cent and the book under it is $11,721. A band of about 0.84 to 0.92 covers the 16 October release, and 0.905 sits inside the top of that band, above the point. Above fair, and not a wide miss. A final HICP that revises September up, a core rate excluding energy and food well above the staff's 2.5% for 2026, or a voting member tying the flash to a move on 29 October, would push the point down through 0.84. A revision the other way, or a repeat of the gradual-return line from someone who votes, would push it back toward 0.93.
Questions the contract actually answers
When is the October decision announced?
The Governing Council meets on 28 and 29 October 2026 in Frankfurt. The ECB calendar puts the press conference on 29 October, after day two. The Polymarket event ends at 03:59 UTC on 30 October and can resolve earlier, once the statement with the deposit facility rate is out. The next monetary policy meeting, with a new projection round, is on 16 and 17 December.
Which of the three ECB rates does the book use?
The deposit facility rate. Settlement is the change in that rate, in basis points, against the level before the meeting. It is 2.50% after the 10 September decision, from 16 September. The refinancing rate is 2.65% and the marginal lending rate is 2.90%. Those two do not settle this contract. A move that hit only the refinancing rate would not, on the wording, pay the increase legs.
Why are three legs stuck at 0.0005 if they still have liquidity?
A displayed price and a stock of liquidity are different things. The cut legs and the 50 basis point increase show an ask at 0.001, no bid, and a last trade at 0.001, even though each has more liquidity than the no-change leg's $11,721. The probability on the screen is the floor of the tick. Five-figure liquidity at that ask is a resting offer, not a forecast that the council is about to cut.
Does the 3.8% flash mean the hold is wrong?
It means the hold should not be 93 cents, which is where a pure reading of the September surveys would have left it. It does not mean the hold should be 70. The jump is real, it is mostly energy, and services moved up by 0.2 points. The ex-energy-and-food figure for September is not in the 2 October overview. Our haircut is 5 points, from 0.93 to 0.88, and it sits in the quarter-point increase.
Is this a view on the euro?
No. The September account notes a 1.9% rise in the euro against the dollar between the July and September meetings, inside the financial-conditions discussion. That sentence is in the past, and it is theirs. This page has no target for the euro, no path for any dollar pair, and no claim about any other cross. The only price it judges is the no-change leg of this contract.
What would make 0.88 the wrong fair value before 29 October?
A 16 October HICP that revises the 3.8% flash up, or a core rate excluding energy and food above the staff's 2.5% for 2026, would pull the hold fair value down. A revision the other way, or a voting member repeating that expectations are anchored and the return can be gradual, would push it up. A fresh energy spike large enough to fail that expectations test would move more than a tenth. A quiet fortnight would leave 0.88 alone.
This is analysis of a prediction-market contract, not advice and not a solicitation to trade. Fair value is an editorial probability, not a promise of how the Governing Council will vote. Contracts can settle at zero. Prices move, liquidity on the hold is about $11,721, and you can lose what you stake. The European Central Bank's own releases remain the record of what it decided.