
Is USD/PLN pricing a weaker zloty, or a stronger dollar that the zloty has not confirmed? That is the question in the 2 October ECB reference, and the crosses answer it. USD/PLN printed 3.8998, up from 3.8710 on 1 October, a rise of 0.74 percent and the highest fix in this series back to 1 April. EUR/PLN, on the same two days, moved from 4.3735 to 4.3775. That is 0.09 percent. EUR/USD fell from 1.1298 to 1.1225, down 0.65 percent. Zlotys per dollar equal zlotys per euro divided by euros per dollar, so almost the whole of that session was the dollar leg. Warsaw did not reprice Poland on the day. The pair wore a dollar move, and it wore it at a six-month high because the weeks before had already done the lifting.
A one-day split can be noise. The stretch since the Federal Reserve's hike is not. From the 16 September fix to 2 October, USD/PLN rose from 3.7681 to 3.8998, which is 3.5 percent. EUR/PLN rose from 4.3473 to 4.3775, or 0.7 percent. EUR/USD fell from 1.1537 to 1.1225, or 2.7 percent. Roughly four-fifths of the rise in the dollar pair since that Fed day is the dollar. The zloty-versus-euro drift is real, and it is the smaller part. Narrow the window again and the zloty drops out. EUR/PLN's high across September and early October was 4.3823 on 24 September, not on 2 October. From that day to the latest fix the euro cross eased 0.11 percent, to 4.3775, while USD/PLN rose from 3.8553 to 3.8998, or 1.15 percent, because EUR/USD fell from 1.1367 to 1.1225.
The dollar pair made its high on a day the zloty was slightly firmer against the euro than at the September peak in the cross.
Saturday 3 October has no new ECB reference. Figures here were pulled that day from Frankfurter's republication of ECB rates for Friday 2 October, unless another date sits next to the number. They are reference rates, not a live tick. The ECB publishes the underlying fixes.
- USD/PLN 3.8998 on the ECB reference for 2 October 2026, from 3.8710 on 1 October, up 0.74 percent.
- EUR/PLN 4.3775 and EUR/USD 1.1225 on the same fix. The euro cross rose 0.09 percent. The dollar rose 0.65 percent against the euro.
- NBP table A mid for the dollar was 3.8881 on 2 October, from 3.8762 on 1 October, up 0.31 percent, and 0.0117 below the ECB print. NBP table A.
- NBP reference rate 3.75 percent, held on 8-9 September, with the lombard rate at 4.25 percent and the deposit rate at 3.25 percent. Next decision meeting 6-7 October. No October decision exists yet.
- The Fed raised the funds range by a quarter point on 16 September, to 3.75 to 4 percent, unanimously. Kevin Warsh read the median appropriate rate as 4.1 percent at the end of 2026.
- Polish CPI flash for September: 4.0 percent on the year and 0.7 percent on the month. Transport fuels were up 36.1 percent on the year. Statistics Poland, 30 September. Preliminary.
- Moody's cut Poland from A2 to A3 on 18 September and moved the outlook to stable. It looks for a deficit around 7 percent of GDP in both 2026 and 2027, in the Ministry of Finance account of the action.
What 2 October actually was
Traders who live on one pair will call 3.8998 a zloty low. On the euro cross it is not. Through September, EUR/PLN traded between 4.3103 on 7 September and 4.3823 on 24 September, a band of about 1.7 percent. The 2 October print, 4.3775, sits near the top of that band and a little under the high. From 1 September, EUR/PLN is up 1.1 percent, from 4.3313. USD/PLN over the same span is up 4.4 percent, from 3.7371. The dollar pair ran. The euro pair walked.
The identity is worth doing in public. On 2 October, 4.3775 divided by 1.1225 is 3.8998. On 24 September, 4.3823 divided by 1.1367 is 3.8553, the ECB dollar fix that day. Nothing below assumes a model of Polish growth. It assumes the identity still holds in December, and then asks which leg moves.
If EUR/PLN stays at 4.3775, the levels map straight into the dollar.
| USD/PLN level | Versus 3.8998 | EUR/USD if EUR/PLN stays 4.3775 |
|---|---|---|
| 3.65 bear | 6.4 percent lower | 1.199 |
| 3.82 base | 2.0 percent lower | 1.146 |
| 3.8998 anchor | 2 October ECB fix | 1.1225, the fix itself |
| 4.05, where the base fades | 3.9 percent higher | 1.081 |
| 4.15 bull | 6.4 percent higher | 1.055 |
A base of 3.82, with the euro cross unchanged, is a partial give-back in the dollar toward 1.15, not a rally in the zloty. A bear case of 3.65 needs EUR/USD near 1.20. A bull case of 4.15 needs EUR/USD near 1.05, or a break in EUR/PLN that September did not deliver. Those are different bets.
The dollar leg is the same one in the EUR/USD forecast from 3 September. The ECB reference that day was 1.1615. By 2 October it was 1.1225, down 3.4 percent. Poland's own fix is quieter on the day itself. Table A put the dollar at 3.8762 on 1 October and 3.8881 on 2 October, a rise of 0.31 percent, less than half the ECB step. Direction agrees. The levels here are struck from the ECB reference, because that is the history on the chart. Struck from the NBP mid, 4.15 is still above the market and 3.82 and 3.65 are still below it.
The gap that flipped on 16 September
On 16 September the Federal Open Market Committee raised the funds target by a quarter point, to 3.75 to 4 percent. The vote was unanimous. The statement said inflation remains elevated. A quarter-point rise to that range means the previous range was 3.50 to 3.75 percent. Before the decision, the top of the Fed range sat on the NBP reference rate. After it, the floor sits on 3.75 percent and the ceiling is 25 basis points higher. The midpoint, 3.875 percent, is 12.5 basis points above the Polish rate. Carry of that size does not dictate a currency. It changes the sign. Dollars no longer earn less than zlotys at the middle of the Fed range.
"The plain fact is that inflation is too high and has been for too long."
Kevin Warsh, Chair of the Federal Reserve, said that at the 16 September press conference. In the median of his colleagues, which he read out without filing a dot of his own, total PCE inflation runs at 3.7 percent this year, and the appropriate funds rate is 4.1 percent at the end of this year and again next year. He put August's 12-month PCE change, inferred from CPI and PPI, at around 3.6 percent. A further quarter point would take the range to 4 to 4.25 percent. That is what 4.1 percent implies. It is not a promise. Our 30 September note on the October Fed decision found the contract in line with fed funds futures. In line is not a hike already delivered.
The council in Warsaw has been still. On 8-9 September it kept the reference rate at 3.75 percent, the lombard rate at 4.25 percent and the deposit rate at 3.25 percent. The communique also left the rediscount rate at 3.80 percent and the discount rate at 3.85 percent. August CPI, on the flash then in hand, had risen to 3.4 percent from 3.0 percent in July, led by fuel. Core inflation excluding food and energy, the note said, could be estimated to have risen too. It gave no core figure, and this piece will not invent one. The next decision meeting on the NBP calendar is 6-7 October. It has not happened.
On the September flash, 3.75 percent sits 0.25 percentage points under headline CPI. The flash can be revised, and Warsh's US figures are PCE, not CPI, so a real-rate contest would be false precision. The usable fact is narrower. The Polish reference rate is no longer above the Fed's midpoint, and headline inflation has stepped up to a number that rate does not cover.
A 4.0 percent flash that is mostly fuel
Statistics Poland's flash for September, dated 30 September, put consumer prices 4.0 percent above September 2025 and 0.7 percent above August. The office says the flash is preliminary and subject to change. Food and non-alcoholic beverages were 0.5 percent lower than a year earlier. Electricity, gas and other fuels were 4.9 percent higher on the year and 0.9 percent higher on the month. Fuels and lubricants for personal transport were 36.1 percent higher than a year earlier and 9.2 percent higher than in August. The release is the source.
The chart in that release draws the inflation target at 2.5 percent. August's final 3.4 percent sits just under the upper deviation line. September, at 4.0, is through it. The 15 September final had already fixed August: services up 5.6 percent on the year, goods up 2.5 percent, the month up 0.3 percent rather than the flash's 0.4. January to August was 2.8 percent above a year earlier. Chart description follows Statistics Poland's flash release. The August split is from Consumer price indices in August 2026.
Fuel at 36 percent is not a wage boom. A council that held at 3.4 percent can hold again in front of a fuel spike, or it can decide a preliminary 4.0 is the wrong backdrop for a cut while the Fed median sits at 4.1. A cut is the outcome this flash does not support. Services at 5.6 percent in August are the part a hold does not dissolve. The 6-7 October meeting will see the flash and not the full September breakdown, which was still unpublished on 3 October.
A rating cut that did not gap the Monday fix
On 18 September Moody's lowered Poland to A3 from A2, cut the issuer rating to Prime-2 from Prime-1, and moved the outlook to stable from negative. The Ministry of Finance set out the action the same day. In that account the deficit stays around 7 percent of GDP in both 2026 and 2027, growth is 3.7 percent in 2026 and 3.2 percent in 2027 after 3.6 percent in 2025, and general-government debt reaches 68.9 percent of GDP in 2027 from 59.7 percent in 2025. Defence, healthcare, investment and social spending are what keep the deficit up, with the November 2027 election named as a brake. The 55 percent prudential threshold and the 60 percent constitutional limit use the national debt definition, not the 68.9 percent ratio.
"We take this decision seriously, but calmly. The Polish economy is growing rapidly, and its fundamentals remain strong."
Andrzej Domański, Minister of Finance and Economy, wrote that on X on 18 September, in Polish. The English is the rendering in Notes from Poland, matching the post. The original adds that repairing the public finances needs every state institution, including the president. That is the political constraint Moody's also wrote down. It is not a currency forecast.
The fix after the announcement is the test. Moody's moved late on Friday. Friday's own ECB reference, 3.8076 for USD/PLN and 4.3635 for EUR/PLN, could not contain a late-evening rating action. Monday 21 September printed 3.7885 and 4.353, with EUR/USD at 1.149. Both zloty crosses were slightly firmer, not a gap weaker. The later climb in USD/PLN, from 3.7885 that Monday to 3.8998 on 2 October, lines up with EUR/USD falling from 1.149 to 1.1225. The rating is a slow premium, not a Monday air-pocket.
The premium can still matter by December if holders decide A3 was the first notch rather than the last. Moody's debt path, toward the high 60s on the EU measure by 2027, works through bonds and only then through the currency, and only if the NBP does not answer with a higher reference rate. That is a bull case for USD/PLN, meaning a weaker zloty. It is not what 2 October was.
Three paths on one chart
The series is the ECB reference on every business day from 1 April to 2 October 2026. The low is 3.588 on 17 April. The 31 December 2025 fix was 3.5923. From there to 3.8998 is 8.56 percent. From the April low it is 8.69 percent. From 2 October 2025, at 3.6213, it is 7.69 percent. A dollar year, with September the steep stretch of a climb that was already between 3.70 and 3.81 for much of the summer.
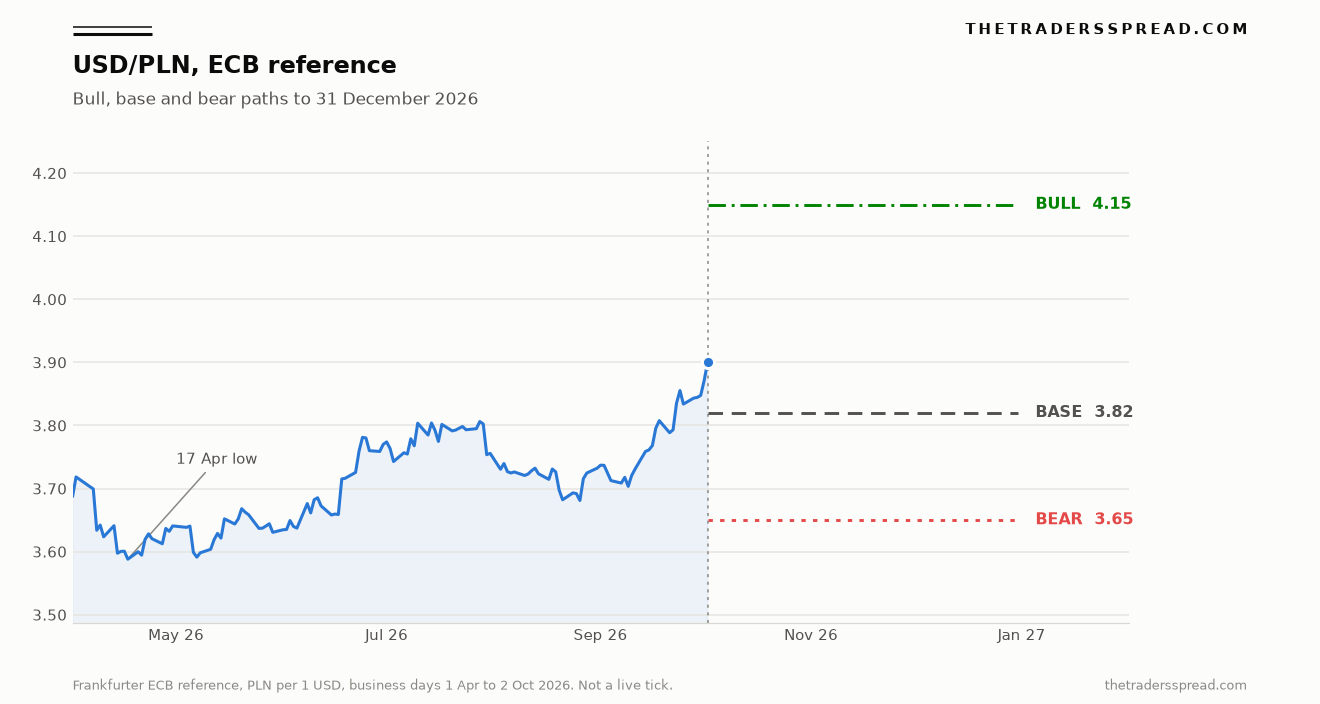 ECB reference, business days, with scenarios to 31 December. Not a live tick.
RelatedUSD/SEK Forecast: 10.60 Bull Case vs 9.35 Bear Case
Bull at 4.15, base at 3.82, bear at 3.65. The lines start at the last fix and run to 31 December. They are scenarios. The same shape of question, a dollar pair that stopped following the local story, is what the USD/NOK forecast argued for September: the cross followed the dollar rather than the barrel. Here the story that failed to confirm the high is EUR/PLN.
Read 3.82 against the year, not against the headline. It is 2.0 percent under the 2 October fix and still about 6.3 percent above 3.5923. The base gives back the early-October dollar overshoot and a slice of September. It keeps most of the year's gain. At 3.65 the pair would be 6.4 percent under the anchor, and still about 1.6 percent above the end-2025 fix and about 1.7 percent above the April low. That is a large retracement, not a return to the spring. At 4.15 the pair would be a further 6.4 percent higher, about 15.5 percent above the end-2025 fix. A different year from the one already on the tape.
The call into 31 December
Our base is 3.82. The weight on it is 50 percent. The weight on 4.15 is 30 percent. The weight on 3.65 is 20 percent. Those are our scenario weights, not an options price, and not an instruction. The base is only 2 percent under 3.8998, which is why conviction on the fade is 3 out of 5. The anchor is the ECB print itself, 3.8998. The level that retires the fade is 4.05, about 3.9 percent higher. At 4.05, with EUR/PLN still near 4.38, EUR/USD would be near 1.08, and "partial give-back" would be a late description.
3.65 is not the base because a stable euro cross gets there only if EUR/USD is near 1.20, and the median Warsh read out is 4.1 percent at year-end. The euro cross also rose 0.7 percent from the Fed day to 2 October, so the zloty has not started the firming that path needs. 4.15 is not the base either. With EUR/PLN frozen it is EUR/USD near 1.05, another large dollar leg after the 3.4 percent move since 3 September. The other route, a break of several percent in the euro cross, did not happen in a September range of about 1.7 percent, and the cross is off its high.
What would move the weights. An NBP hike on 7 October, or a dollar reversal that takes EUR/USD back through 1.16 while EUR/PLN stays under 4.38, would lift 3.65 and cut 4.15. At 1.16 and an unchanged 4.3775, USD/PLN is near 3.77, the neighbourhood of the base, not yet 3.65. Reaching 3.65 still wants more dollar weakness than one bounce, or a zloty that firms against the euro. A second Fed hike, delivered while the council holds, and EUR/PLN through 4.3823 with momentum, would lift 4.15 and retire 3.82.
The disconfirmation is specific. If the next ECB references show EUR/PLN rising in line with USD/PLN, the split in the opening is finished. The pair would be a zloty story, and a base case borrowed from a fading dollar would be the wrong borrow. Until that happens, 3.8998 is a dollar print sitting on a smaller zloty drift.
Questions that actually come up
Is 3.8998 a live tradable price?
No. It is the ECB reference for Friday 2 October 2026, taken on Saturday 3 October from Frankfurter. There is no Saturday reference. The NBP table A mid that day was 3.8881. A dealing price on Monday can sit away from both. The levels 4.15, 3.82 and 3.65 are scenarios around the ECB print, not bids.
Does a higher USD/PLN mean a stronger zloty?
It means the opposite. USD/PLN is zlotys per dollar. At 3.8998 a dollar costs more zlotys than at 3.8710 the day before, so the zloty is weaker against the dollar. The bull case in the title, 4.15, is a weaker zloty. The bear case, 3.65, is a stronger zloty. EUR/PLN works the same way, and that number barely rose on 2 October.
Will the NBP cut or hike on 6-7 October?
This piece does not know. The council has not voted. It held at 3.75 percent on 8-9 September with August CPI at 3.4 percent. The September flash is 4.0 percent, preliminary, led by transport fuel at 36.1 percent on the year. That makes a cut hard to square with the communique already published. A hike is possible and is not our base. Treating either result as decided is how a forecast goes stale before the meeting.
What retires 3.82 before December?
An ECB reference at or through 4.05. That is about 3.9 percent above 3.8998, via the dollar, via the zloty against the euro, or via both. One session like 2 October will not do it. A run of them, with EUR/PLN joining, would. On the downside, a print under 3.70 would mean the fade has gone past the base, particularly if EUR/USD is back near 1.18 or higher and the 3.65 case is the one being priced.
This is analysis, not a recommendation. It is not an instruction to trade USD/PLN, the zloty, or any other instrument. The levels are scenarios around an ECB reference rate. Foreign exchange can travel through a scenario in a single session, and the reference rate is not the price a position is filled at. Capital is at risk.