
Freeport-McMoRan closed at $70.79 on 29 September 2026, 80.5% above the $39.22 close on 30 September 2025.
The gain came after the September 2025 mud rush at Grasberg, not before it. PT Freeport Indonesia sold 153 million pounds of copper in the second quarter of 2026, against 443 million a year earlier, a drop of 65.5%. The common stock almost doubled while the operation that used to set the story was still selling about a third of last year's quarterly copper.
The pounds on the NYSE line are fewer than the headline. The 23 July 2026 earnings release guides consolidated copper sales for 2026 to about 3.1 billion pounds. The July sales slide assigns 0.81 billion of those pounds to noncontrolling interests. The difference is 2.29 billion. Freeport's stake in PT Freeport Indonesia is 48.76%. A price that uses the full 3.1 billion is counting metal the share does not own.
The figures behind the close
- Nasdaq last sale $70.79 on 29 September 2026, down $1.17 from $71.96. Up 39.4% from the $50.79 close on 31 December 2025. 11.8% under the $80.24 high of 26 August. The 30 September 2025 session low was $37.20.
- Second-quarter net income to common stock $984 million, $0.68 a share, against $772 million. Adjusted net income $1,080 million, $0.74. Realized copper $6.17 a pound, against $4.54.
- Grasberg rate path: about 65% of capacity in the second half of 2026, about 80% by mid-2027, near full capacity by the end of 2027. Block 1S restart targeted for mid-2027.
- 2026 operating cash flow about $8.3 billion at $6.00 copper, $4,000 gold and $30 molybdenum for the second half. Each extra $0.10 of copper is about $150 million. Capital spending about $4.3 billion.
- COMEX December 2026 copper $6.656 at 3:19 a.m. Eastern on 30 September 2026, Yahoo Finance delayed quote, up $0.053 from $6.603. Not the subject of this forecast.
- 30 June 2026: cash $4.1 billion, total debt $9.4 billion, policy net debt $2.1 billion excluding $3.2 billion of downstream debt. Diluted shares 1,443 million, about $102.1 billion at $70.79.
A ramp, not a restored mine
Seven people died in the mud rush. Kathleen L. Quirk, president and chief executive, wrote in the 2025 sustainability report, in a letter dated 22 April 2026, "We are deeply saddened by the tragic loss of seven team members in the unprecedented external mud rush incident at PTFI's Grasberg Block Cave underground mine and the two additional team member fatalities that occurred in separate workplace incidents in 2025." Frances Fragos Townsend, chair of the corporate responsibility committee, wrote in the same report: "Regrettably, Freeport experienced three fatal events during 2025, including the heartbreaking loss of seven workers in the Grasberg mud rush incident." The report also says Freeport supplied about 7% of the world's mined copper in 2025. The equity question for the next two quarters is narrower than that franchise.
Blocks 2 and 3 were remediated in the first quarter of 2026. The ramp started at the end of March. In the second quarter those blocks hit the rates the company had set, and the haulage upgrades were on schedule. Block 1S is the unfinished piece. The 23 July slide deck aims its restart at mid-2027, with clean-up, a plug and infrastructure repairs still underway.
Do not read the 65% rate as the 65.5% sales drop. The rate is a second-half operating plan against normal capacity. The 65.5% is 153 million pounds of PTFI copper sales against 443 million in the second quarter of 2025. One looks forward. The other is a completed quarter. PTFI's full-year sales guide is about 0.7 billion pounds of copper and 650 thousand ounces of gold, with production ahead of sales because about 100 million pounds of copper and 50 thousand ounces of gold are deferred in smelter inventory.
Idle facility and restoration costs were $284 million in the second quarter and $690 million in the first half, outside unit net cash costs and inside cash. Operating cash flow of $2.0 billion in the quarter included $0.7 billion of pre-tax insurance proceeds, after $0.6 billion of working-capital uses. Not a run-rate. Third-quarter guidance is 750 million pounds of copper and 160 thousand ounces of gold. Gold sales in the second quarter were 123 thousand ounces, under an April estimate of 140 thousand, on shipment timing.
What the common stock owns
Freeport consolidates PTFI and manages it. The economic interest is 48.76% through 2041. A February 2026 memorandum with the Indonesian government would hold that stake through 2041 and cut it to about 37% from 2042 if the licence extension is completed. PTFI filed the IUPK application in June 2026. The process was still open in the July release. It does not change a March 2027 quarter. It does change what a 2040s Grasberg is worth to this share.
Apply 48.76% to the 0.7 billion pound PTFI sales guide and the parent's 2026 claim on Indonesian copper sales is about 340 million pounds, near an eleventh of the consolidated 3.1 billion. Gold is the reverse. The consolidated gold guide for 2026 is also 650 thousand ounces, matching the PTFI figure, so essentially all of the gold is Indonesian and just under half of the economics stay with the parent. The second-quarter PTFI unit net cash credit was $0.81 a pound of copper, down from $0.99 a year earlier because copper volume was lower. That credit is the gold.
The July slide states the same split for the whole company. Copper sales are marked at 3.6 billion pounds in 2025, 3.1 billion in 2026, 3.8 billion in 2027 and 4.1 billion in 2028. Noncontrolling interests take 1.11 billion, 0.81 billion, 1.13 billion and 1.27 billion pounds of those years. On the rounded 2026 and 2027 figures:
- 2026: 3.1 minus 0.81 leaves 2.29 billion pounds with the parent.
- 2027: 3.8 minus 1.13 leaves 2.67 billion pounds.
- The consolidated increase is 0.7 billion pounds, about 23%. The increase for Freeport-McMoRan shareholders is 0.38 billion, about 17% on 2.29 billion. Close to half of the extra pounds are the minority's.
Gold on that slide goes from 0.65 million ounces in 2026 to 1.0 million in 2027, with minorities marked at 330 thousand and then 512 thousand. The parent's ounces rise from about 320 thousand to about 488 thousand. A little over half of the increase is not this share's. The multiple still moves on Grasberg headlines, because it is paying for the ramp and the gold credit, not for a clean claim on every pound.
The Americas carried the quarter, and the ownership is cleaner. US copper sales are guided at about 1.4 billion pounds for 2026, South America at about 1.0 billion. Second-quarter unit net cash costs were $2.94 in the US, on a $6.25 realized price, and $2.48 in South America, on $6.11. Year guides are $2.96 and $2.56. The consolidated guide of $1.90 is that low only because Indonesian credits pull the average down. Morenci is already in the US figures at a 72% interest. The Cerro Verde stake rose in May 2026 from 55.08% to 55.66%.
Leaching does not wait on Block 1S. Incremental copper was 47 million pounds in the second quarter and 101 million in the first half, with a targeted run rate of 300 million pounds by the end of 2026 from US and South American stockpiles. Those pounds sit closer to the parent than a Grasberg pound does.
A cash case written at $6
The $8.3 billion cash-flow figure assumes $6.00 copper, $4,000 gold and $30 molybdenum for the second half. After $4.3 billion of capital spending the consolidated residual is about $4.0 billion. On 1,443 million diluted shares that is about 3.9% of the $102 billion equity value, and the parent's share is smaller. The release estimates $2.0 billion of 2026 net income for noncontrolling interests on that price case, about 24% of consolidated pre-tax income. Some of that is accounting, not a cash distribution. It is still a claim on the mines.
Net debt of $2.1 billion sits under a policy band of $3 billion to $4 billion that excludes $3.2 billion of downstream project debt. Cash subtracted from total debt is $5.3 billion. Both figures are in the release, and they are not interchangeable.
Yahoo Finance's delayed quote put December 2026 COMEX copper at $6.656 at 3:19 a.m. Eastern on 30 September, a day range of $6.611 to $6.663. The copper forecast covers the metal. The equity question is the gap to $6.00. The release moves second-half operating cash flow by about $150 million per $0.10 of copper. From $6.00 to $6.656 is $0.656, which is $984 million if the sensitivity is linear and the volume case holds. Added to $8.3 billion, the year would be near $9.3 billion, and the residual after capital spending nearer $5 billion than $4 billion. Still consolidated. Still not a parent free-cash-flow yield.
A second sensitivity in the same release is easy to mix up with that one. At 30 June, 99 million pounds of provisionally priced copper, net of intercompany sales and minorities, sat on the books at $6.07. Each $0.05 away from that price is about $9 million of 2026 revenue and about $3 million of net income to the common stock. The London settlement the release cites for 22 July was $6.30. The $3 million is a mark on metal already sold. The $150 million is unsold second-half volume. Using the smaller figure for the whole half understates the torque.
This article has no live gold price. The cash case uses $4,000 an ounce. The second quarter realized $4,520. At $40 million of operating cash flow per $100, that $520 gap is about $208 million if the quarter's realized price simply carried on. An illustration, not a gold call. The gold forecast is where the ounce belongs. Here the ounce is why PTFI can show a credit per pound, and why only part of that credit reaches the common stock.
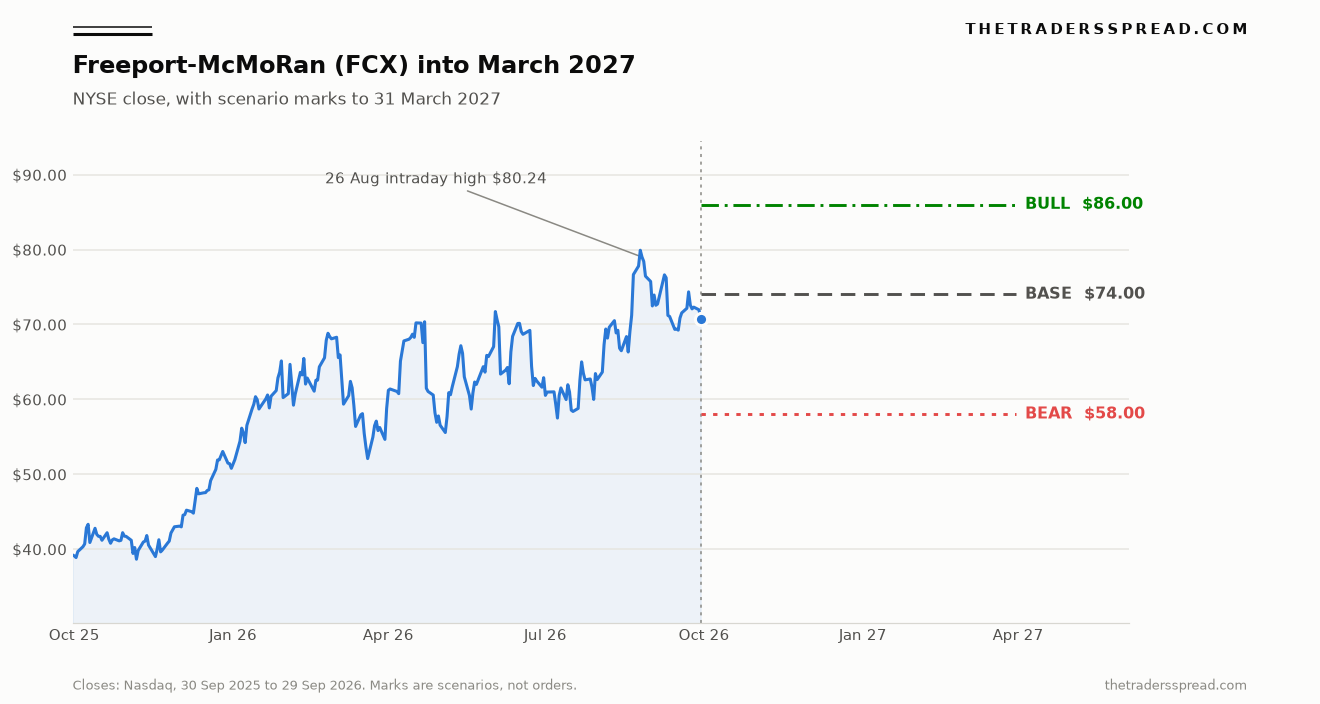
Closes on the chart are Nasdaq's, 30 September 2025 through 29 September 2026. The three lines run to 31 March 2027. They are this desk's scenarios. Freeport publishes no share-price target.
| Mark | Price | Against $70.79 | What has to show up in the reports |
|---|---|---|---|
| Bear | $58 | 18.1% lower | Second-half rate misses about 65%, Block 1S slips past mid-2027, or copper is back through $6.00 |
| Base | $74 | 4.5% higher | Third-quarter copper sales near 750 million pounds and the 3.1 billion pound year holds, without a new high |
| Bull | $86 | 21.5% higher | The step from about 2.29 billion attributable pounds to about 2.67 billion looks intact, and copper stays near the late-September tape |
Other exchange metals are not a model for this share. Aluminium rose 12.9% in 2026 as LME stocks halved. Freeport can lag a firm metal. From the 8 September close of $76.62 to the 10 September close of $71.21 the share fell 7.1%, on about 22.2 million shares that day. The filing that week, an 8-K dated 8 September, only extended PTFI's revolver to September 2031. Drawings were still $250 million. No new volume guide.
$74, $86 and $58
The horizon is 31 March 2027, after a fourth-quarter report and before the mid-2027 check on an 80% rate and a Block 1S restart. Full capacity is an end-2027 mark. A March price that assumes the district is already normal is not the forecast on the slides.
Base, $74. That is 4.5% above the 29 September close and 35 cents under the $74.35 close of 22 September. It is the July plan arriving roughly as written: third-quarter copper near 750 million pounds, the year near 3.1 billion, the second-half Grasberg rate near 65%, unit costs near $1.90 for the year and nearer $2.00 in the third quarter. Copper can stay above $6. The share does not have to clear $80.24. An 80.5% gain in a year has already paid for a large part of a 17% step in the pounds this stock owns.
The dividend is not the case. On 24 June 2026 the board declared $0.15 a share, half base and half variable, paid 3 August. Four quarters at that declared rate would be $0.60, or 0.85% of $70.79, and both parts are at the board's discretion. Repurchases in the second quarter were 1.7 million shares at an average of $64.34. By 22 July the $5 billion authorisation had absorbed 55.4 million shares at an average of $39.80. That is a balance sheet with room under its net-debt band, not a reason to own the share.
Bull, $86. That is 21.5% above the close and 7.2% above the 26 August intraday high. Two conditions, separate ones. The attributable step from about 2.29 billion pounds to about 2.67 billion has to look intact when the fourth quarter is out, which means the 65% rate held and Block 1S has not been delayed. And the gap from $6.00 to a tape near $6.66 has to look like a second-half average, not one early-morning indication. The $984 million is that gap run through the company's sensitivity. It is not a booked cash-flow number.
RelatedBoeing (BA) Stock Forecast: $240 Bull Case vs $165 Bear Case
$86 does not include Kucing Liar, a 2030s ramp toward about 750 million pounds of copper a year, with about $1.4 billion spent by 30 June 2026 and roughly $4 billion more through 2033. Bagdad's studies, a possible decision in the second half of 2026, describe 200 to 250 million extra pounds and capital about 30% above a 2023 estimate of $3.5 billion. El Abra's March 2026 filing in Chile is sized at over 700 million pounds a year. A decision can be news before March. The pounds cannot.
Bear, $58. That is 18.1% under the close, and just under the $58.78 close on 31 March 2026. The 31 July close was $62.63 and the 3 August close was $63.64, so $58 breaks that shelf rather than retesting it. It is the spring-to-September rally given back: a second-half rate that misses 65%, a Block 1S restart pushed past mid-2027, idle costs stuck near the $284 million second-quarter level, or copper back through $6.00. It is not a return to $39.22. That price was the window just after the mud rush, before Blocks 2 and 3 restarted.
A third-quarter copper sales print clear of 750 million pounds, with gold shipments no longer lagging, would pull $74 toward $86. A cut to the 3.1 billion pound year, or a Block 1S date moved past mid-2027, would retire $74 and leave $58 as the mark that fits the new plan.
Quirk's line in the July release is the company's version of the split. "The Freeport team achieved strong results in the second quarter, supported by solid execution of our operating plans and favorable pricing for our products. We made steady progress with our Grasberg ramp-up and our Americas operations delivered excellent performance, which resulted in year-over-year improvements to bottom-line results, demonstrating the strength of our diversified portfolio." Earnings rose from $772 million to $984 million, about 27%, while PTFI copper sales fell 65.5%. The US mines are why a Grasberg slip dents the multiple and does not zero the equity.
Questions that keep attaching to this share
Does $86 mean Grasberg is fully back by March 2027? No. The July slides put the district near 65% of capacity in the second half of 2026, near 80% by mid-2027, and near full capacity at the end of 2027. Block 1S is a mid-2027 restart target. $86 is the case in which that timetable still looks credible and copper has not fallen back to the $6.00 price in the cash-flow case.
Does the share own all 3.1 billion pounds? No. The July slide assigns 0.81 billion pounds of the 2026 copper sales estimate to noncontrolling interests. The stake in PT Freeport Indonesia is 48.76% through 2041, and the February memorandum would take it to about 37% from 2042 if the extension is completed. US sales are closer to the parent, with Morenci already counted at 72%.
Why is cash flow guided at $8.3 billion with copper above $6.60? The 23 July guide assumes $6.00 copper for the second half, plus $4,000 gold and $30 molybdenum. Each extra $0.10 of copper is about $150 million of second-half operating cash flow. From $6.00 to the $6.656 indication on 30 September, that is $984 million, and only if volumes and costs hold.
What does $58 go back to? It is just under the $58.78 close on 31 March 2026, before the run to the August high, and below the late-July closes near $63. It is not the $39.22 close of 30 September 2025, and it is not a shutdown case. It is the spring re-rating handed back.
Is the dividend a fixed yield? The board declared $0.15 on 24 June 2026. The release says later base and variable dividends depend on results, cash needs and the board's judgement. Four times that declaration is $0.60, or 0.85% of the 29 September close. One decision is not a schedule.
What would retire the base case? A cut to the 3.1 billion pound copper year, or a Block 1S restart dated after mid-2027, would. A third-quarter sales figure well above 750 million pounds of copper, with gold catching the 160 thousand ounce guide, would do the opposite and pull the base toward $86. The licence step-down in 2042 is a different question.
This is analysis of a share price, not a recommendation to trade Freeport-McMoRan or any other security. The $58, $74 and $86 marks are scenarios drawn from company disclosures dated 23 July 2026 and from prices checked on 29 and 30 September 2026. Volumes, the Grasberg ramp, copper, gold, costs, the Indonesian licence and minority interests can all move the result. Capital is at risk, including a total loss of the amount committed.