

Will Banxico keep the overnight interbank target at 6.50 percent when the Governing Board publishes the 5 November statement, or has the cut leg in the contract book run ahead of the central bank's own record? Polymarket's event was live at 07:52 UTC on 4 November 2026, volume $301,311 and liquidity $36,661, and the gamma record still listed it as open. The unchanged-target leg was marked at 71.5 cents. A 25 basis point cut was marked at 29.35 cents. Beside those prices, Banco de México's October survey of private-sector specialists, released on 3 November, still carries a median end-2026 funding rate of 6.50 percent and a mean of 6.49 percent. The contract and the survey are expressing different amounts of doubt about the same rate. The full board is the Banxico decision event on Polymarket. Links to Polymarket are affiliate links, from which The Traders Spread may earn a commission at no cost to you.
The move under those prices is recent, and it is large relative to the liquidity on the hold. Gamma's one-day change on the 25 basis point cut was plus 22.25 cents, and the one-day change on the unchanged target was a decline of 20.5 cents, in that same 4 November read. Subtract the week-change and month-change fields from the current cut price and the earlier marks sit near 11.8 cents and near 2.5 cents. The same arithmetic puts the hold near 88 cents a week earlier and near 94.5 cents a month earlier. The survey median stayed at 6.50 while the contract moved. Fair value here follows the 24 September statement and that survey, and it gives the one-day print only a partial weight. On the unchanged-target leg the fair value is 84 percent, so the traded price of 71.5 cents sits below it.
Key facts
- The Polymarket event was open at 07:52 UTC on 4 November 2026, with volume of $301,311 and liquidity of $36,661 (Polymarket gamma API, 4 November 2026).
- The unchanged-target leg was priced at 71.5 cents and the 25 basis point cut at 29.35 cents, and the five outcome prices summed to 101 cents (Polymarket outcomePrices, 4 November 2026).
- Banxico's Governing Board voted unanimously on 24 September 2026 to keep the overnight interbank target at 6.50 percent, with every member present (Banco de México monetary policy statement, 24 September 2026).
- INEGI put headline inflation at 3.62 percent and core inflation at 3.78 percent in the first fortnight of October 2026 (INEGI indicator bulletin 633/26, 22 October 2026).
- The October survey median for the interbank funding rate at the end of 2026 is 6.50 percent, the mean is 6.49 percent, and the standard deviation is 0.08 percentage points (Banco de México survey, 3 November 2026).
- The latest ECB reference rate available through Frankfurter was 18.5974 pesos per dollar on 3 November 2026 (Frankfurter, 3 November 2026).
- Banxico's calendar places the statement on 5 November, with announcements at 13:00 CST on Thursdays, and the following statement on 17 December (Banco de México calendar, retrieved 4 November 2026).
1) Five prices and a one-cent overround
The event splits one decision into five mutually exclusive legs: a cut of 50 basis points or more, a cut of 25 basis points, an unchanged target, a hike of 25 basis points, and a hike of 50 basis points or more. Resolution follows the change in the overnight interbank target at the November meeting, using Banco de México's statement. The calendar puts that statement on 5 November at 13:00 CST, with the next statement on 17 December. A cancelled meeting, or one pushed past the start of the next scheduled meeting, resolves to the unchanged bracket.
Outcome prices are the column set against fair value, and on the two live legs they sit inside the spread. The cut's bid and ask were 27.8 and 30.9 cents, with 29.35 between them. The hold's bid and ask were 71 and 72, with 71.5 between them. The cut's last trade, 34.2 cents, sits above that ask, so the print is older than the book. The hold's last trade equals the 72 cent ask. Using the last trade would make the cut look richer, and the hold would still sit below an 84 percent fair value.
| Leg | Market | Bid / ask | Last trade | Volume | Liquidity | Fair value |
|---|---|---|---|---|---|---|
| Cut of 50bp or more | 0.05% | ask 0.1 cent | 0.2 cent | $20,380 | $2,303 | 0.4% |
| Cut of 25bp | 29.35% | 27.8 / 30.9 | 34.2 cents | $111,406 | $4,542 | 14.5% |
| Unchanged target | 71.5% | 71 / 72 | 72 cents | $131,676 | $2,689 | 84.0% |
| Hike of 25bp | 0.05% | ask 0.1 cent | 0.1 cent | $31,388 | $14,561 | 0.9% |
| Hike of 50bp or more | 0.05% | ask 0.1 cent | 0.1 cent | $6,727 | $12,780 | 0.2% |
Market columns are the Polymarket gamma fields at 07:52 UTC on 4 November 2026, with volumes rounded to the dollar. The three tail rows record an ask because a usable bid was absent from those objects. Fair value is the mark in section 5.
The five outcome prices sum to 101 cents, a one-cent overround on an exhaustive ladder and a small number beside the 12.5 point gap between 71.5 and 84. Fair values below sum to 100. Event volume is $301,311 and day volume was $78,035, the hold leads volume at $131,676 against $111,406 on the 25 basis point cut, and liquidity runs the other way, $4,542 on the cut against $2,689 on the hold. The 25 basis point hike shows $14,561 of liquidity at a 0.05 percent price, which reads as posted inventory. The cut's one-hour change was minus 2.2 cents and the hold's was plus 3.5 cents, so the day move has given a little back while the day change on the cut is still plus 22.25 cents. The unchanged-target contract is the leg marked below.
2) The 24 September vote, and the line after it
The latest statement on Banxico's announcements page is dated 24 September 2026. The Governing Board maintained the target for the overnight interbank rate at 6.50 percent, and the vote line says every member was present and the decision was unanimous. The same page records holds at 6.50 percent on 25 June and 6 August, after decreases of 25 basis points on 7 May and 26 March and a February hold at 7.00 percent.
Banco de México's own account posted that 6.50 target on the morning of 4 November, which is the live setting the contract is written against, and the gamma event was still taking prices hours later.
Tasa de interés objetivo(04/11/2026), valor: 6.50 https://t.co/hEeyPENI4I
— Banco de México (@Banxico) November 4, 2026
September's forward line lists what the board will weigh: disinflation, exchange-rate pass-through, slack and inflation expectations. It also says conditions in Mexico differ from those in the United States, so policy can differ from the federal funds path. The same statement records that the Federal Reserve raised its target range by 25 basis points in September. A separate book on that US path is the Fed December decision odds page. Banxico cites the hike and then treats the next Mexican step as its own.
Between the first fortnight of July and the first fortnight of September, headline inflation rose from 3.10 percent to 3.42 percent on higher non-core inflation, while core fell from 3.95 percent to 3.79 percent. The forecast table puts fourth-quarter 2026 headline inflation at 3.5 percent and convergence to 3.0 percent in the fourth quarter of 2027. Fourth-quarter core inflation was revised up, from 3.5 percent to 3.6 percent. The balance of risks on that path remains biased to the upside, with persistent core inflation and a depreciation trend on one side and weaker activity plus the prior year's currency appreciation on the other. Activity was expected to have moderated, slack was expected to persist, yields had risen at most maturities, and the peso had been volatile. September is a unanimous hold, a slow path back to 3.0 percent, and a next vote the board left conditional, which is why a cut keeps a price. A hold book that cleared the other way, with the traded price above fair value, is the Bank of Japan unchanged-rate odds page.
3) Inflation at 3.62 percent, core at 3.78
The newest public price index is newer than the September statement and older than the contract's one-day move. INEGI bulletin 633/26, dated 22 October 2026, covers the first fortnight of October. Headline inflation was 3.62 percent at an annual rate, the fortnightly change was 0.41 percent, and the index stood at 146.739, against an annual rate of 3.63 percent in the same fortnight a year earlier.
Core inflation was 3.78 percent on the year and 0.25 percent on the fortnight. Non-core prices rose 0.98 percent, with energy and authorised tariffs up 1.85 percent, tied largely to the end of the summer electricity subsidy in 18 cities, the same channel behind the earlier rise from 3.10 percent to 3.42 percent. The core slide has stalled.
A single fortnight against a quarterly-average forecast is only a direction check: 3.62 percent sits above the 3.5 percent fourth-quarter headline forecast, and 3.78 percent sits above the 3.6 percent core forecast. The next INEGI fortnightly release is dated 24 November, after the statement, so the public inflation file for this meeting is the 22 October pair plus September's upside risk balance. That mix fits another hold at 6.50 percent. It is a weak case for a hike, which is why those fair values stay under 1 percent while slack is still in the activity paragraph.
4) Where the specialist distribution sits
Banco de México posted the October survey on 3 November 2026, from answers collected between 19 and 29 October across 40 analysis and consulting groups. The funding-rate block is the direct cross-check on the contract.
📄 El #BancodeMéxico dio a conocer los resultados de la Encuesta sobre las expectativas del sector privado: octubre 2026. Consulta aquí el documento: https://t.co/YBaPsTjdf9 pic.twitter.com/ELBzm0ZoD0
— Banco de México (@Banxico) November 3, 2026
For the funding rate at the end of 2026, the October mean is 6.49 percent and the median is 6.50 percent, against 6.51 and 6.50 in September. The end-2027 median is 6.50 percent as well. In the appendix, the October first quartile, median and third quartile all sit at 6.50. The minimum is 6.25 percent, the maximum is 6.75 percent, and the standard deviation is 0.08 percentage points, against a September minimum of 6.50, a maximum of 6.75 and a standard deviation of 0.04. October reopened a 6.25 answer, and the centre stayed on the current target. The survey text says that, for every quarter in the horizon, most analysts expect the funding rate to equal the target in force when they answered.
A median of 6.50 can sit beside a minority at 6.25, and it is a long way from a 29.35 percent chance of a November cut. If the only forecasts off 6.50 are 6.25 and 6.75, a mean of 6.49 and a standard deviation of 0.08 line up with about 7 percent of forecasts at 6.25 and about 3 percent at 6.75: the low share has to exceed the high share by about 4 points, and the two shares have to add to about 10 percent. A first quartile at 6.50 also caps the share below 6.50 at a quarter of the panel, so 7 percent fits inside the cap while 29 percent fails the standard deviation.
That 7 percent is a year-end point forecast, and 17 December still sits on the calendar after 5 November, so a respondent at 6.25 may mean either meeting. Putting the whole share on November is already a generous reading, and the traded cut is still more than four times it.
Other October medians fill in the macro. End-2026 headline inflation is 3.88 percent, from 3.87, and core inflation is 3.82 percent, from 3.90, both above the 3.0 percent convergence rate, on a December-to-December basis rather than the statement's quarterly average. GDP growth for 2026 is 1.50 percent, from 1.40, so the activity mark rose in the month the cut got more expensive. The 28-day Cete median for end-2026 is 6.45 percent, from 6.50. An earlier hold book with a higher traded price is the ECB unchanged-rate contract, and 71.5 cents is a soft print for that kind of leg.
5) Fair value on the unchanged target
The leg marked here is the unchanged target. The market price is the 71.5 cent outcome price. Fair value is 84 percent, or 0.84 as a probability. Because 0.715 is below 0.84, the call on that leg is below fair. The other four fair values are the residual that makes the column sum to 100, so the cut can be seen as rich rather than left unnamed.
RelatedThe RBA cash rate contract resolves on the board target
The year-end illustration puts about 7 percent of point forecasts at 6.25. Placing all of that mass on November, with 17 December carrying a separate meeting, is the generous base for the cut. September's conditional forward line adds 4 points: the next vote was tied to disinflation, pass-through, slack and expectations, and kept apart from a mechanical answer to the Fed. The latest inflation print is still above the 3.0 percent destination, so the cut stays inside the framework and outside its centre. The contract's day volume of $78,035 adds 3.5 points, about an eighth of the traded cut, because the flow is real and the survey median in the same window stayed at 6.50. Those pieces sum to 14.5 percent, against a traded price of 29.35 percent and a last trade of 34.2 cents that sits even higher.
A cut of 50 basis points or more would push the rate to 6.00 percent or lower, past the survey minimum of 6.25, so that leg is 0.4 percent against a market price of 0.05 percent. A 25 basis point hike matches the 6.75 maximum and the illustrative 3 percent of year-end forecasts up there, and pulling it into this meeting is a thinner event, marked at 0.9 percent against 0.05 percent in the market. A larger hike is 0.2 percent. The gap worth spending is on the hold and the 25 basis point cut.
The unchanged target is the residual: 100 minus 14.5 minus 0.4 minus 0.9 minus 0.2, which is 84.0 percent, against a market price of 71.5 percent. The gap of 12.5 points compares with a posted spread from 71 to 72, several times the spread, which is the line between a price below fair value and a price in line with it.
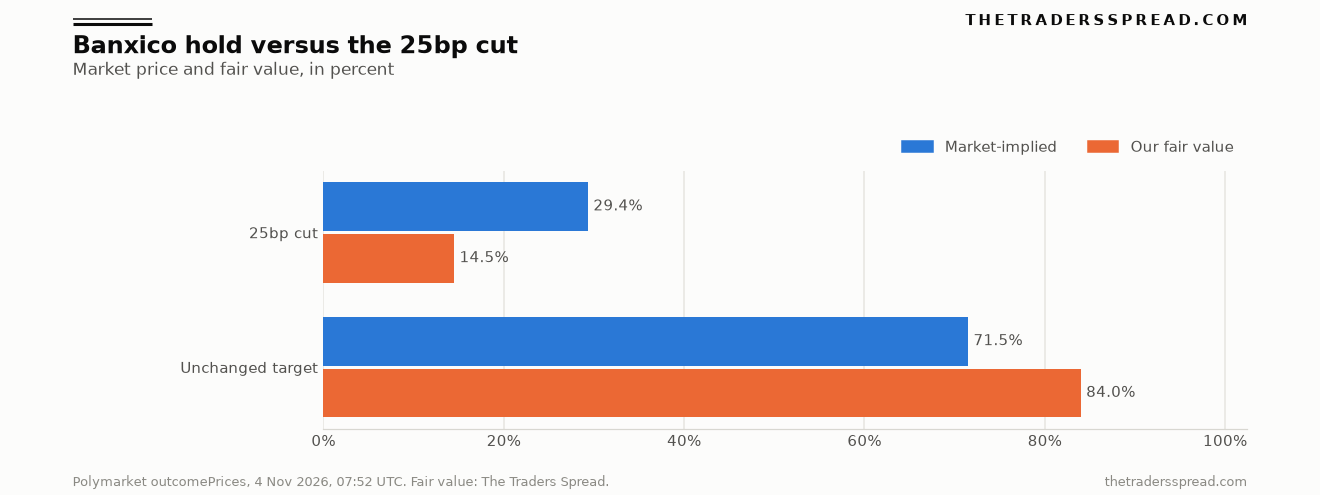
The 25 basis point cut contract is the leg that sits above the fair value assigned to it. The hold is the leg that sits below.
6) One peso print, kept as context
Frankfurter's ECB reference rate for 3 November 2026 was 18.5974 pesos per dollar, the latest date returned, and it is context only. The October survey median for the end of 2026 is 18.39 per dollar, from 17.50, with a mean of 18.25, from 17.57, and an end-2027 median of 18.64. The reference rate sits a little weaker than the year-end median. September's statement had already listed peso volatility, a depreciation trend and the prior year's appreciation among inflation risks. The probability mark stays on the rate contract alone.
7) What would move 71.5 cents before the statement
Between this reading and 13:00 CST on 5 November the public calendar is quiet: the next INEGI fortnight is 24 November, the survey is out, and the 4 November target line still reads 6.50. A new board document would move the fair value. Flow can move the traded price alone, and $2,689 of liquidity on the hold will take a small order. The session already swung the hold by about 20 cents and the cut by about 22, with a small fade in the last hour.
The fair-value gap narrows if later minutes or a survey put a much fatter share on a November cut. A standard deviation of 0.08 rejects a mass near 29 percent at 6.25, and the inflation prints in hand point toward the hold. The market gap narrows only if the price moves, up toward 84 if the one-day flow reverses, or further below 71.5 if it continues. Fair value follows the statement, the survey and the bulletin. The traded price follows the book.
Verdict
On the Banxico rate decision, the unchanged-target contract trades at 71.5 cents, against a fair value of 84 percent. The traded price sits below fair value by 12.5 points, on a one-cent spread. The 25 basis point cut at 29.35 cents sits above a 14.5 percent fair value drawn from three holds at 6.50 percent, the unanimous 24 September vote, headline inflation of 3.62 percent with core at 3.78 percent, and an October distribution whose median and 0.08 standard deviation still cluster on 6.50 at year-end. The one-day repricing is a 3.5 point allowance inside that 14.5, which is too small a piece to carry a 29 cent price.
Below fair, on the unchanged target, with the cut as the rich leg. The three tail prices in the market add up to 0.15 percent, and the three tail fair values add up to 1.5 percent. The statement that resolves the event is still ahead of the book, on a calendar that puts it at 13:00 CST on 5 November, and the contract's own end stamp is 23:59 UTC that day.
This is a probability mark on a prediction-market contract, for information only. It is not a recommendation to transact, and it is not a forecast of the peso.