
Synthetix stopped being a debt-pool token when the 420 staking system closed. CoinGecko's description still says staked SNX collateral underwrites sUSD and backstops the liquidity vault. The price those pages are describing was $0.184157 at 07:56 UTC on 31 October 2026, inside a 24-hour range of $0.180469 to $0.188477. A synthetix price prediction from that print runs to 26 June 2027, the claim date in the docs, with a bull case of $0.25, a base of $0.20 and a bear case of $0.13.
| Case | Level | Distance from $0.184157 | What the level is anchored to |
|---|---|---|---|
| Bull | $0.25 | 35.8% above | SIP-423 values SNX at $0.25 to set the conversion. That is 1.9% above the 12 June 2026 daily print and 1.6% under the 30 September daily print. |
| Base | $0.20 | 8.6% above | The 26 June 2026 daily print was $0.2009, the snapshot date in the legacy-staking docs. |
| Bear | $0.13 | 29.4% below | One repeat of the 27.5% slide from the 30 September daily print to this morning's print. The year file's low is $0.1821. |
The contrarian reading of the same morning is that the dilution a 2027 claim sounds like has already been written into the supply figure. On 17 August 2026 Synthetix posted an original supply of 344,939,867.56 SNX, a mint of 236,464,356 SNX and a new supply of 581,404,223.56 SNX. CoinGecko's total supply at 07:56 UTC on 31 October is 581,404,223.56, the same figure to the hundredth of a token, and circulating supply is 580,980,590, which is 99.93% of that total. The market cap of $106,991,573 is the print times that circulating supply. A reader waiting for the mint to appear in the valuation is waiting on a change the endpoint has already recorded.
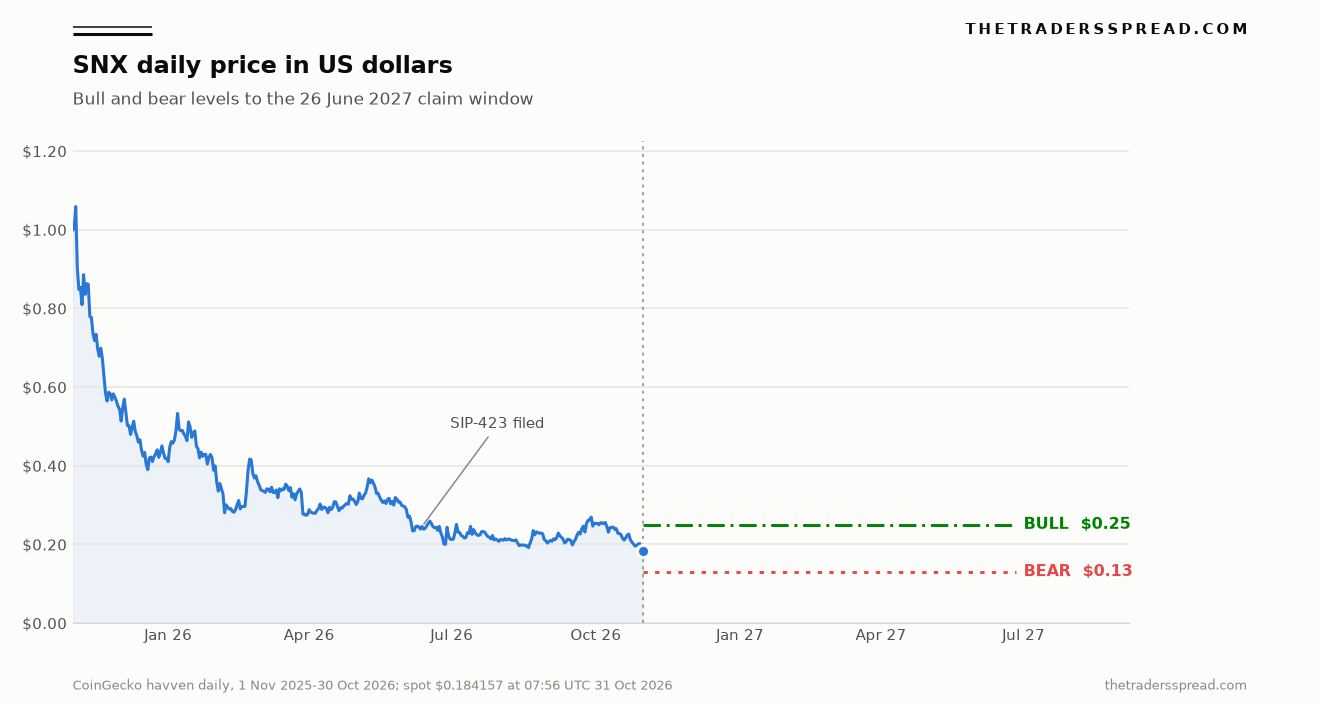
The daily file opens at $0.9983 on 1 November 2025, tops out at $1.0587 on 3 November, and is 81.6% lower by this morning. CoinGecko's one-year field is -81.8%, the 30-day field is -28.4%, the seven-day field is -9.5%, and the 24-hour field is +0.8%, at rank 264. Fully diluted value is $107,069,588, a gap of 423,633 SNX. The file then prints $0.2454 on 12 June 2026, the created date on SIP-423, $0.2009 on the 26 June snapshot, $0.2540 on 30 September, and a low of $0.1821 on 30 October, with this morning 1.1% above that low.
What the debt pool used to bill
A newer trader meeting SNX usually inherits a 2021 picture. Stakers locked SNX, minted sUSD, and owed a slice of one shared synth bill, so a swing in traders' positions moved every staker together. The collateral ratio tested whether the locked SNX still covered that slice. People still reach for that mechanism on a red week.
SIP-423, status Implemented on the SIPs page, was written to retire the arrangement. Its summary names two outcomes: convert sUSD on Ethereum and Optimism into newly minted SNX, and restructure the 420 Pool Debt Jubilee together with SNX staking. The legacy-staking docs, updated 24 June 2026, say the 420 system has been retired, the Debt Jubilee has ended, legacy sUSD has been deprecated, and the sUSD staking requirement has been removed. Stakers who were clear of debt had eligible tokens returned. The token page, updated the same day, says SNX is out of that previous staking model.
What remains on the token page is narrower. SNX is there for ecosystem participation where governance supports it, for debt resolution owed by former 420 stakers, and for settlement of the conversion. A later staking design, a fee-funded buyback, and Snaxpot ticket multipliers sit on a list of features that wait for a separate announcement. SIP-424, created 19 August 2026 and still marked vote pending, says Phase 4 staking remains unbuilt, so council voting can rest on a staking balance that the pool closure removed. Arbitrum's bull and bear cases turn on a similar split, between income a network earns and whatever the token itself receives.
A mint the supply figure already contains
The conversion arithmetic is short enough to check on the SIP. The specification values sUSD at $1 and SNX at $0.25, which is four tokens per sUSD, and the parameter table states 4 SNX per 1 sUSD entitlement. The maximum mint is 236,464,356 SNX, and the page says that figure is the Phase 2 snapshot, equal to an sUSD entitlement of 59,116,089. Multiplying 59,116,089 by four produces 236,464,356. The snapshot blocks on the page are Ethereum block 25,473,065 and Optimism block 153,868,527.
Synthetix posted that mint as a completed supply change. The original supply in the 17 August post, 344,939,867.56, plus 236,464,356, equals 581,404,223.56. The mint is 68.6% of the old supply and 40.7% of the new one. CoinGecko's total matches the new line, and circulating supply is 99.93% of it, so $0.184157 is a price on the diluted total.
2⃣/5⃣
— Synthetix ⚔️ (@synthetix) August 17, 2026
New SNX was minted at a 4:1 ratio with sUSD. The conversion includes a 1-year lock followed by 1-year vesting:
🔹Original supply: 344,939,867.56 SNX
🔹SNX minted tokens: 236,464,356 SNX
🔹New supply: 581,404,223.56 SNX
The tension is between that supply identity and the claim machinery. The docs date the snapshot at 26 June 2026, a lock through 26 June 2027, and a claim window that opens when vesting begins. Vested SNX has to be claimed within six months of becoming available, or the docs expect it to expire. SIP-423 writes the claim window as T+365 days and still tags the receipt contract as a deferred build. The tokens can sit inside a supply figure the project and CoinGecko agree on, while the contract a holder uses to take a claim is still described as ahead.
| Clock | What the opened page says | Date on that page |
|---|---|---|
| sUSD snapshot | Docs: 1 sUSD converts at 4 SNX | 26 June 2026 |
| Claim window | Docs: vesting begins and claims open. SIP: T+365 days, receipt contract tagged deferred | 26 June 2027 |
| Debt lock | Docs: former stakers with outstanding debt stay in the resolution framework, and repayment of the remainder is in USDT | 26 June 2026 to 26 June 2030 |
| Debt vest | Docs: a one-year vest after the four-year lock | From 26 June 2030 |
| Phase 4 staking | SIP-423 marks the build deferred. SIP-424, vote pending, says the replacement remains unbuilt | SIP-424 created 19 August 2026 |
Former stakers who still had debt kept their SNX inside that longer framework. SIP-424 attributes the treasury balance wallet by wallet, and a single total for that locked debt-SNX was left off the pages opened here, so the bear case uses the mint that does have a number. A separate SIP path would pay some legacy sUSD holders in USDT instead of SNX, after material revenue, with a $10 million example hurdle over two years and an example share of 25%, both marked configurable. The derivatives-volume endpoint returned a paywall, so that example stands on the page alone.
Three prices, three different anchors
The bull case is $0.25 because that is the SNX price the SIP uses in the conversion. The 12 June print of $0.2454 sits 1.9% under it, and the 30 September print of $0.2540 sits 1.6% over it. From $0.184157 the distance is 35.8%, and on 580,980,590 circulating tokens the market cap would be about $145.2 million, against $107.0 million at the print. Getting there inside this window wants a buyer the current pages only sketch: the buyback, Phase 4 staking, or a public SLP vault. While those stay on the later-work list, $0.25 is a formula price the file has visited.
The base is $0.20, 8.6% above the print, the 26 June daily print of $0.2009 rounded to the cent. That day is the snapshot date. A base here means the token spends the months until the claim window near the price it held when the snapshot was taken, after the June closure and before the slide from $0.2540. The same circulating supply puts $0.20 near $116.2 million of market cap. It is a stall, and it sits above the spot, which is why the published downside is lower.
The bear case rounds to $0.13 from a repeated slide. From $0.2540 on 30 September to $0.184157 is a decline of 27.5%, and applying that ratio again, the print times itself divided by $0.2540, lands at $0.134. At $0.13 the distance is 29.4% under the print, about $75.5 million of market cap, and past every daily print in the year, whose low is $0.1821. It is a second leg of a slide that already happened, on a token whose documented buyers are still on a future list, into the claim window dated 26 June 2027.
The lean is that bear case, with conviction kept low because the mint is already in the supply the quote uses. What remains is transferability: tokens the dashboard may already count, becoming movable when claims open, against a fee sink left for a later announcement. A daily print at $0.25, the conversion price, would end the lean, and that level is the invalidation. Distances are measured from the $0.184157 print.
Fees land in USDT
The live product is a different object from the debt pool. The docs index describes perpetual futures margined and settled in USDT on Ethereum mainnet. The products page, updated 24 March 2026, files 420 staking under legacy and marks the SLP vault as coming soon. The SLP page, updated 24 February 2026, says the vault runs internally and user deposits stay closed. CoinGecko's total-value-locked field was $871,123 at the same 07:56 UTC timestamp, a market-cap-to-TVL ratio of 122.82. DefiLlama's protocol endpoint, read the same morning, returned $871,122 on Ethereum and zero on Arbitrum and Base, the same dollar total, which would misread a live SNX debt pool.
The fees page, updated 16 June 2026, charges a regular maker 0.02% and a regular taker 0.05% of notional. Its worked example is 0.5 BTC at 100,000 USDT, or 50,000 USDT of notional: 25 USDT at the taker rate and 10 USDT at the maker rate, settled to the subaccount's USDT balance. A round trip as a taker on that example is 50 USDT. GMX token traders run into the same kind of split, where the open fee and the funding bill are different lines. Pendle's bull and bear cases are the contrast, a token whose fee path already contains a buyback. CoinGecko's 24-hour volume was $4,619,798, about 4.3% of the market cap, so the book is active while the buyback stays on the later list.
RelatedWhat Compound (COMP) Borrowers Get Wrong About the Rate
Checklist through the claim window
- A daily CoinGecko print at $0.25, the conversion price in SIP-423, ends the bear lean used here.
- A daily print at $0.13 completes the bear case. The year file's low is $0.1821, so that print would be new for the window.
- The docs date the claim window at 26 June 2027. Claims paying out are the event that date stands for, and the SIP still tags the receipt contract as a deferred build.
- A Phase 4 staking contract, or a buyback leaving the token page's list of later features, would add a buyer the present pages leave for a future announcement.
- The SLP page still describes an internal vault and closed user deposits. Deposits opening would change who holds the market-making book.
- A published total for SNX still held against unpaid 420 debt would fill the blank this reading leaves open. Until then, the mint of 236,464,356 is the supply number with a source.
FAQ
What is the Synthetix price prediction from this print?
The reference print is $0.184157 at 07:56 UTC on 31 October 2026, from CoinGecko's havven endpoint. The bull case is $0.25, the base is $0.20 and the bear case is $0.13, measured to the 26 June 2027 claim window in the docs. The lean is the bear case, and a daily print at $0.25 would end it. The mint of 236,464,356 SNX is already inside the supply figure the price is quoted on.
What did the debt pool require of an SNX staker?
Stakers locked SNX, minted sUSD, and owed a slice of one shared synth bill, so a move in traders' positions moved every bill together. The collateral ratio tested whether locked SNX still covered that slice. SIP-423 and the legacy-staking docs say the 420 pool has been closed, the Debt Jubilee has ended, and legacy sUSD has been deprecated. SNX now settles the conversion, which is a different job from minting a live shared debt.
How large was the sUSD-to-SNX mint?
SIP-423 states a maximum mint of 236,464,356 SNX, equal to an sUSD entitlement of 59,116,089 at four SNX per sUSD. Multiplying 59,116,089 by four produces 236,464,356. The 17 August 2026 post gives the original supply as 344,939,867.56 SNX and the new supply as 581,404,223.56. Adding the mint to the original supply produces that new total, and CoinGecko's total on 31 October matches it to the hundredth of a token.
When can converted SNX be claimed?
The legacy-staking docs date the snapshot at 26 June 2026 and the claim window at 26 June 2027, when vesting begins. The SIP writes that window as T+365 days and tags the receipt contract as a deferred build. Vested tokens have to be claimed within six months of becoming available, or the docs expect them to expire. Debt still owed by former stakers sits on a four-year lock from 26 June 2026 and a vest from 26 June 2030.
What would end the bear case?
A daily CoinGecko print at $0.25 would put SNX back at the conversion price in SIP-423, which is the invalidation used here. That level also sits within 2% of the 12 June and 30 September 2026 daily prints. The bear case itself is $0.13, rounded from a second 27.5% slide of the kind that ran from 30 September to 31 October. The year file bottoms at $0.1821, so $0.13 would be a new low for that window.
Does the live exchange use SNX as margin?
The docs index says Synthetix Exchange perpetuals are quoted and settled in USDT on Ethereum mainnet. The fees page charges a regular maker 0.02% and a regular taker 0.05% of notional, and those fees settle to the USDT balance. The token page lists an SNX buyback among features that wait for a separate announcement. The SLP vault is described as running internally, with user deposits still closed on the page updated 24 February 2026.
Figures are a reading of Synthetix documentation, SIP-423, SIP-424 and market data retrieved on 31 October 2026. They are not a recommendation to transact in SNX, and the live print will have moved by the time this is read.