
Having kept germanium on the minor-metals sheet since China put the metal under an export licence in August 2023, I no longer treat the domestic print and the warehouse print as two views of one price. They stopped being that when the licence arrived, and the sheet this morning still will not reconcile them. Shanghai Metals Market's China assessment for zone-refined ingot, 99.999% germanium, resistivity of at least 50 ohm-centimetres, VAT included, in warehouse in China, was 28,250 yuan a kilogram on 20 October 2026, updated at 10:40 GMT+8. That print is the benchmark for every level below. Into 31 December I have a base at 30,000 yuan, a bull case at 33,000 and a bear case at 24,000. The bull case is above the live assessment. The bear case is below it. None of those figures is an instruction.
The useful fact is narrower than "germanium is expensive". On the same SMM page the dollar average is $3,732.68 a kilogram, inside a range of $3,699.65 to $3,765.71, and the page also shows $4,217.93. The second dollar figure is the average multiplied by 1.13, to the cent. Divide 28,250 yuan by 1.13 and you get 25,000 yuan exactly, a round ex-VAT figure the page does not label as such. One Chinese assessment is being shown inside tax and outside it. Translate 28,250 yuan at the Frankfurter dollar-yuan reference for 19 October 2026, which was 6.6807, and the result is about $4,229, roughly $11 from SMM's VAT-included dollar line. That is a translation. It is not the market a Western user can actually lift. The rows that did not move, updated at 12:00 GMT+8 the same morning, were $6,425 a kilogram in US warehouses and $6,405 in Europe.
- SMM China germanium ingot, 99.999%, at least 50 ohm-cm, VAT included, in warehouse in China: 28,250 yuan/kg on 20 October 2026, updated 10:40 GMT+8 — Shanghai Metals Market, retrieved 20 October 2026
- The same page's dollar average was $3,732.68/kg, range $3,699.65 to $3,765.71, and it also showed $4,217.93, equal to that average times 1.13 — SMM, 20 October 2026
- Germanium in US warehouses: average $6,425/kg, range $6,400 to $6,450, unchanged on the day — SMM US warehouse row, 20 October 2026, 12:00 GMT+8
- Germanium in European warehouses: average $6,405/kg, range $6,380 to $6,430, also unchanged — SMM Europe row, 20 October 2026, 12:00 GMT+8
- From 13,500 yuan/kg on 31 December 2025 to 28,250 yuan/kg is a rise of 109.3% — SMM print cited 13 October, page read 20 October 2026; the percentage is our arithmetic
- US imports of germanium metal were an estimated 7,000 kg in 2025, down 67% from 21,000 kg in 2024, while dioxide imports rose 55% to 17,000 kg — USGS Mineral Commodity Summaries 2026
- China's US-specific export ban on germanium was suspended until 27 November 2026; the separate ban on dual-use items for US military users was not suspended — Fastmarkets, 11 November 2025, reporting the commerce ministry's 9 November 2025 announcement
One assessment, three numbers
Against the VAT-included dollar line, the US warehouse premium is about $2,207 a kilogram, or 52%. Against the ex-VAT dollar line it is about $2,692, or 72%. Both percentages use the 20 October SMM prints and nothing else. Europe sits $20 under the United States. That is not the premium.
The stale number most likely to be copied is the FOB row. On the SMM board opened for this note, China germanium ingot FOB was still stamped 27 April 2026, average $2,765, inside $2,740 to $2,790. Using $2,765 as spot describes April, $968 under the ex-VAT dollar average now on the product page.
That board's China 99.999% dollar row was still dated 19 October: average $3,597.33, range $3,564.32 to $3,630.33, up $2.63. The product page at 10:40 GMT+8 on 20 October had stepped to $3,732.68, a difference of $135.35. The 13 October flash still had the ingot at 27,250 yuan. I have no yuan print for 19 October, so the 1,000 yuan step is not one session.
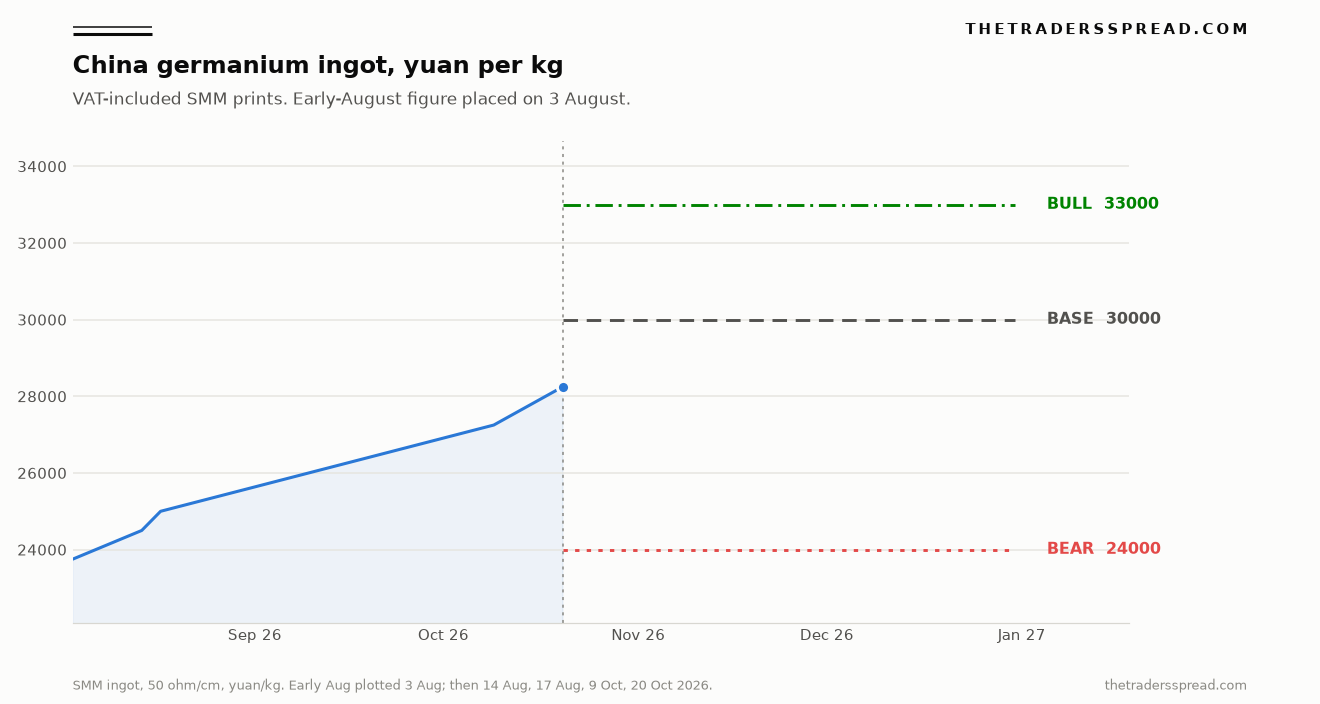
The line is the VAT-included yuan series only. SMM did not name a day for the early-August print of 23,750 yuan/kg in its 10 October weekly, so the chart places it on 3 August and says so. Named days are 24,500 on 14 August, 25,000 from 17 August, 27,250 on 9 October and 28,250 on 20 October. Paths right of the dotted line are scenarios: bull 33,000, base 30,000, bear 24,000.
| Assessment | Level | Date | Source |
|---|---|---|---|
| China ingot, VAT included | 28,250 yuan/kg | 20 Oct 2026 | SMM product page |
| Same page, dollar average | $3,732.68/kg | 20 Oct 2026 | SMM, range $3,699.65 to $3,765.71 |
| Same page, average times 1.13 | $4,217.93/kg | 20 Oct 2026 | SMM; the 13% identity is our arithmetic |
| In warehouse, United States | $6,425/kg | 20 Oct 2026 | SMM, range $6,400 to $6,450, unchanged |
| In warehouse, Europe | $6,405/kg | 20 Oct 2026 | SMM, range $6,380 to $6,430, unchanged |
| China ingot, prior year-end | 13,500 yuan/kg | 31 Dec 2025 | SMM, cited 13 Oct 2026 |
| China ingot FOB, stale row | $2,765/kg average | 27 Apr 2026 | SMM board, still showing that date |
| USGS annual average, metal | $4,100/kg | 2025 estimate | Europe, minimum 99.999%; not today's China print |
The last row is a different object. USGS put the 2025 European annual average for metal, minimum 99.999%, at $4,100 a kilogram, against $1,991 in 2024. January to October 2025 on that series ran from $3,150 to $5,380. I will not splice $5,380 onto today's $6,405. SMM's header says 99.99% minimum. Its quality note cites 99.999% at 50 ohm-centimetres.
The oxide lagged the ingot. As of 9 October, SMM had dioxide (99.999%) at 19,250 yuan/kg, up 6.9% from 18,000 over seven weeks, against 9.0% for the ingot from 25,000 to 27,250. Early August at 23,750 to 27,250 was SMM's 14.7%. Through today's 28,250 that gain is 18.9%, or 4,500 yuan, on our arithmetic.
A suspension with a date on it
The licence is still the structure. China put germanium under export licensing in August 2023 and banned exports of the metal to the United States in December 2024. On 9 November 2025 the commerce ministry suspended that US-specific ban until 27 November 2026, which Fastmarkets reported two days later. The metals stayed on the dual-use list, so a shipment still needs a licence. The December rule barring dual-use items from US military users was not addressed. The ministry notice itself did not open for this note. There is no notice number here, and no claim that a later extension does or does not exist. From 20 October, 27 November is 38 days.
Fastmarkets also noted no direct China-to-US exports of the controlled materials since the August 2023 controls. A flat $6,425 beside a China dollar average that rose $135.35 is a warehouse that did not follow. The premium narrowed by that $135 and is still measured in thousands of dollars a kilogram.
Infrared optics is the demand SMM names in the 10 October weekly and again on 13 October: thermal-imaging lenses for defence and security. SMM called the fourth quarter the peak for military deliveries, and said lens makers had already increased purchases at the end of the third quarter. A US military user still sits outside the suspension. On 10 October SMM said a higher foreign price raises the domestic ceiling while approvals restrict the flow. The warehouse rows did not lift this morning. Antimony, named in the same December 2024 measure, is the sibling on this desk.
Trail, Red Dog, and a New York waste stream
Primary germanium is a by-product. USGS says resources sit with certain zinc and lead-zinc-copper sulphide ores and with lignite, and it will not publish a country production table. China was the leading producer and exporter of metal in 2025. Processing or recycling was also known in the United States, Belgium, Canada, Germany and Russia. SMM, on 10 October, said China accounts for more than 60% of global production. That share is SMM's figure. The rank is the survey's.
In 2025 an Alaska mine produced germanium-bearing zinc concentrates, some exported to a Canadian refinery USGS does not name. A Tennessee mine has been suspended since November 2023. St. George, Utah, makes satellite-solar wafers from imported and recycled metal. Quapaw, Oklahoma, makes tetrachloride for fibre optics the same way. Metal and dioxide imports were worth an estimated $66 million. Net import reliance stayed above 50%.
Metal Tech News, drawing on Titan Mining's May announcement, describes Teck's Trail Operations in southern British Columbia as the only commercial-scale plant in North America recovering germanium from primary sources, and says Trail takes concentrates from the Red Dog mine in Alaska. I will not treat that as a sentence the survey wrote.
Rita Adiani, chief executive of Titan Mining, said: "Germanium at Empire State Mines sits in material that is currently treated as waste. By working with a credible processing partner that operates an established large-scale metallurgical facility, we have the potential to generate incremental cash flow without additional mining." The report's arithmetic is about 13,000 kilograms a year of contained germanium: roughly 600,000 short tons of scavenger tailings at 23 grams per metric ton, plus 5,400 short tons of pre-float tailings at 69 grams per ton. Contained metal is not recovered metal, and the Teck work is a test of whether those streams can become feed Trail will take.
Ian Anderson, Teck's chief commercial officer, said in that report that Teck is one of the world's largest global producers of germanium and a key supplier to the United States. Any commercial step depends on the technical and economic results.
Titan's 7 July 2026 release found germanium across six ore bodies and two tailings facilities, one Mud Pond Main sample at 85.6 ppm. The assays are not a resource and must not be multiplied by tonnage. Adiani called germanium "a district-wide characteristic of the mineral system at Empire State Mines, not a localized occurrence", and cited landed US pricing "at over $6,000/kg". This morning's warehouse average is $6,425. Thirteen thousand kilograms of contained metal is not 2026 production.
USGS estimates metal imports fell 67% in 2025, to 7,000 kilograms, because of the ban, while dioxide imports rose 55% to 17,000 kilograms, "likely owing to increased purchasing before potential tariff changes on imported goods from Canada." Over 2021–24, metal came mainly from China (41%), Belgium (27%) and Germany (25%). China's metal exports through September 2025 were 7,520 kilograms, against 18,787 a year earlier and 36,656 in 2023, to Russia, Belgium, Germany and Japan. The United States is not on that list. Recycling can be described and cannot be counted. SMM says Chinese scrap from fibre preforms and lenses is too scattered to supplement mine supply. Zinc is the host metal. The 10 October note is tight feed and sellers withholding. The unchanged US warehouse is a different story.
The kilogram infrared will not casually give up
USGS lists US end uses, in descending order, as fibre optics, infrared optics, semiconductor applications and solar cells, and radiation detectors. Fibre takes dioxide and tetrachloride. Infrared takes metal. SMM matches that infrared line and adds germanium substrates for gallium-arsenide satellite cells, citing low-Earth-orbit orders, while tetrachloride for fibre doping is described as stable. The rally on their page is an infrared rally with a satellite echo.
On 10 October, and again on 13 October, SMM said acceptance of prices above 26,000 yuan a kilogram had weakened. Today's print is 28,250, further into that zone. Their medium-term centre of 30,000 was published when the ingot was 27,250. I am not marking it up for one week's step.
Keep the two substitute stories apart. USGS says chalcogenide glass has already replaced germanium in some infrared systems, and that silicon or gallium arsenide can replace it in some electronics. SMM says some lens makers have begun evaluating zinc sulphide. One substitute exists. The other is a test. The bear case needs a line that used to take germanium and has stopped.
Tungsten is another yuan assessment, and it is not a template. Germanium's dated path is 23,750 in early August, 24,500 on 14 August in SMM's flash that day, then 25,000, 27,250 through the holiday, and 28,250 now. SMM called the climb to 27,250 a stair with no pullback, and said the next stretch was more likely sideways than another jump.
USGS shows potential disposals of 5,000 kilograms gross weight for fiscal 2025, and no potential acquisitions. A potential disposal is not a sale. In that summary's account of 2025, an August Department of Energy announcement covered $1 billion of initiatives that included germanium refining. Funding is not a kilogram in a warehouse. Titan, via Metal Tech News, put US warehouse talk as of 30 April at $5,800 to $8,600 a kilogram. Today's SMM US range is $6,400 to $6,450, unchanged. April's band was $2,800 wide. October's is $50. SMM does not say whether that is agreement or silence.
RelatedSoybean Meal Price Prediction: $410 Bull Case vs $310 Bear
30,000 is the centre, not the stretch
The base case is 30,000 yuan a kilogram by 31 December 2026, the centre SMM published on 10 October when the ingot was 27,250. I am not marking it up for the 28,250 print. From here that is a 6.2% grind, slower than the 18.9% rise since early August, in line with their warning that the pace should slow while prices above 26,000 are digested. What keeps 30,000 first is tight feed, low smelter inventories, sellers withholding, and a fourth quarter they call the peak for military infrared deliveries. The overseas price they say raises the domestic ceiling is still above $6,400 in both warehouses. I weight this path ahead of the other two.
The bull case is 33,000, about 4,750 yuan above the live print, close to the 4,500 yuan gained from 23,750 in early August. It needs the stair to resume after digestion. SMM's mechanism is a high foreign price pulling domestic offers up while licences stop the physical gap from closing. If the 27 November suspension lapses and civilian licences tighten, that mechanism gets another argument. Titan's spring band still ran to $8,600, so $6,425 is not a cap. If an extension is published and approvals speed up, 33,000 is the case I drop first. The military prohibition was never suspended.
The bear case is 24,000, just under the 14 August average of 24,500. It gives back the post-August climb, not the rise from 13,500 at the end of 2025. It needs weakened acceptance above 26,000 to become lost orders, and infrared makers doing more than evaluating zinc sulphide. The holiday left the ingot at 27,250. The next print is higher. A quiet week is not this case.
A weekly average at or below 26,000 before December would cut the bull path early. A print at 24,000 retires it. A US warehouse reading under $6,000, while China was still rising, would break the ceiling-raising story. The live print is 28,250. The centre I will defend is 30,000. Conviction is the middle of this desk's scale.
Questions the sheet actually gets
Which germanium price is this note using?
The benchmark is SMM's China ingot, 99.999% minimum, at least 50 ohm-centimetres, VAT included, in warehouse in China: 28,250 yuan a kilogram on 20 October 2026. The 33,000 yuan bull case and the 24,000 yuan bear case sit on that series only. The dollar prints on the same page, $3,732.68 and $4,217.93, are translations, one of them grossed up by 13% VAT. They are not a second forecast.
Why is US warehouse metal so far above the China price?
On 20 October the US in-warehouse average was $6,425 a kilogram and Europe was $6,405, both unchanged. Against SMM's two China dollar lines the US premium is about 52% or about 72%. Exports have needed a licence since August 2023. The US-specific ban of December 2024 is suspended only until 27 November 2026, and the military end-user prohibition was not suspended. The warehouse did not reprice when the China assessment stepped.
Does 27 November 2026 end the controls?
No. Fastmarkets, reporting the commerce ministry on 9 November 2025, said the US-specific suspension runs until 27 November 2026, that a licence is still required, and that the ban on dual-use shipments to US military users was left in place. This note did not open the ministry text, so it quotes no notice number and does not claim a later extension was or was not published.
Who refines germanium outside China?
USGS names processing or recycling in the United States, Belgium, Canada, China, Germany and Russia, and calls China the leading producer without a published share. Titan describes Teck's Trail plant as the only commercial-scale primary recovery site in North America. A study of Empire State waste streams, about 13,000 kilograms a year of contained metal on Titan's figures, is not production. The July assays are not a resource.
What breaks the 33,000 yuan case?
A weekly average at or below 26,000 yuan, where SMM said acceptance had already weakened, would cut it before price reached 24,000. So would a US warehouse print under $6,000 while the China assessment was still rising. A published extension of the November suspension, followed by metal that actually moves, would do the same. Substitution counts only if an infrared line stops taking germanium.
Is the 109% rise an SMM headline?
No. SMM's 13 October flash said the ingot averaged 27,250 yuan, up 101.85% from 13,500 on 31 December 2025. The 20 October page read 28,250. From 13,500 to 28,250 is 109.3% on our arithmetic. Use 101.85% for 13 October. Use 109.3% only for the later assessment against that same year-end print.
This is analysis, not advice. The levels are scenarios for a thin, assessed market, not a recommendation to take a position. Capital is at risk, and an unchanged warehouse row can hide a market in which very little traded.