
Qualcomm (QCOM) closed at $172.11 on 16 October 2026, $10.85 above the $161.26 strike on a warrant the company issued to an Amazon affiliate for up to 25 million shares. The gap is 6.3% of the close. The official print, 4:00 p.m. Eastern, was down $6.29, or 3.5%, from $178.40, on 12,510,984 shares. After-hours trade at $171.98 did not change it. The intraday high was $259.92 on 29 May, so Friday sits 33.8% under a price the stock traded five months ago. The intraday low was $121.99 on 7 April. Handset chip revenue in the quarter ended 28 June was $5.086 billion, down 20% from a year earlier, and still 51% of the $9.947 billion Qualcomm reported. The price is stuck between a warrant strike just underneath it and a May high a third above it, while the largest product line is shrinking.
The warrant and the handset line are one story told in two filings. On 8 September Qualcomm disclosed that 3.75 million of the 25 million warrant shares, 15%, vested on issue against what the 8-K calls initial purchase commitments. The other 21.25 million vest only as Amazon places orders and pays, up to a ceiling of $60 billion that the same filing does not describe as revenue already booked. Automotive and IoT together were $3.418 billion in the June quarter, up 28%, which annualises to about $13.7 billion. The fiscal 2029 non-handset target, repeated by Cristiano Amon on 29 July, is $40 billion. Closing that gap is the bull case. The June income statement says it has not started: total revenue fell 4%.
Key facts
- QCOM closed at $172.11 on 16 October 2026, down $6.29 or 3.53% from $178.40, with an after-hours print of $171.98 — stockanalysis.com quote, session of 16 October 2026, retrieved 18 October 2026
- The 52-week intraday high is $259.92 on 29 May 2026 and the intraday low is $121.99 on 7 April 2026 — stockanalysis.com daily history, retrieved 18 October 2026
- Fiscal third-quarter revenue was $9,947 million, GAAP diluted EPS $1.87 and non-GAAP EPS $2.21, with QCT handsets at $5,086 million — Qualcomm Exhibit 99.1, 29 July 2026
- Fourth-quarter guidance is revenue of $9.7 billion to $10.5 billion and non-GAAP diluted EPS of $2.05 to $2.25 — same Exhibit 99.1, 29 July 2026
- An Amazon affiliate received a warrant for up to 25,000,000 shares at $161.26, of which 3,750,000 vested on issue, against payments of up to $60 billion — Form 8-K, filed 8 September 2026
- Common shares outstanding were 1,050 million on 27 July 2026, and inventories were $8,379 million on 28 June against $6,526 million at the prior fiscal year-end — Form 10-Q, filed 29 July 2026
A flat quarter, and a phone line that is still half the company
The June quarter, fiscal Q3, ended on 28 June and was released on 29 July. Revenue was $9,947 million, against $10,365 million. GAAP diluted earnings were $1.87 a share, against $2.43. Non-GAAP diluted earnings were $2.21, against $2.77, on 1,069 million diluted shares. Operating income was $1,626 million, against $2,762 million: a margin of 16.3%, against 26.6%.
Cost of revenue rose while sales fell, to $4,670 million from $4,606 million. Gross margin slipped from 55.6% to 53.1%. Research and development was $2,607 million, up from $2,226 million, and selling, general and administrative expense was $976 million, up from $771 million.
"Despite a challenging memory and supply environment, our third quarter results reflect solid execution of our growth strategy, with quarterly revenues at the high end of guidance," said Cristiano Amon, President and CEO of Qualcomm Incorporated, in the 29 July release. He put a number on the strategy: non-handset revenue of $40 billion by fiscal 2029, nearly double the November 2024 target, with growth in that bucket, including data centre, expected to accelerate from 24% in fiscal 2026 to more than 60% in fiscal 2027. The same release said input costs are up across wafers, assembly, test, packaging and memory, and that higher product prices should help gross margin only as they take effect. The cost is already in the quarter. The help is not.
Inside QCT the phone decline swamped the rest. Handsets fell 20%, automotive rose 61% for a 23rd straight quarter of double-digit growth, and IoT rose 9%. QCT still fell 5%, with earnings before tax at 26% of segment revenue against 30%. QTL fell 3%, at a 69% margin against 71%.
Fourth-quarter guidance, for the period that ended on 27 September, is a band, not a rebound. Revenue of $9.7 billion to $10.5 billion midpoints at $10.1 billion, 1.5% above June, and the bottom of the band sits under the quarter just reported. QCT is guided to $8.4 billion to $9.0 billion and QTL to $1.2 billion to $1.4 billion. Non-GAAP diluted EPS of $2.05 to $2.25 midpoints at $2.15, a little under $2.21. GAAP EPS of $1.22 to $1.42 is lower because the release subtracts $0.72 for share-based compensation and $0.11 for other items. The earnings power in the guide is roughly flat.
Fifteen percent of a $60 billion ceiling
On 3 September Qualcomm issued a warrant to Amazon.com NV Investment Holdings LLC, an affiliate of Amazon Data Services. The 8-K filed on 8 September was signed by Akash Palkhiwala, executive vice president, chief financial officer and chief operating officer. The warrant covers up to 25,000,000 shares at $161.26, expires on 3 September 2036, and carries no vote while unexercised. Shares vest on commercial arrangements, binding orders and actual purchases of server chips, technology, systems and manufacturing services, up to $60 billion of payments. Of that grant, 3,750,000 shares vested on issuance, against initial purchase commitments.
Fifteen percent of the equity kicker is already live. Eighty-five percent is not. Four times the June quarter is about $39.8 billion, so a $60 billion ceiling is about a year and a half of current revenue, spread across a warrant that does not expire until 2036. The filing never says the $60 billion will be spent. It says vesting stops there. Our Amazon forecast is the other side of the contract: Amazon's orders decide whether the unvested shares exist.
A second issuance is easy to lose beside the warrant. A 31 July 8-K said Qualcomm had issued 17,826,566 shares for Modular Inc. The 29 July release said that acquisition was complete. At Friday's close those shares are worth about $3.07 billion. They are already stock. The warrant is mostly still an option on purchases.
Investor Day on 24 June is where the $40 billion figure was raised and the mix was spelled out. The release that day set fiscal 2029 targets of more than $15 billion of data-centre revenue, $10 billion of automotive revenue and more than $14 billion of IoT, with handsets falling to about one-third of QCT. Non-GAAP earnings were targeted above $18 a share. If non-handset QCT revenue is $40 billion and handsets are one-third of QCT, handsets that year would be about $20 billion. That arithmetic is ours, not a guide Qualcomm published. It describes a phone business that stops being most of QCT.
"We are defining Qualcomm's next chapter as we accelerate our edge diversification strategy, introduce a comprehensive roadmap for next-generation AI data centers, and evolve into a platform company," Amon said on 24 June. He was President and CEO then, as in July. Four times the June automotive quarter is $6.35 billion. The fiscal 2029 automotive target is $10 billion. Another year at the 61% rate on that run-rate would clear $10 billion. The target assumes that 61% does not last.
A year the tape has already traded
From the close on 16 October 2025, $164.08, Qualcomm is up 4.9%. From the 31 December 2025 close of $171.05 it is up 0.6%. The path is not a drift. The closing high was $251.02 on 29 May, the same session as the $259.92 intraday high, and the low close after that peak was $147.61 on 31 July. September spiked to $201.97 on the 25th, after a 5.8% drop on 18 September to $177.72. The 30 September close was $184.04. Friday is 6.5% under that close and 14.8% under 25 September.
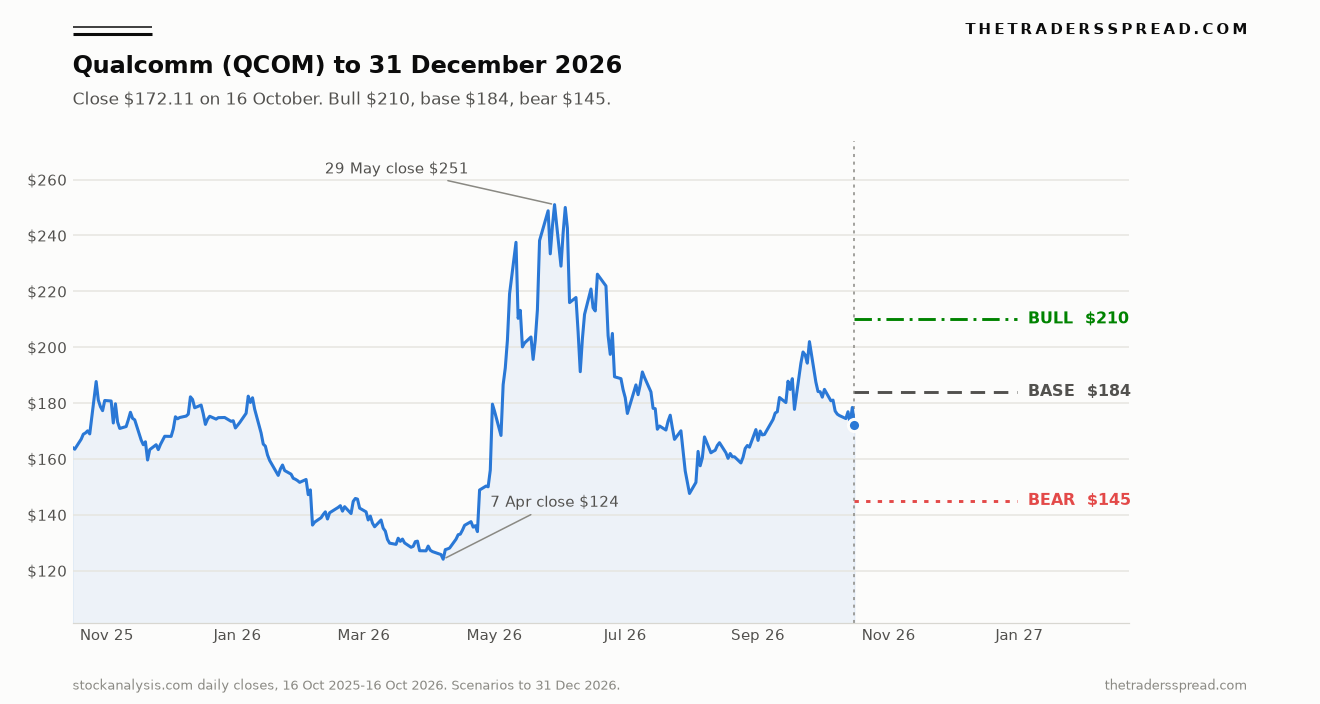
The lines are scenarios to 31 December 2026, not a path the stock must follow. Bull at $210 is 22.0% above Friday and still 19% under the May intraday high. Base at $184 is the 30 September close, rounded, 6.9% above Friday. Bear at $145 is 15.8% under Friday and just under the 31 July close of $147.61. All three sit inside a range already traded in 2026.
| QCT and QTL | Q3 FY2026 | Q3 FY2025 | Change |
|---|---|---|---|
| Handsets | $5,086 million | $6,328 million | −20% |
| Automotive | $1,588 million | $984 million | +61% |
| IoT | $1,830 million | $1,681 million | +9% |
| QCT total | $8,504 million | $8,993 million | −5% |
| QTL | $1,278 million | $1,318 million | −3% |
Segment revenue from Exhibit 99.1, 29 July 2026. Handsets were 60% of QCT in the quarter and 51% of company revenue.
| Case to 31 Dec 2026 | Level | Versus $172.11 | Weight |
|---|---|---|---|
| Bull | $210 | +22.0% | 25% |
| Base | $184 | +6.9% | 45% |
| Bear | $145 | −15.8% | 30% |
Weights are our own. Applied to the three levels they give about $179, 4% above the 16 October close. Repeat the fourth-quarter non-GAAP midpoint of $2.15 for four quarters and the figure is $8.60. Friday's close is 20.0 times that. $210 is 24.4 times it, $184 is 21.4 times it, and $145 is 16.9 times it. The fiscal 2029 non-GAAP target above $18 is a different year: 9.6 times a target at Friday's close, not 9.6 times a result.
The tape around the name has not been quiet. Applied Materials fell 19.3% in the week to 16 October. Broadcom's forecast is the other custom-silicon story, with a different customer list. The comparison that belongs here is Qualcomm's own segments.
A verdict, a stockpile, and a share count with a date on it
The July 10-Q describes a Delaware case Qualcomm filed against Arm, alleging Arm breached the architectural licence by failing to deliver what the contract requires. Later amendments added claims that Arm had sought to terminate the licence. The 10-Q says trial was scheduled to begin on 5 October 2026. On 13 October the company said a jury had found that Arm breached that licence, failed to honour its commitments, and acted to disrupt Qualcomm's businesses. The statement gives no damages figure. An earlier Nuvia case had already gone Qualcomm's way: a December 2024 jury found no breach by Qualcomm and found the relevant CPU designs licensed, and judgment followed on 30 September 2025. Arm appealed the next day.
The price did not treat 13 October as a re-rating. QCOM closed that day at $176.86, up 1.4% from $174.43. By Friday it was $172.11, 2.7% under the verdict-day close and 1.3% under the session before the statement. Our Arm forecast is the other name on the licence. The 10-Q says Arm had asked a court, in the earlier case, to have the disputed technology destroyed. It does not replace a dollar of handset revenue. Qualcomm had recorded no accrual at 28 June for contingent losses on these matters, because a loss was not considered probable and could not be estimated.
Inventories argue with the diversification slide. They were $8,379 million on 28 June, against $6,526 million on 28 September 2025, up 28.4% while nine-month revenue fell from $33,013 million to $32,798 million and nine-month handsets fell from $20,831 million to $18,934 million. Cash was $4,533 million and marketable securities were $3,771 million. Debt due within a year was $2,489 million, against none at the prior year-end, and long-term debt was $12,781 million. Net of cash and securities, debt was $6,966 million. Nothing on that balance sheet says a $60 billion customer has already paid.
The share count needs a date. The 10-Q cover says 1,050 million shares were outstanding on 27 July. At $172.11 that is $180.7 billion. The 17.8 million Modular shares disclosed on 31 July came after that date, so they are not in the $180.7 billion. Adding them at Friday's price puts the equity near $183.8 billion. In the June quarter the company returned $2.3 billion: $973 million of dividends, $0.92 a share, and $1.4 billion repurchasing 8 million shares, with $20.6 billion of authorisation left. Annualising that dividend against Friday's close is a 2.1% cash yield, the rate paid, not a pledge about the next declaration. Fully issued, the warrant would be 2.4% of the 27 July count. The vested slice is 0.4%. Dilution is not the bear case.
Qualcomm has not posted the next report date. The investor-events page, checked on 18 October 2026, lists no fourth-quarter release. The company FAQ puts that quarter at 29 June through 27 September 2026, and last year's fourth-quarter 8-K and 10-K were filed on 5 November 2025. An early-November print would sit in this window. The 24 June release lists customers vertically integrating as a risk, which is the question in our Apple forecast. These filings do not split the $5.086 billion by customer.
The call
The horizon is 31 December 2026. It can contain the fourth-quarter report if Qualcomm repeats last year's early-November timing, and it is too brief for fiscal 2029 targets to count as facts. The weighted level of the three cases is about $179, a small gap over $172.11. The stance is neutral. The central case is the base, not the bull.
RelatedTSMC (TSM) Falls 3.4% Ahead of the Q3 Earnings Print
Base case, $184, probability 45%. Fourth-quarter revenue lands inside $9.7 billion to $10.5 billion, and non-GAAP earnings inside $2.05 to $2.25. Handsets stop deteriorating at June's 20% rate. Automotive does not have to repeat 61%. The stock retraces the 30 September close of $184.04. That needs no new multiple. It needs no new shock.
Bull case, $210, probability 25%. Revenue prints near $10.5 billion. Automotive keeps a double-digit streak, now at 23 quarters, without repeating 61%. A filing before year-end shows warrant vesting past the initial 3.75 million shares, so the ceiling has started to become orders. $210 is 4% above the 25 September close of $201.97 and still under the May high. The case fails if, on 31 December, the data-centre evidence is still only the 8 September 8-K.
Bear case, $145, probability 30%. Revenue comes in at or under $9.7 billion, or handsets fall another leg like June's. The price closes under the $161.26 strike and drifts toward the summer trough. $145 is just under the 31 July close of $147.61. It does not require the April low of $121.99. A close under the strike pulls this case forward. So would inventories still rising from $8,379 million.
What would change the weights: vesting beyond the initial 3.75 million shares, tied to orders rather than to the ceiling, would move ten points from the base to the bull. A revenue print under $9.7 billion, or a close under $161.26, would make the bear case the central one. Handsets down another 20% in that release would retire $184 as a waiting room. These are the prices at which the June filings and the October tape either agree or do not. They are not instructions.
FAQ
What is the Qualcomm stock forecast to the end of 2026?
Scenarios to 31 December 2026 are $210 bull, $184 base and $145 bear, against the 16 October close of $172.11. Weights of 25%, 45% and 30% blend to about $179, roughly 4% above the close. The bull case is 22% above Friday and still under the 29 May intraday high of $259.92. The bear case is 16% under the close.
Why does the bear case sit under the Amazon warrant strike?
The warrant strike is $161.26, and Friday's close is $10.85 above it. The bear case of $145 is a move through that strike toward the 31 July close of $147.61 and slightly past it. The strike is a price in an 8-K, not a floor Qualcomm promised. A close under it would mean the shares changed hands below the option on the data-centre contract.
When does Qualcomm report next?
As of 18 October 2026 the investor-events page had no fourth-quarter date. The FAQ says the quarter ran from 29 June to 27 September 2026. The prior year's 8-K and 10-K were filed on 5 November 2025. Until Qualcomm names a day, early November is a precedent, not a calendar entry. Guidance is already public: revenue of $9.7 billion to $10.5 billion.
How much of Qualcomm is still handsets?
Handset chip revenue in the quarter ended 28 June was $5,086 million, 51% of company revenue of $9,947 million and 60% of QCT revenue of $8,504 million. Automotive was $1,588 million and IoT $1,830 million. Over nine months, handsets were $18,934 million of $32,798 million. The other lines are growing. They are not yet the majority of the income statement.
What did the October jury finding change for the shares?
On 13 October Qualcomm said a jury found that Arm had breached their architectural licence. The statement gave no damages number. The shares closed that day at $176.86 and by 16 October were at $172.11, below the session before the statement. A separate Nuvia case had already been decided for Qualcomm in 2025, and Arm appealed. The finding matters for the CPU programme. It did not reset the price.
Disclaimer
This is analysis, not advice. The scenario levels, weights and the $8.60 illustration are ours, and they can be wrong. Qualcomm's targets for fiscal 2029 are the company's targets, not results. Share prices fall as well as rise. Capital is at risk. Figures come from the filings, the company pages and the price source dated in the text. Readers should check the primary documents and their own circumstances before making any decision.