
| Series | Specification | Basis and time | |
|---|---|---|---|
| Neodymium metal, VAT excluded | 99.0% to 99.9%, GB/T 9967-2010, brands Funeng, Chenguang, Keli | $122.05/kg ($122,045.07/t), range $121.71 to $122.38/kg, change 0 | Delivered China. SMM, 10 November 2026, 11:00 GMT+8 |
| Same metal, VAT included | Same card | $137.91/kg ($137,910.93/t), change 0 | Same update. Equals the VAT-excluded tonne price times 1.13 |
| Same metal, yuan | Original assessment | 922,500 yuan/t, change 0 | Same SMM update |
| Pr-Nd oxide, VAT excluded | Nd2O3 75% of TREO, Pr6O11 25%, GB/T 31965-2015 | $94.13/kg. Yuan 711,500, up 4,500 (0.64%) | Delivered China. SMM, same morning |
| Neodymium metal, FOB | Export metal | $145 to $157/kg, down $3/kg | SMM ex-China review, 6 November 2026 |
| Neodymium oxide average | 99.5% min, FOB, annual | $73/kg, 2025 estimate | USGS Mineral Commodity Summaries, February 2026, via Argus |
The neodymium price most models paste in is whichever dollar figure a screen showed last, and on 10 November 2026 those screens disagreed by tens of dollars a kilogram. I am calling Shanghai Metals Market neodymium metal, VAT excluded, delivered to works in China, at $122.05 a kilogram.
The card I opened showed $122,045.07 a tonne, a range of $121,714.33 to $122,375.82, and a zero change, with the yuan assessment steady at 922,500. Specification is 99.0% to 99.9% metal under GB/T 9967-2010, brands Funeng, Chenguang and Keli. Daily history asks for a login, so the chart keeps this single point and parks the oxide averages in their own table.
The VAT-included print was $137,910.93 a tonne. Multiplying $122,045.07 by 1.13 lands on that figure, so $137.91 a kilogram is the tax-inclusive conversion of the same assessment, and I leave older yuan quotes in yuan. Pr-Nd oxide, same house and same 11:00 GMT+8, was $94,130.16 a tonne VAT-excluded, about $94.13 a kilogram, with yuan at 711,500, up 4,500 or 0.64%, on a mixed-oxide spec under GB/T 31965-2015.
From the USGS 2025 oxide average of $73, through the $94 oxide, the $122 metal and the $145 to $157 FOB range, swapping the label changes the story by more than my whole base case. That base, $131, is only $8.95 or 7.3% above the metal I chose, smaller than the metal-to-oxide gap on the same morning.
The print I am using
Asian Metal's board asked for a sign-in, so I marked the SMM card that opened. Bull is $148, base is $131, and bear is $102, against a $122.05 spot, so the bull sits above, the bear below, and the base between. A squeeze would have wanted a higher yuan print, and the metal card was flat at 922,500.
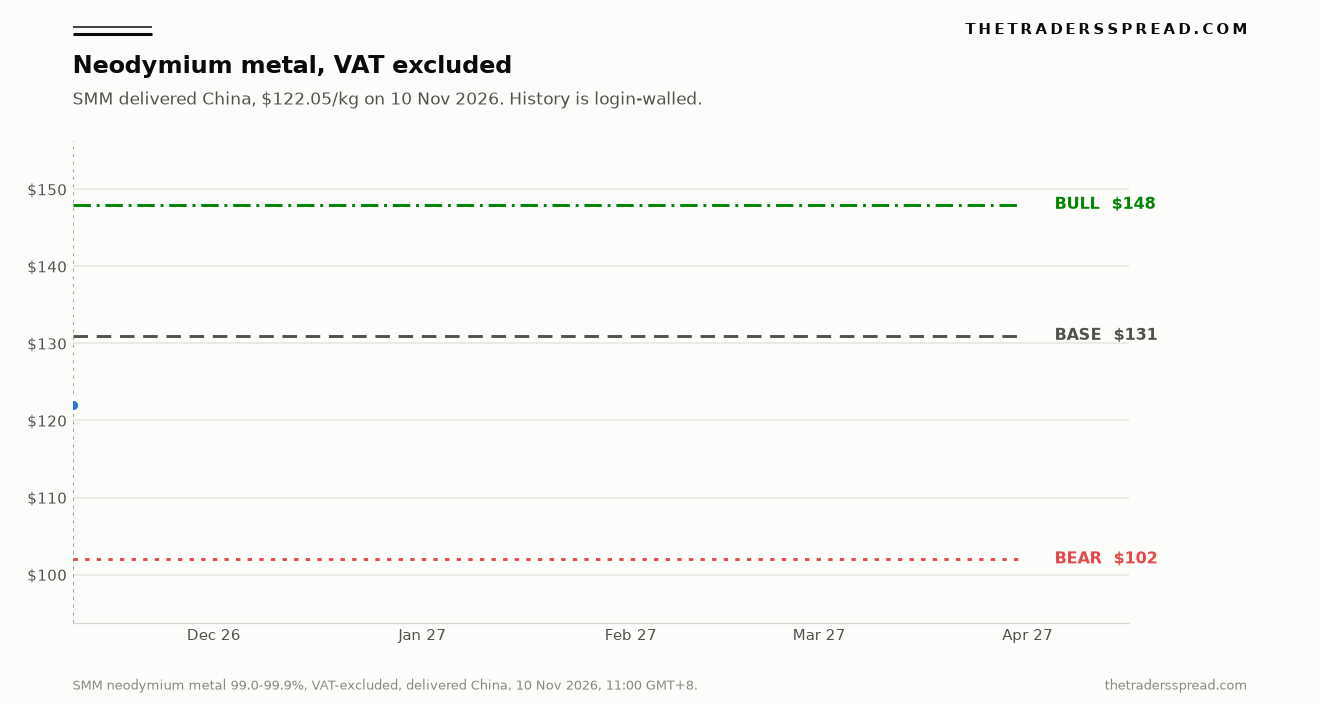
The levels run to 31 March 2027 because that date falls after 10 January 2027, when the current suspension of China's October 2025 rare-earth package is due to expire. A chart that stopped in December would hide the policy date inside the horizon. The dot at the left is the whole history I can defend for this series.
Key facts
- VAT-excluded neodymium metal, 99.0% to 99.9%, delivered China, averaged $122.05 a kilogram on 10 November 2026, yuan unchanged at 922,500 a tonne. Shanghai Metals Market, 10 November 2026.
- The VAT-included print on the same card was $137.91 a kilogram, the VAT-excluded tonne price times 1.13. Shanghai Metals Market, 10 November 2026.
- Pr-Nd oxide was $94.13 a kilogram VAT-excluded the same morning, yuan 711,500, up 0.64%. Shanghai Metals Market, 10 November 2026.
- FOB China neodymium metal was $145 to $157 a kilogram, down $3. Shanghai Metals Market ex-China review, 6 November 2026.
- The 2025 average for neodymium oxide, 99.5% minimum, FOB, was an estimated $73 a kilogram, after $56 in 2024 and $134 in 2022. USGS Mineral Commodity Summaries, February 2026.
- Surveyed NdFeB plants ran at 74% in October, down 2.1 points on the month and up 15% on the year, with November projected at 75.78% and output of 32,394 tonnes. Shanghai Metals Market, 30 October 2026.
- China's rare-earth exports were 4,386 tonnes in October, up 2.7% on the month, and 48,097 tonnes for January to October, down 8.7% on the year, while value rose 46.4% to about $584 million. RAWMATERIALS.net, citing Customs, 10 November 2026.
Five years of the oxide average
The oxide history stays in its own table so the $73 figure stays an annual average and never gets drawn as if it were Tuesday's metal.
| Year | Neodymium oxide, 99.5% min, $/kg | NdPr oxide, 99% min, $/kg |
|---|---|---|
| 2021 | 98 | 92 |
| 2022 | 134 | 124 |
| 2023 | 78 | 75 |
| 2024 | 56 | 55 |
| 2025e | 73 | 69 |
Those free-on-board annual averages come from Argus via the US Geological Survey's February 2026 Mineral Commodity Summaries. Oxide fell from $134 in 2022 to $56 in 2024, and the 2025 estimate recovered to $73, with NdPr oxide tracing $124, $75, $55 and then $69. The complex can travel tens of dollars inside a year on a fixed product, and that oxide path is a weak map for delivered Chinese metal in March.
Estimated 2025 world mine output was 390,000 metric tons of rare-earth oxide, China 270,000 and the United States 51,000. US compound imports were estimated at 21,000 metric tons against 8,120 in 2024, and net import reliance for compounds and metals at 67% against 53%. Leading global use was magnets. Fiscal 2025 potential acquisitions included 300 tons of NdPr oxide and 450 tons of NdFeB block.
Magnet plants take a small step
SMM's 30 October note is the demand evidence I will use. Industry NdFeB operating rates in October were 74%, down 2.1 percentage points on the month and up 15% on the year, after a peak season that missed orders. SMM reads the yearly gain as a cycle still intact and the monthly dip as soft end demand, including new-energy vehicles, with holidays and maintenance on top. November is projected at 75.78%, with output up about 2.3% from 31,670 tonnes to 32,394 tonnes, a moderate fourth quarter rather than a V-shaped snapback.
Those 724 extra tonnes are the demand increment I can document before the next survey. A base case about $9 above a flat yuan print is about the size of move that step can carry if metal follows magnets with a lag. Keeping a domestic assessment apart from a seaborne number is the same discipline as the manganese call on portside ore.
January sits inside the horizon
On 9 November, MOFCOM and Customs Announcement No. 58 of 2026 kept the October 2025 package suspended from 11 November 2026 through 10 January 2027, covering equipment, medium and heavy rare-earth items, overseas-related items and related technologies. RAWMATERIALS.net lists holmium, erbium, thulium, europium and ytterbium, plus some processing technology, lithium batteries, graphite materials and goods made abroad with Chinese rare earths. The April 2025 controls stay in force. USGS names that set as samarium, gadolinium, terbium, dysprosium, lutetium, scandium and yttrium.
Neodymium metal sits outside both lists, while dysprosium and terbium sit inside the April set that was left in force. I treat 10 January as a date for the magnet bill and only indirectly for the ingot. If the suspension expires on schedule, heavier oxides tighten and this light metal stays off the control list. A higher heavy-rare-earth cost can lift NdFeB offers, or it can push mills toward grades that use less dysprosium. The bull case is the pass-through, and the base case is a partial one.
Customs figures reported by RAWMATERIALS.net on 10 November show October shipments of all 17 rare earths at 4,386 tonnes, up 2.7% on the month and about 1% on the year. January through October was 48,097 tonnes, down 8.7%, while export value rose 46.4% to about $584 million. That mix, less volume and more value, fits higher-priced products better than a closed border, and 4,386 tonnes is a group total rather than a neodymium-metal balance. The same split between a rule and a product is why gallium moved with the export rules, and why flake graphite and synthetic anode material stopped sharing one price. Graphite materials sit in the package suspended until January.
Tonnes arriving from outside China
Separated NdPr already on the books can hit this horizon. A refinery still choosing a site lands later. MP Materials reported the quarter ended 30 September on 5 November: NdPr production 1,018 metric tons, up 41% from 721, and sales 1,020 metric tons, up 94% from 525. Revenue was $147.655 million, up 176%, with $8.109 million of price-protection income in the quarter. NdPr oxide and metal revenue was $100.961 million, magnetics revenue $18.623 million, adjusted EBITDA $41.138 million, and the net loss $20.710 million.
James Litinsky, Founder, Chairman and Chief Executive Officer of MP Materials, said in that release: "MP Materials delivered a strong quarter of growth across production, sales, and earnings." General Motors magnet qualification is complete, with saleable deliveries beginning in the fourth quarter. The oxide and metal MP sells competes with Chinese NdPr on an assessment separate from the SMM ingot, so I count the volume ramp as a weight on the bull case for the domestic card. The company posted those headline figures the same day.
$MP Q3 2026 highlights:
— MP Materials (@MPMaterials) November 5, 2026
• NdPr production: 1,018 MT (+41% YoY)
• NdPr sales: 1,020 MT (+94% YoY)
• $155.8M of consolidated revenue and PPA income, including $147.7M of revenue (+176% YoY) and $8.1M of PPA Income
• Materials Segment generated $133.5M revenue, $8.1M PPA…
SMM's 6 November ex-China review puts Lynas down for about a month in Malaysia and about two weeks at Kalgoorlie, with December-quarter production under pressure. The same note had FOB neodymium metal at $145 to $157 a kilogram, down $3, while dysprosium and terbium oxides in Rotterdam were higher, so light and heavy moved apart. DTEC's planned Malaysian refineries, about $600 million and 10,000 metric tons a year, were still choosing a site, and Solvay's Viridis offtake of about 2,450 metric tons a year starts shipments in 2028. Lynas's weeks of maintenance fit a March clock, while those 2028 shipments sit past it.
Where $148, $131 and $102 come from
| Case | Level | Versus $122.05 | What has to hold |
|---|---|---|---|
| Bull | $148/kg | +$25.95, about 21.3% | November magnet output lands near 32,394 tonnes, the 10 January expiry tightens heavies, and domestic metal follows toward the low end of the FOB range |
| Base | $131/kg | +$8.95, about 7.3% | The yuan assessment stays firm, the magnet step-up is about 2%, and MP's NdPr sales are absorbed without a break in the delivered print |
| Bear | $102/kg | minus $20.05, about 16.4% | The magnet rate gives back October's 74% and keeps falling, while outside NdPr shows up in the domestic metal card |
The $148 bull case is a level on this delivered metal series, not a forecast of the FOB range that already printed $145 to $157 a kilogram on 6 November. Reaching $148 would put VAT-excluded domestic metal near the bottom of that export range, which fits if January's expiry lifts the magnet bill. A print far through $157, with oxide still near $94, would be a different market from the card, so the bull stops at $148.
Related19% Murban Crude Slide Began Before the Midterm Vote
The base case at $131 is the path I mark, 7.3% above a yuan print that was unchanged on 10 November, against magnet output projected 2.3% higher. With one visible point, I would rather underwrite a small lift than a regime change. Conviction is a 2 on a five-point scale, because the MP ramp and the Lynas outage pull in opposite directions and the daily metal history sits behind the login.
The bear case at $102 is 16.4% under the spot I opened. It needs the magnet survey to fall back through October's 74% and outside NdPr to land in the domestic assessment. A print under $102 would break the metal series I am using, and that is the invalidation for the $131 path.
I would move the base case if the November magnet rate falls back through 74%, if Beijing extends the suspended October 2025 package past the end of March, or if this VAT-excluded print breaks under $102 a kilogram. Any one of those retires the $131 path. A rate that holds near 76%, with the yuan assessment still steady, leaves the base case in place. Entry is $122.05, the base target is $131, and the horizon is 31 March 2027.
FAQ
What neodymium price is this call using?
The call uses Shanghai Metals Market neodymium metal, 99.0% to 99.9%, VAT excluded, delivered to works in China. On 10 November 2026 at 11:00 GMT+8 that average was $122,045.07 a tonne, or $122.05 a kilogram, and the yuan assessment was unchanged at 922,500. The VAT-included dollar print, the Pr-Nd oxide print and the USGS annual oxide average are different products and stay out of the title.
Why is the bull case $148 a kilogram?
A move from $122.05 to $148 is about 21%, large enough to matter and still inside the low end of the FOB metal range SMM published on 6 November at $145 to $157. It needs the November magnet step-up to stick and the 10 January control expiry to lift the heavy-rare-earth part of the magnet bill. I stop there because a domestic print far above the export offer would be a different market from the one on the card.
What would make $102 the right map?
The bear case needs surveyed NdFeB operating rates to give back October's 74% and keep sliding, while separated NdPr from producers outside China shows up in the Chinese delivered assessment. MP's third quarter already recorded 1,020 metric tons of NdPr sales. If that metal, or the tonnes behind it, pressures the SMM card, $102 is the level where I drop the $131 base. Above $102, the base path can still survive a noisy week.
Does the April 2025 control list include neodymium?
Neodymium sits outside the April 2025 list and outside the October 2025 list that is suspended until 10 January 2027. The April list, as the USGS records it, is samarium, gadolinium, terbium, dysprosium, lutetium, scandium and yttrium, and those controls stayed in force. Dysprosium and terbium still sit in high-temperature magnets next to neodymium, so the January date can change the magnet bill without changing the legal status of the ingot itself.
How should I read the USGS figure of $73?
The $73 is the Survey's 2025 estimate for neodymium oxide, 99.5% minimum, as an annual FOB average, with Argus as the source in the February 2026 Mineral Commodity Summaries. The 2024 average on that line was $56 and the 2022 average was $134. It is a year of oxide, useful as a long reference beside the metal card, and a weak substitute for the $122.05 delivered-metal print from 10 November.
This is desk analysis for information, and it is not a recommendation to trade neodymium metal, a magnet, or any security tied to them. Prices can move against you, and capital is at risk.