
Distributor A accounted for 44% of Marvell net revenue in the quarter ended 1 August 2026, and the quarterly report still prints that buyer as a letter. The same Form 10-Q, filed on 28 August 2026, puts data-center end-market sales at $2,171.5 million, 79% of the $2,739.3 million total. Those two percentages come from different tables, one a customer-concentration line and the other an end-market line, and a custom-ASIC dollar column appears in neither.
Direct customers were $1,364.9 million, half the quarter, and distributors were $1,374.4 million, the other half. A year earlier, direct customers were 59% and distributors were 41%, while data center was 74% rather than 79%. Anyone who reads 79% as a headcount of hyperscalers buying custom XPUs is mixing a billing channel with an end market. Note 3 keeps those cuts in separate tables, and the MD&A lists electro-optics, custom, storage and switching as joint drivers of the increase.
Updated 10 November 2026, from the Form 10-Q for the quarter ended 1 August 2026 and the filings around it.
Key figures from the filings
- Net revenue was $2,739.3 million for the quarter ended 1 August 2026, against $2,006.1 million a year earlier (Marvell earnings release, 27 August 2026).
- Data center was $2,171.5 million, 79% of that quarter, and communications and other was $567.8 million, 21% (Form 10-Q Note 3, 1 August 2026).
- Distributor A was 44% of quarterly net revenue and direct Customer A was 16%, both left as letters (Form 10-Q, filed 28 August 2026).
- China-destination shipments were $1,161.5 million, 42%, against United States shipments of $190.8 million, 7% (Form 10-Q Note 3, 1 August 2026).
- Google LLC received a warrant for up to 58,970,907 shares at $206.58, with tranches tied to $500 million of custom-product purchases (Form 8-K, filed 19 August 2026).
- GAAP gross margin was 53.1%, and third-quarter revenue guidance was $3.150 billion plus or minus 5% (earnings release, 27 August 2026).
- Common shares outstanding were 876.9 million as of 21 August 2026, and cash was $3,932.8 million at 1 August 2026 (Form 10-Q).
Is 79% the custom book?
Matt Murphy, Chairman and CEO of Marvell Technology, separated the pieces in the earnings release on 27 August 2026. He said the company was "seeing broad-based strength across our Data Center portfolio, including strong demand in Connectivity and a significant acceleration in our Custom business beginning in the second half of fiscal 2027." The 10-Q MD&A gives the same four drivers, electro-optics, custom, storage and switching, and on the call that afternoon he said interconnect "continues to lead the way, while our custom business is expected to ramp significantly in the second half." Booking the whole 46% year-on-year data-center increase to custom runs ahead of that order.
The fiscal 2026 Form 10-K, filed 11 March 2026, defines custom work as semiconductor solutions tailored to individual customer specifications, built on Marvell intellectual property such as SerDes, silicon photonics, chiplets and custom high-bandwidth memory. Interconnects, ethernet solutions, fibre channel adapters, processors and storage controllers sit beside that family as separate offerings.
| End market | Quarter ended 1 Aug 2026 | Share | Quarter ended 2 Aug 2025 | Share | Year ended 31 Jan 2026 | Share |
|---|---|---|---|---|---|---|
| Data center | $2,171.5 million | 79% | $1,490.5 million | 74% | $6,100.3 million | 74% |
| Communications and other | $567.8 million | 21% | $515.6 million | 26% | $2,094.3 million | 26% |
| Total net revenue | $2,739.3 million | 100% | $2,006.1 million | 100% | $8,194.6 million | 100% |
Sources: Form 10-Q Note 3 for the quarters, and the fiscal 2026 Form 10-K for the year ended 31 January 2026. In the year ended 3 February 2024 the same 10-K shows data center at $2,216.7 million, 40% of revenue, and communications and other at $3,291.0 million, 60%. Reading the total and then the lines under it is the habit a line-by-line reading of Lam Research earnings asks of an equipment report.
The name on the invoice is often a distributor
Note 3 also splits the quarter by customer type. Distributor revenue grew from $814.7 million a year earlier to $1,374.4 million, while direct revenue grew from $1,191.4 million to $1,364.9 million and its share fell from 59% to 50%. The six-month columns in the table show the same even split, against a year-earlier mix of 58% direct and 42% distributors.
| Customer cut | Quarter ended 1 Aug 2026 | Quarter ended 2 Aug 2025 | Six months ended 1 Aug 2026 |
|---|---|---|---|
| Direct customers | $1,364.9 million, 50% | $1,191.4 million, 59% | $2,553.8 million, about 50% |
| Distributors | $1,374.4 million, 50% | $814.7 million, 41% | $2,603.3 million, about 50% |
| Customer A, direct | 16% | 16% | 16% |
| Distributor A | 44% | 34% | 45% |
Sources: Form 10-Q Note 3 and the sales and customer composition section. For the year ended 31 January 2026 the 10-K shows Customer A at 14% and Distributor A at 37%, and the ten largest customers, distributors included, at 82% of net revenue. At 1 August 2026, four customers represented 72% of gross accounts receivable, against five customers and 73% a year earlier. During the quarter Marvell sold $111.1 million of trade receivables under a factoring arrangement, and $412.0 million over the six months, with $111.1 million still serviced at the quarter end.
Google LLC is named in the Form 8-K filed on 19 August 2026. NVIDIA Corporation is named in the 10-Q because, on 31 March 2026, Marvell issued Series A convertible preferred stock to NVIDIA for $2.0 billion. Customer A remains a letter in the revenue table, so assigning either legal name to it would be a guess the filing refuses to support. On the 27 August call Murphy called that counterparty "a key hyperscaler." Six Walmart myths on sales, traffic and margin make the same point for a retailer.
A shipment address is a factory
China was the destination for $1,161.5 million of shipments in the quarter, 42%, up from $583.4 million and 29% a year earlier. The United States was $190.8 million, 7%, down from $310.8 million and 15%. Taiwan was $456.8 million, or 17% of the quarter, and Singapore was $337.3 million, or 12%. The United States share of shipments fell in the same quarter the data-center share of end markets rose to 79%.
Note 3 says these destinations of shipment "are not necessarily indicative of the geographic location of the Company's end customers," and that "a substantial majority of the shipments made to China relate to sales to non-China based customers that have factories or contract manufacturing operations located within China." The 42% figure is a factory address, so a US hyperscaler's custom order can still be counted in China when the box leaves for a contract manufacturer in Asia.
What "custom" means in Marvell's own product language
The 10-K spends the custom paragraph on Marvell's platform, rather than on a foundry service. The company says it has executed multiple 5-nanometre designs, is progressing through 3-nanometre designs, and is developing a 2-nanometre platform. The applications run past the data center into compute, networking, carrier, storage, aerospace and defense, so a custom chip can sit in the communications column as well as in the data-center column. Using the 79% as a ceiling on custom, or as a floor, over-reads the label.
The neighbouring interconnect family covers PAM and coherent DSPs, laser drivers, silicon photonics, co-packaged optics, linear pluggable optics and PCIe retimers. Several of those words reappear in the quarterly MD&A as electro-optics, inside the 79% and in a different family from the custom ASIC paragraph. On 5 November 2026 the official account posted about Ara, an optical DSP in that connectivity list.
Ara T can cut optical module power consumption by more than 35%.
— Marvell Technology (@MarvellTech) November 5, 2026
It’s part of the Marvell 1.6T optical DSP platform portfolio, which just earned a 2026 LEAP (Leadership in Engineering Achievement) Award from @DesignWorld in the connectivity category.
The portfolio includes Ara… pic.twitter.com/r3qVU2eQQn
The 10-Q risk summary flags a limited set of suppliers and the chance Marvell cannot obtain enough advanced-node wafers from Taiwan Semiconductor Manufacturing Company Limited. The earnings release adds that the ASIC model requires third-party intellectual property. Celestial AI closed on 2 February 2026 and XConn on 10 February 2026, described as photonic-fabric scale-up interconnect and as PCIe and CXL switches, with revenue left inside the consolidated totals.
The warrant vests when Google buys
The commercial agreement with Google is dated 29 July 2026, and the warrant was issued on 18 August 2026, after the quarter had closed. The 10-Q records no unregistered equity sales during the three months ended 1 August 2026 and treats the warrant as a subsequent event. Performance tranches vest on purchases by Google and its affiliates of AI inference accelerators, storage controllers, network interface controllers, memory interface controllers and near-memory compute attached to the TPU ecosystem.
| Term in the 19 August 2026 8-K | What it states |
|---|---|
| Counterparty | Google LLC |
| Maximum shares | 58,970,907 at $206.58 |
| Time-based shares | 1,360,867, quarterly installments in year one |
| Performance shares | 240 tranches, one per $500 million of defined custom-product revenue through fiscal 2033 |
| What Note 3 records | End market, destination, direct versus distributor. No custom-dollar line |
Two pieces of arithmetic follow from those terms, and both should stay labelled as arithmetic. Two hundred and forty tranches times $500 million is $120 billion of defined custom-product purchases if every performance tranche vests. That threshold counts Google-and-affiliates purchases of the covered products, and it is a different object from company-wide revenue. Separately, 58,970,907 shares times $206.58 is about $12.18 billion, the cash payable if every share were exercised. Quoting that product as revenue renames the exercise cash.
Against the 876.9 million common shares outstanding on 21 August 2026, the full warrant would be about 6.7% if every share were issued, and the time-based slice of 1,360,867 shares would be about 0.16%. Diluted weighted-average shares for the quarter were 921.2 million and basic shares were 897.4 million, because the earnings release counts preferred stock assuming conversion. The warrant sits outside that diluted count. Murphy said on 27 August, in the call transcript, that covered-program revenue through fiscal 2028 "is already reflected in the overall custom revenue target we have previously provided." He left a fiscal 2029 custom figure at the prior call's "$10 billion kind of plus," tied to an April 2024 discussion of $8 billion to $10 billion, and Note 3 leaves those targets off the revenue page.
On the same call he expected fiscal 2027 company revenue of roughly $12 billion, about 45% growth, data center growth of about 60%, and a fiscal 2028 company figure of about $18 billion, with custom more than doubling that year. Dan Durn, Chief Financial Officer of Marvell Technology, said "the forecasted acceleration of our custom business" was "creating the sequential headwind in the fiscal third quarter." Second-quarter non-GAAP gross margin was 58.9%, against a third-quarter non-GAAP band of 57.5% to 58.5% and a GAAP band of 52.9% to 53.9%.
A guide band and a reported margin stay in different columns, the same split a Shopify earnings report forces on a software income statement. The exercise-price product has a cousin in list price versus reported net sales at Novo Nordisk: cash at $206.58 a share is payable on exercise, and the income statement collects it only if that cash arrives.
The other column, and a merger that was still a condition
Communications and other was $567.8 million in the quarter, up 10% from $515.6 million a year earlier and down 3% from $585.1 million in the quarter ended 2 May 2026. Murphy expected that end market to decline in the low-to-mid-teens percent range in the third quarter, sequentially and year on year, then to recover in the fourth, with the full year still approaching a 10% growth target. He also expected third-quarter data-center revenue to grow more than 20% sequentially and roughly 75% year on year.
Automotive ethernet was divested at the start of the third quarter of fiscal 2026, and the 27 August product footnote dates the sale to 14 August 2025. The MD&A says total revenue growth was partly offset by that lost portfolio, so the press release's 37% sits beside an income-statement change of 36.5%, from $2,006.1 million to $2,739.3 million. Scale-out switching, Murphy said, was on track to more than double this fiscal year on 51.2-terabit products. On 3 November 2026 the official account posted the Teralynx T100 at wire speed and described the bottleneck as having moved toward connectivity, a switch product rather than a single-customer ASIC.
RelatedCan Cloudflare (NET) Reach a $330 Bull Case Before $185?
AI clusters run at just 40-50% GPU utilization today. The bottleneck has moved from compute to memory to connectivity.
— Marvell Technology (@MarvellTech) November 3, 2026
In a new video, Rajagopal Krishnaswamy, AVP of Product Marketing for Cloud Switch at Marvell, shows a live Teralynx T100 running traffic at full wire speed. The… pic.twitter.com/medHbqIFod
On 1 November 2026 Marvell entered a merger agreement with Lumentum Holdings Inc. The Form 8-K filed on 2 November 2026 says the merger takes place upon the terms and subject to the conditions of that agreement. The August quarter is Marvell on its own, and Lumentum photonics revenue stays outside Note 3 until a closing.
The share price is reference data beside the filings
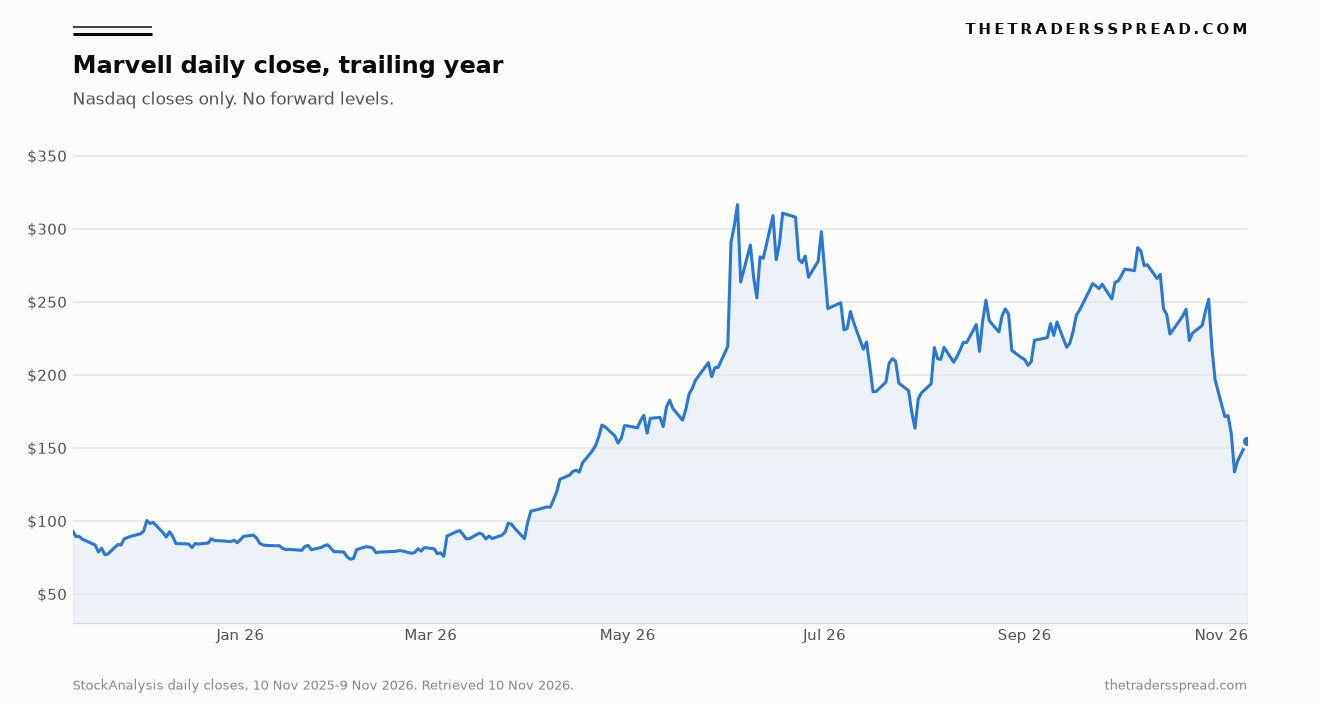
A search for marvell stock often starts from the daily close. The StockAnalysis quote feed showed a Nasdaq close of $154.60 at 4:00 p.m. Eastern on 9 November 2026, a 52-week high of $329.88 and a 52-week low of $70.685, retrieved 10 November 2026. The chart runs from the 10 November 2025 close of $93.23 through that 9 November close.
What to check in the next 10-Q
The next quarterly report should cover the quarter ending 31 October 2026. As of 10 November 2026 the latest 10-Q on EDGAR was still the quarter ended 1 August 2026.
- Where data-center dollars land against Murphy's "more than 20% sequential" and "roughly 75% year on year" comments, and whether Note 3 still stops at two end markets.
- Whether Distributor A is still near 44% of revenue, and how the direct-versus-distributor split moved.
- Whether the China destination share still carries the sentence about non-China customers with factories in China.
- Any new dollar line for custom revenue. Until that line exists, custom stays a discussion above the end-market table.
- GAAP and non-GAAP gross margin against Durn's guided bands for the custom-ramp quarter.
- The cover share count against 876.9 million, plus any vested warrant shares. Time-based shares follow the calendar, and performance shares follow Google custom-product revenue.
- Whether the Lumentum merger has closed, because a closing changes what net revenue includes.
FAQ
Does Marvell break out custom ASIC revenue in the 10-Q?
The quarter ended 1 August 2026 reports net revenue by end market, by shipment destination, and by direct customers versus distributors. Custom appears in the MD&A beside electro-optics, storage and switching, and in the fiscal 2026 10-K as its own product family. When management gives that family a dollar figure, it arrives on the earnings call, while Note 3 keeps the dollars inside the end-market totals.
Who are Marvell's largest customers in the quarterly report?
The 10% table prints Customer A at 16% of the quarter ended 1 August 2026 and Distributor A at 44%. The fiscal 2026 10-K showed 14% and 37%, and said the ten largest customers were 82% of that year's revenue. Google is named on the August warrant and NVIDIA on the March preferred stock. The revenue table still prints letters.
Does the Google warrant already count as revenue or as diluted shares?
The warrant was issued on 18 August 2026, after the quarter closed, and the 10-Q records no unregistered equity sales in the three months ended 1 August 2026. Of 58,970,907 shares, 1,360,867 vest with time in the first year and the rest vest in 240 tranches, one per $500 million of defined custom-product revenue through fiscal 2033. Exercise cash is $206.58 a share, and only after the relevant shares vest.
Why can US shipment revenue fall while data-center revenue rises?
US destination shipments were $190.8 million, 7% of the quarter, down from $310.8 million and 15% a year earlier, while data center was 79% of end-market revenue. Note 3 records where the shipment went, and says a substantial majority of the China shipments, 42% of the quarter, relate to non-China customers manufacturing there. The two series measure different facts.
What did management say about the rest of fiscal 2027?
On 27 August 2026 Murphy expected fiscal 2027 revenue of roughly $12 billion, about 45% above the prior year, and data-center growth of about 60%. Third-quarter revenue was guided at $3.150 billion, plus or minus 5%, and he expected custom to more than double in fiscal 2028. The next 10-Q is where the third-quarter actual replaces that midpoint.
This analysis is for information only. It is not a recommendation to buy or sell Marvell or any other security, and capital is at risk.