
Is EUR/TRY pricing another stretch of real lira appreciation, or the point where that cushion starts to thin?
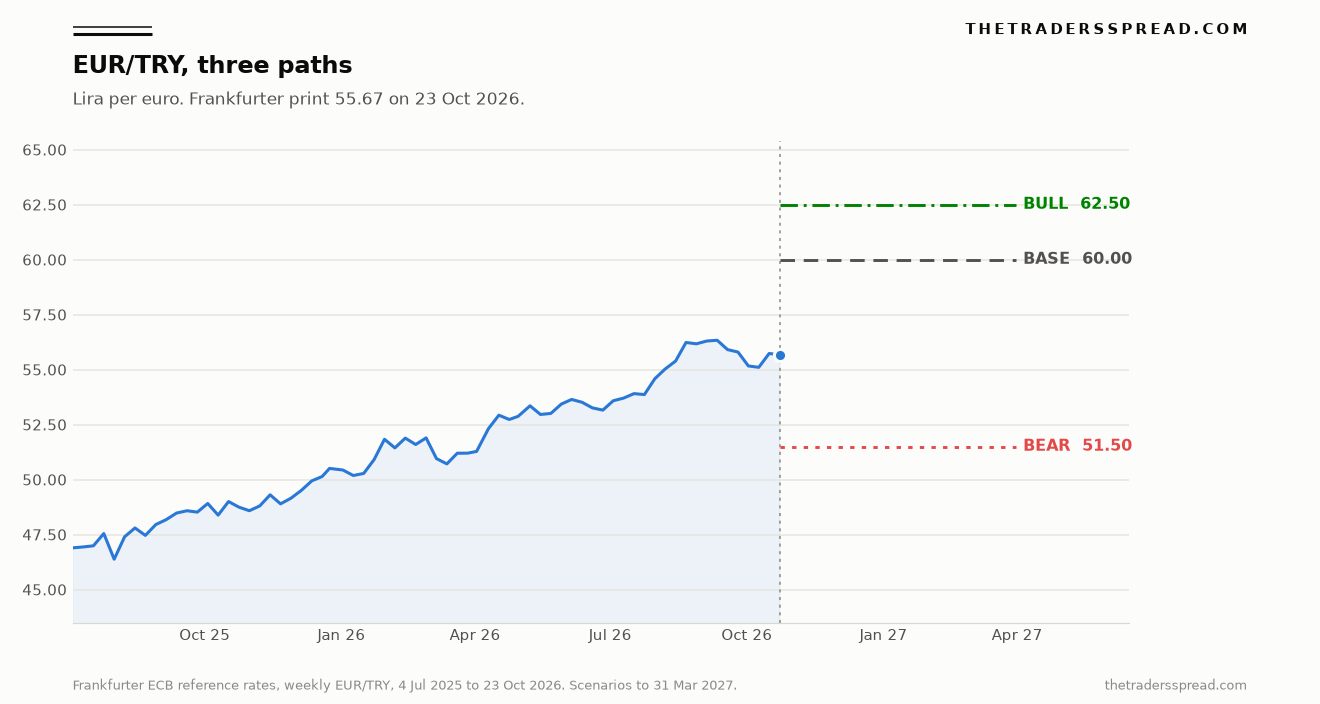
Frankfurter's ECB reference rate, retrieved 25 October 2026, put EUR/TRY at 55.6715 on 23 October 2026. The same feed showed the euro at 1.1193 dollars and the dollar at 49.738 lira, and those two legs multiply back to the cross within a rounding tick. The chart is the last fifteen months of that series. The table turns the opening question into levels.
| Path | Level | Versus 55.6715 | What has to hold |
|---|---|---|---|
| Bull | 62.50 | 12.3% higher | Real appreciation stalls and gives a little back, so the inflation gap does more of the work. |
| Base | 60.00 | 7.8% higher | The CBRT survey's dollar path, euro held at 1.1193 and then rounded, with real appreciation still slowing rather than stopping. |
| Bear | 51.50 | 7.5% lower | The cross returns to the April 2026 shelf as carry and lira deposits outweigh the inflation gap. |
| Level that ends the base | 53.00 | 4.8% lower | A break under the July floor, after which the crawl toward 60 is finished. |
Read 60 against the inflation gap and the level changes character. An EUR/TRY forecast that stops at the nominal crawl misses that split. Turkish annual CPI was 29.73% in September and euro-area HICP was 3.8%, so 1.2973 divided by 1.038 is about 1.25 over a full year. Across the 159 days from 23 October to 31 March, a flat real exchange rate lands near 61.4. The bull case at 62.50 sits just past that path, and the base at 60 sits short of it, so a nominal rise can still hide a real appreciation of the lira.
The dollar survey shows the same split from the other side of the cross. In the CBRT Survey of Market Participants for October, taken on 12 to 14 October, the modified mean for the dollar was 51.5471 lira at year-end and 59.2596 lira twelve months out. Hold the euro at 1.1193 and those paths are about 57.70 and 66.33 in EUR/TRY. Place 31 March about three-tenths of the way from the year-end figure to the twelve-month figure and the cross lands near 60.3, which the base case rounds to 60. That is a little faster than repeating the last year's 14.2% rise, a pace that would point near 59, and slower than the flat-real 61.4. The published USD/TRY forecast carries the dollar leg on its own.
Two rates, one cushion
On 22 October the Monetary Policy Committee cut the one-week repo from 37% to 36% and moved the corridor with it, overnight lending from 40% to 39% and overnight borrowing from 35.5% to 34.5%. Press release 2026-45 lists Governor Yaşar Fatih Karahan among the members in the room. The release says recent inflation confirms a slower underlying trend, weak demand has limited pass-through from supply shocks, and energy prices remain an upside risk. It ties the stance to the currency: "The tight monetary policy stance, which will be maintained until price stability is achieved, will strengthen the disinflation process through demand, exchange rate, and expectation channels." A later line says a significant and persistent deterioration in the inflation outlook would bring a tighter stance. The meeting summary was due within five working days.
The central bank's own account posted the corridor change the same day, which matters because the overnight band moved with the repo rate and the cut shifted the whole range.
MPC Decision of October 22, 2026: One-week repo rate has been cut by 100 basis points.
— CentralBankofTürkiye (@CentralBank_TR) October 22, 2026
The Committee has also lowered the Central Bank overnight lending rate from 40 percent to 39 percent and the overnight borrowing rate from 35.5 percent to 34.5 percent. pic.twitter.com/xwxCCUo7sN
The euro side had moved the other way on 10 September, when the Governing Council raised its three key rates by 25 basis points. From 16 September the deposit facility is 2.50%, the main refinancing rate 2.65% and the marginal lending facility 2.90%. Christine Lagarde, president of the ECB, said "the conflict in the Middle East continues to generate inflation pressures, and inflation is set to remain well above target for an extended period." Staff projections put headline inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028. The council has withheld a pre-committed path, and the deposit facility is still 2.50%. EUR/PLN sets that same ECB leg against a different central bank, and the sign on Türkiye's real rate is what changes the EUR/TRY arithmetic.
| Measure | Türkiye | Euro area | Gap |
|---|---|---|---|
| Policy rate | 36% one-week repo, 22 October 2026 | 2.50% deposit facility, from 16 September 2026 | 33.50 points |
| Latest inflation | 29.73% CPI, September 2026 | 3.8% HICP, September 2026 | 25.93 points |
| Ex-post real policy rate | 6.27 points | 1.30 points below zero | about 7.6 points |
| Published inflation path | MTP year-end 28.4% for 2026, then 21% for 2027 | ECB staff average 3.0% for 2026 and 2.5% for 2027 | The Turkish path dominates |
| Twelve-month survey | CPI 23.89%, policy rate 29.01% | Deposit facility still 2.50% after the September hike | Real-rate cushion still positive |
About 7.6 points of cushion remain after subtracting the inflation gap from the nominal rate gap: 36 minus 29.73, against 2.50 minus 3.8. September HICP at 3.8% already sits above the staff average of 3.0% for 2026, so some other months have to run below 3.0% if that average is going to land. Eurostat's 16 October release put energy at 1.71 points of the September print and services at 1.52, with food, alcohol and tobacco at 0.25 and non-energy goods at 0.29.
What a 14% nominal rise left behind
On 24 October 2025 the same series showed 48.7454. By 23 October 2026 it was 55.6715, a rise of 14.2%, and with Turkish inflation near 30% against euro-area inflation of 3.8% that rise is a real appreciation. Inside 2026 the low was 50.1841 on 9 January and the high was 56.4857 on 9 September, leaving the latest print 10.9% above the January low and 1.4% under the September high. The floor since 2 April is 51.2795 and the floor since 1 July is 53.1266. The bear case at 51.50 sits just above the April low, and 53 sits just under the July floor. EUR/SEK is a milder euro cross, and the lira keeps falling short of the inflation differential.
TurkStat's indicator panel, opened 25 October 2026, shows annual consumer inflation of 29.73% for September. Anadolu Agency's report of the TurkStat release, published 5 October, put the monthly change at 1.84%. Food and non-alcoholic beverages fell 0.20% on the month, while transport rose 2.79% and housing rose 2.71%. On the year, food was up 27.62%, transport 35.10% and housing 39.99%. The C index, excluding energy, food, alcohol, tobacco and gold, was up 28.70%, and prices were higher in 133 of 174 subclasses, so the annual rate is broad.
TurkStat's own account carried the annual and monthly CPI figures the morning of the release, and they match the indicator panel and Anadolu's account of the bulletin.
Consumer Price Index, September 2026
— turkstat (@TurkStat) October 5, 2026
Consumer price index (CPI) increased by 29.73% annually and increased by 1.84% monthly
You can visit our website for details.🔎
↪️ https://t.co/QrFrugmruo pic.twitter.com/kAkSC5MBYo
Industrial production was down 1.9% on the year in August, second-quarter GDP was up 2.3%, August unemployment was 7.8%, and October confidence stood at 84.8. Vice President Cevdet Yılmaz said on 6 September that the government had cut its 2026 growth forecast to 3.3% from 3.8%, while the market survey had 2.9%.
A dollar survey, translated
The October survey collected 71 responses, and the central bank says the modified means are the participants' answers, separate from its own forecast. Year-end CPI is 29.63% and twelve-month CPI is 23.89%. The current-month CPI expectation is 2.11%. On the policy rate, the first meeting was 36%, which is what 22 October delivered. The second meeting and the year-end rate are both 35%, and the twelve-month rate is 29.01%. Set 29.01 against 23.89% expected inflation and the survey still has about five points of real rate a year out. A one-point gap between 36 and 35 moves these FX paths much less than the question of whether real appreciation stops.
End-of-month USD/TRY was 49.7970, a hair above the 49.738 Frankfurter print, and at a constant 1.1193 that is about 55.74, essentially the spot. The year-end translation is a rise of roughly two lira per euro. March near 60.3 is only the early part of the climb toward the twelve-month dollar figure, which sits past the horizon used here.
Seda Guler Mert, chief economist for Türkiye at BBVA Research, and Adem Ileri, principal economist, wrote on 22 October that the bank is likely to keep an exchange-rate strategy that unwinds accumulated real appreciation, with inflation near 30% until late in the first quarter of 2027. They also wrote that the policy rate stays at 36% unless year-end inflation looks likely to finish below 30%, in which case another 100 basis point cut in December would line up with the consensus they were watching. That is the bull case in one place: a controlled give-back of real appreciation, nominal rate still high, which is why 62.50, just past the flat-real 61.4, is the upside here rather than the survey's twelve-month dollar translation.
Yılmaz, in the Daily Sabah account of the 6 September presentation, set the government's inflation path at 28.4% by the end of 2026 and 21% in 2027. "We expect inflation to start declining again in the fourth quarter of 2026 and to reach 28.4% by the end of the year," he said. September's 29.73% is already above that year-end figure, so hitting 28.4 means the annual rate falls about 1.3 points in one quarter, and the survey at 29.63% leaves almost the whole of that decline still ahead. He also said the central bank had put the war's direct and indirect effect on inflation at about seven points. The program number still needs the next three monthly prints.
Key facts
- EUR/TRY stood at 55.6715 on 23 October 2026, up from 48.7454 on 24 October 2025, a rise of 14.2%, on Frankfurter's ECB reference rates retrieved 25 October 2026.
- The CBRT cut the one-week repo to 36% from 37% on 22 October 2026 and reset the overnight corridor to 34.5-39%, in press release 2026-45 dated 22 October 2026.
- Turkish annual CPI was 29.73% in September 2026, the monthly change was 1.84% and the C index was 28.70%, on the TurkStat panel retrieved 25 October 2026 and in Anadolu Agency's 5 October report of the release.
- Euro-area HICP was 3.8% in September 2026, up from 3.2% in August, with energy contributing 1.71 points, and the ECB deposit facility has been 2.50% since 16 September 2026, per Eurostat on 16 October 2026 and the ECB statement of 10 September 2026.
- Participants looked for year-end USD/TRY at 51.5471, twelve-month USD/TRY at 59.2596 and year-end CPI at 29.63%, in the CBRT survey taken on 12 to 14 October 2026.
- The government put year-end inflation at 28.4% and 2026 growth at 3.3%, with 2027 inflation at 21%, in remarks by Vice President Cevdet Yılmaz reported by Daily Sabah on 6 September 2026.
Bull case at 62.50
A level of 62.50 is 12.3% above the latest print and a little past the flat-real result near 61.4. It is the case in which the bank lets some of the past year's real appreciation leak back out, the strategy Mert and Ileri described, while energy keeps the euro firm. Clearing 62.50 would also take the 9 September high of 56.4857 out by a wide margin.
Where 60 comes from
The base case is the target. It rounds the survey bridge, near 60.3 with the euro held at 1.1193, to 60. Repeating the last year's 14.2% pace across the same 159 days points near 59, so 60 is a small step faster than the trailing crawl and a clear step slower than flat-real 61.4. In real terms the lira is still gaining, because 7.8% in five months runs well short of a 26-point inflation gap.
RelatedGBP/SEK Trades Its Own Rate Path, Not a Dollar Cross
What keeps 60 plausible is the cushion that survived the cut: about 6.3 points ex post, and about five points on the survey's twelve-month pair of a 29.01% policy rate against 23.89% expected inflation. The base case ends at 53, 4.8% under the latest print and a fraction under the 1 July low of 53.1266. Below 53 the summer shelf is gone and the April shelf at 51.50 is the path in play. Conviction on the base is a three out of five: the crawl has the survey and a positive real rate behind it, and a 100 basis point cut is small next to a 30% inflation rate.
Bear case at 51.50
A finish at 51.50 is 7.5% under the 23 October print and a fifth of a lira above the 2 April low of 51.2795. Getting there means the nominal cross falls and real appreciation speeds up, after a year in which it was already running. Yılmaz said the share of lira deposits had risen from 31.6% to 61.5% as of 28 August, and that gross reserves had increased by $89.7 billion to $188.2 billion, with the risk premium down from the 700s to below 220. Those are his figures, as Daily Sabah reported them, and they describe a domestic preference for the lira that a positive real rate can keep feeding.
A euro that softens, if the next decision leaves the deposit rate at 2.50% and energy's contribution fades, would help that preference show up in the cross. The stall under 56.49, with spot still 1.4% short of that high, is already on the chart. The chain breaks if the next CPI print arrives near the survey's 2.11% and the annual rate sticks near 30%, because the inflation gap would still be pushing the quote up and the bear case would then need the euro side to do the work.
The prints that would move the levels
The next CPI release sits against a survey figure of 2.11% for the current month. A print near that leaves the 28.4% program number dependent on the two months after it. The deposit facility is still 2.50%. The survey has the second CBRT meeting, and the year-end policy rate, at 35%. As a currency input, 35% and 36% are close. What would change the description is a run of CPI that pushes the Turkish real rate through zero, which revives the bull case, or a run that drops the annual rate through 28%, which gives the bear case a domestic reason on top of the deposit story.
Questions the levels leave open
What is EUR/TRY pricing at 55.67?
The cross is pricing a nominal rise that still leaves the lira firmer in real terms. September inflation of 29.73% in Türkiye against 3.8% in the euro area puts a flat real rate near 61.4 by 31 March. The survey's dollar path, with the euro held at 1.1193, points near 60.3 on the same date. Both sit above the Frankfurter print of 55.6715 and inside a full-year catch-up to the inflation gap.
Why can the lira ease in the quote while the policy rate stays far above inflation?
The inflation gap is wider than the recent crawl and narrower than the nominal rate gap. A repo rate of 36% minus September CPI of 29.73% is still about 6.3 points, while the gap versus euro-area inflation is about 26 points. A cross that rises about 8% in five months can sit beside a positive real rate, the exchange rate taking part of the price gap and the policy rate taking the rest.
Which level ends the base case?
The base case ends under 53, just below the 1 July low of 53.1266 and about 4.8% under the 23 October print of 55.6715. Under that shelf the crawl toward 60 stops being the right description, and the bear case at 51.50, just above the 2 April low of 51.2795, is the range that has to be argued instead. The September high at 56.4857 is still 1.4% overhead.
After the three paths
If the next CPI print lands near the survey's 2.11% and the following CBRT meeting takes the repo rate to the 35% participants had already written down, does EUR/TRY keep the walk toward 60, or does the real-rate cushion pull the cross back through 53?
Scenario analysis of published official data and one reference-rate history. It is not a recommendation to buy, sell or hold EUR/TRY or any other instrument.