
Is Cisco, at a $102.01 cash close, being priced for $9 billion of hyperscaler AI infrastructure revenue, or for a networking quarter whose next official guide already steps down?
Of the $2.5 billion increase in the fiscal 2027 revenue-guide midpoint, $1.5 billion is the hyperscaler AI infrastructure line. That line moved from $7.5 billion in Cisco's 12 August 2026 release to $9 billion in the 12 November 2026 release. The other $1.0 billion is the residual after that subtraction, and Cisco published no bridge between the two guides. The cash close of $102.01 was up $1.25, or 1.24%, from the prior close of $100.76. After-hours trading was $101.70, down $0.31, as of 7:59 pm Eastern. A record quarter and a higher AI revenue expectation finished the evening $0.31 under the cash close.
StockAnalysis stamps that cash close at 4:00 pm Eastern on 12 November 2026. Cisco's own post is timestamped 21:08 UTC, eight minutes later. The release sets the earnings call for 1:30 pm Pacific the same day, half an hour after the 1:00 pm Pacific cash close. The $102.01 print is the session that ended before that call. The $101.70 print is the one that sits after the release.
Key facts
- Cash close $102.01 on 12 November 2026, up $1.25, or 1.24%, from $100.76, with after-hours at $101.70 as of 7:59 pm Eastern (StockAnalysis CSCO quote, retrieved 13 November 2026).
- First-quarter fiscal 2027 revenue was $18.5 billion, up 24%, with GAAP earnings per share of $1.14 and non-GAAP earnings per share of $1.40, for the period ended 24 October 2026 (Cisco first-quarter release, 12 November 2026).
- The expectation for AI infrastructure revenue from hyperscalers was raised to $9 billion in fiscal 2027, from $7.5 billion in the prior guide (Cisco first-quarter release, 12 November 2026; the $7.5 billion figure is in the fourth-quarter release, 12 August 2026).
- Fiscal 2027 guidance is revenue of $74.8 billion to $75.8 billion and non-GAAP earnings per share of $5.47 to $5.53, against the August guide of $72.2 billion to $73.4 billion and $5.05 to $5.11 (Cisco releases, 12 November 2026 and 12 August 2026).
- Networking revenue was $11,132 million, up 43%, and security revenue was $2,120 million, up 7% (Cisco first-quarter product table, 12 November 2026).
- GAAP gross margin was 63.7% and non-GAAP gross margin was 65.6%, against 65.5% and 68.1% a year earlier (Cisco first-quarter release, 12 November 2026).
- The 4 June 2026 close was $130.00, the 6 November 2026 session low was $93.35, and the 12 November close was $102.01 (StockAnalysis CSCO daily history, retrieved 13 November 2026).
1. The quarter against the August guide
Cisco's first-quarter release, dated 12 November 2026, covers the period ended 24 October 2026. The income statement shows revenue of $18,517 million, against $14,883 million, the 24% increase the summary rounds to $18.5 billion. Product revenue was $14,667 million, up 32%, and services revenue was $3,850 million, up 1%. GAAP net income was $4,552 million, up 59% from $2,860 million, or $1.14 a share against $0.72. Non-GAAP net income was $5,567 million, up 39%, or $1.40 a share against $1.00.
Chuck Robbins, chair and chief executive, called the revenue growth and the non-GAAP earnings-per-share growth the strongest in over 15 years, and described the early stages of a multi-year networking supercycle. Mark Patterson, chief financial officer, said revenue, non-GAAP operating margin and non-GAAP earnings per share exceeded the high end of guidance, and gave that beat as the reason for raising the fiscal 2027 guides.
The guide those results cleared was set on 12 August in the fourth-quarter release: revenue of $18.0 billion to $18.2 billion, GAAP earnings per share of $1.08 to $1.10, non-GAAP earnings per share of $1.32 to $1.34, non-GAAP gross margin of 65% to 66%, and non-GAAP operating margin of 35.5% to 36.5%. Revenue of $18,517 million is $317 million above the $18.2 billion high end. Non-GAAP earnings per share of $1.40 cleared $1.34 by $0.06. Non-GAAP operating margin of 37.8% cleared the 35.5% to 36.5% range. Non-GAAP gross margin of 65.6% landed inside 65% to 66%.
The new full-year guide is revenue of $74.8 billion to $75.8 billion, GAAP earnings per share of $4.38 to $4.44, and non-GAAP earnings per share of $5.47 to $5.53. August had set $72.2 billion to $73.4 billion, GAAP earnings per share of $4.00 to $4.06, and non-GAAP earnings per share of $5.05 to $5.11. On our arithmetic the revenue midpoint moved from $72.8 billion to $75.3 billion, a raise of $2.5 billion, and the non-GAAP earnings-per-share midpoint moved from $5.08 to $5.50, a raise of $0.42.
Second-quarter guidance is the step down in the opening question. Cisco expects revenue of $18.0 billion to $18.2 billion, the same range this quarter just beat, GAAP earnings per share of $1.07 to $1.09, and non-GAAP earnings per share of $1.34 to $1.36. Non-GAAP gross margin is guided at 65% to 66%, and non-GAAP operating margin at 36% to 37%, under the 37.8% just printed. The $18.1 billion midpoint is $417 million, or 2.3%, under $18,517 million. The non-GAAP earnings-per-share midpoint of $1.35 sits under the $1.40 just printed.
On those midpoints, first-half non-GAAP earnings per share of $1.40 plus $1.35 equal $2.75, and a $5.50 year leaves another $2.75, while first-half revenue of about $36.6 billion leaves about $38.7 billion of a $75.3 billion year. The half split is our subtraction from the published ranges.
2. Where the $9 billion sits
The November summary states the new line in one sentence: Cisco raised its expectation for AI infrastructure revenue from hyperscalers to $9 billion in fiscal 2027, more than double the fiscal 2026 total. The August release is where the prior numbers sit. Cisco delivered approximately $4 billion of that revenue in fiscal 2026, expected $7.5 billion in fiscal 2027, took $4 billion of orders in the fourth quarter, and took $9.3 billion of orders across the year. The $7.5 billion mark is an August figure.
The $9 billion is a full-year expectation, not a quarterly run-rate. Against the new revenue midpoint of $75.3 billion it is 12.0% of guided revenue. Against the approximate $4 billion delivered in fiscal 2026 it is 2.25 times, which lines up with "more than double." The $1.5 billion step from $7.5 billion to $9 billion is 60% of the $2.5 billion rise in the revenue midpoint, and the other $1.0 billion is the implied change in everything else, from $65.3 billion to $66.3 billion, on our arithmetic.
Cisco's own account posted the quarter's revenue and the two earnings-per-share figures the evening of the release.
📣 Just announced - #CSCOQ1FY27 Earnings.
— Cisco (@Cisco) November 12, 2026
Q1 Revenue: $18.5B
Q1 EPS: $1.14 GAAP $1.40 non-GAAP
Read the full news release ➡️ https://t.co/UaIWzwIVAp$CSCO pic.twitter.com/ElWJXWXGlY
Order totals for the quarter ended 24 October are absent from the November release. The order totals Cisco did publish describe the quarter ended 25 July 2026: product orders up 35% year over year, up 25% excluding hyperscalers, and networking product orders up 40%, an eighth straight double-digit quarter. Those rates belong to July, and using them for October would mix two periods.
At $102.01 the share is 18.5 times the $5.50 non-GAAP midpoint and 23.1 times the $4.41 GAAP midpoint. The per-share table shows 3,978 million diluted shares and 3,948 million basic shares, and 3,978 million times $102.01 is an equity value of $405.8 billion.
3. Margin, inventory and the backlog
Gross margin moved the other way from revenue. GAAP gross margin was 63.7% overall, 61.8% on product and 70.9% on services, against 65.5%, 64.5% and 68.4% a year earlier. Non-GAAP gross margin was 65.6%, 63.7% and 72.9%, against 68.1%, 67.2% and 70.7%. The total is 1.8 points lower on a GAAP basis and 2.5 points lower on a non-GAAP basis, with services margin higher and product margin lower.
Product was 79.2% of revenue, against 74.4% a year earlier: $14,667 million over $18,517 million, and $11,077 million over $14,883 million. More of the quarter came from product, the lower-margin line, while services grew 1%. That mix sits in the same quarter as the compression in the total margin.
Networking was $11,132 million, up 43%, equal to 75.9% of product revenue and 60.1% of total revenue on our arithmetic. August's product table had fourth-quarter networking at $9,791 million, up 28%. Security was $2,120 million, up 7%, collaboration $1,136 million, up 8%, and observability $279 million, up 2%. The networking print sits beside the cloud-switch cycle on this desk, and the slower security line sits beside Palo Alto's billings line.
Americas revenue was $11,506 million, up 28%, EMEA was $4,456 million, up 18%, and APJC was $2,556 million, up 21%, with the release noting that the amounts may not sum.
GAAP operating expenses were $6,190 million, down 3% and 33.4% of revenue, which the summary rounds to $6.2 billion. Non-GAAP operating expenses were $5.1 billion, up 2% and 27.8% of revenue. The reconciliation shows smaller add-backs than a year ago: share-based compensation of $775 million against $884 million, acquisition-related amortization of $191 million against $231 million, and impairments and restructurings of $28 million against $147 million. GAAP operating income was $5,598 million, a 30.2% margin against 22.6% a year earlier. Non-GAAP operating income was $7,007 million, a 37.8% margin against 34.4%.
Cash from operations was $4,357 million against $3,212 million, equal to 95.7% of GAAP net income of $4,552 million on our arithmetic. Accounts receivable contributed $1,570 million of cash, and inventories absorbed $686 million. Receivables on the balance sheet were $5,928 million against $7,470 million at 25 July 2026, and inventories were $6,384 million against $5,694 million, up $690 million or 12.1%.
Remaining performance obligations were $46,169 million, up 8% from $42,873 million and $565 million, or 1.2%, below the $46,734 million at 25 July 2026. Product obligations were $23,396 million against $23,436 million, and services obligations were $22,773 million against $23,298 million. Deferred revenue rose to $30,058 million from $29,781 million at year-end and from $27,969 million a year earlier. Obligations minus deferred revenue narrowed from $16,953 million to $16,111 million, a gap of $842 million on our arithmetic, in a quarter when revenue grew 24%.
The dividend and repurchase table shows $3,656 million returned, rounded to $3.7 billion in the summary. The dividend line was $1,654 million, or $0.42 a share, and the repurchase was about 18 million shares at $112.38, or $2,002 million, with $6.1 billion of authorization still open and no termination date. That average repurchase price is $10.37 above the $102.01 close.
4. What the tape has already done
Daily history from StockAnalysis, retrieved 13 November 2026, runs from a 12 November 2025 close of $73.96 to the $102.01 close, a rise of 37.9%. The low that first day, $71.72, is the 52-week low on the quote. The high on 4 June 2026 was $130.366, the 52-week high, and the close was $130.00. From that close the share is down 21.5%. From the high it is down 21.8%.
The path after June included another high day and then a hard down session. On 12 August the close was $123.88. On 13 August it was $113.47, down 8.4% on the history file's change field, on volume of 61,560,412 shares. The August release set that call for 1:30 pm Pacific on 12 August, so 13 August was the first full session after that call.
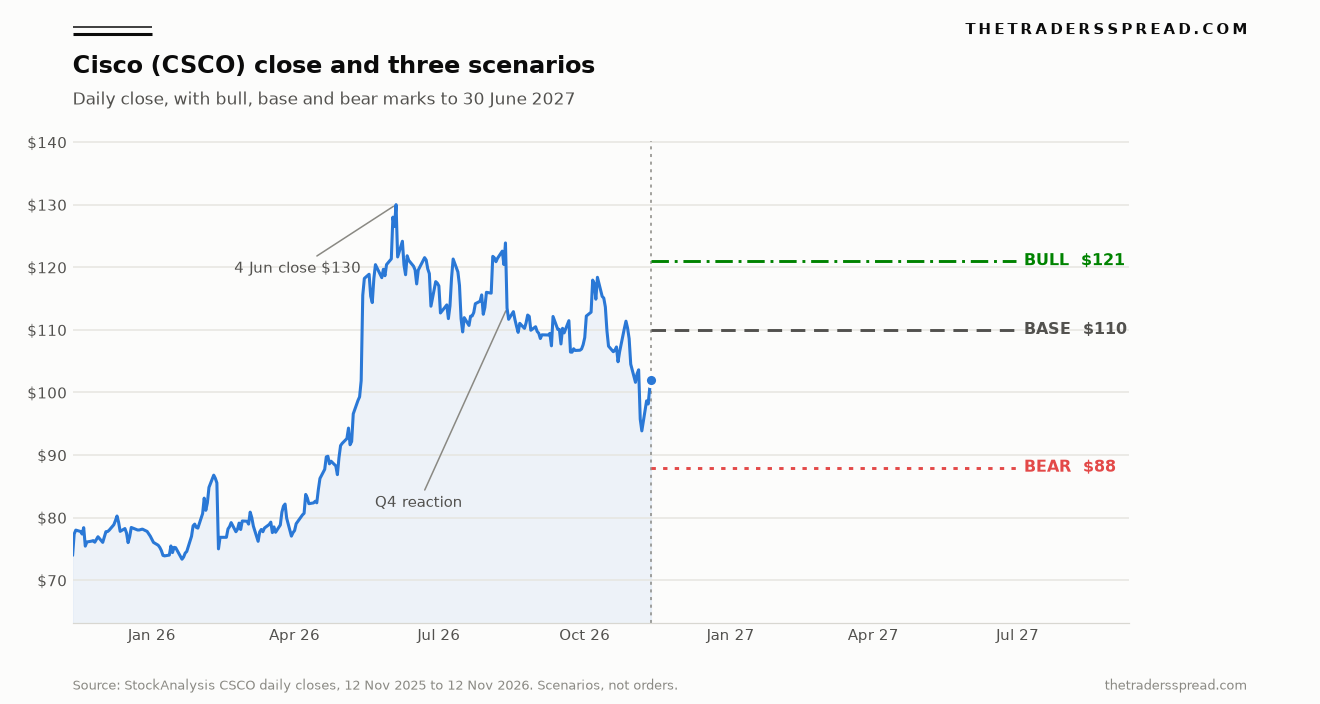
From the 9 October close of $118.39 the share fell to $93.85 on 6 November, a decline of 20.7%, with a session low of $93.35. The 5 November close was $95.72, down 7.62% from $103.61. By 11 November the close was $100.76, and on 12 November it was $102.01, up 8.7% from 6 November, on volume of 26,714,497 shares. The 12 November volume is the regular session, lighter than 13 August, and the post-release price in hand is the after-hours print of $101.70.
Related6 Measures Split Intuitive Surgical (ISRG) From Devices
5. Three prices on one multiple
The three prices are multiples of the $5.50 non-GAAP midpoint, on a share already at 18.5 times that midpoint, drawn out to 30 June 2027. The same three-price layout is how the desk framed Broadcom, and the link is that layout alone.
| Case | Price | Multiple of the $5.50 midpoint | Versus the $102.01 close |
|---|---|---|---|
| Bull | $121 | 22.0 times | 18.6% above |
| Base | $110 | 20.0 times | 7.8% above |
| Bear | $88 | 16.0 times | 13.7% below |
$121 is 22 times $5.50 and sits under the 4 June close of $130.00 and under the 12 August high of $124.45, so the bull case is a multiple the share has already traded, on the raised guide. $110 is 20 times $5.50 and matches the late-October closes of $110.24 and $110.29. $88 is 16 times $5.50. It sits under the 6 November low of $93.35 and near the 27 April close of $88.26.
Both the $102.01 cash close and the $101.70 after-hours print sit between $88 and $121. A cash close under $93, beside the 6 November low, is the tripwire that would shift weight before the share reached the $88 bear case.
6. The weighting, and what would move it
The base case of $110 carries the most weight. The share already stands at 18.5 times a guide raised the same evening, after-hours trading finished at $101.70, and the second-quarter guide is lower on revenue, on non-GAAP earnings per share and on non-GAAP operating margin. $121 needs the AI line or the margin to do more than November already banked. $88 needs the step-down to continue, or the multiple to move from 18.5 times toward 16. Through 7:59 pm Eastern the tape had left the share between those prices.
Chuck Robbins posted the record quarter the same evening, including revenue up 24% and non-GAAP earnings per share up 40%.
Proud of our Cisco team for an incredible start to FY27. We delivered record quarterly revenue of $18.5B, up 24% y/y, and non-GAAP earnings per share of $1.40, up 40% y/y — our strongest growth rates in over 15 years. Thank you to our teams for their execution and our customers,…
— Chuck Robbins (@ChuckRobbins) November 12, 2026
Weight moves toward $121 if a later official guide lifts the $9 billion hyperscaler AI line again and non-GAAP gross margin climbs back toward the year-ago 68.1%, with networking still growing at a double-digit rate. A first full session after a future release that holds the prior close, unlike 13 August, would point the same way. Weight moves toward $88 if second-quarter revenue lands at or under $18.0 billion, if the $5.50 non-GAAP midpoint is cut, or if the cash close prints under $93.
Until one of those arrives, the weighting stays with $110, the bull case stays at $121 and the bear case stays at $88. The reference price is the $102.01 cash close, the horizon is 30 June 2027, and conviction sits in the middle of the scale. The raise is in the release. The tape's answer through the evening was $0.31. The next official revenue range is the range just beaten.
FAQ
What did Cisco set as hyperscaler AI infrastructure revenue?
The 12 November 2026 release raised AI infrastructure revenue from hyperscalers to $9 billion for fiscal 2027, more than double the prior-year total. The 12 August release had put fiscal 2026 delivery near $4 billion and the old fiscal 2027 expectation at $7.5 billion, with $4 billion of fourth-quarter orders and $9.3 billion of orders for the year. The $9 billion figure is a full-year revenue expectation against a $75.3 billion revenue midpoint.
Why is the Cisco share still near $102 after a record quarter?
The 12 November cash close was $102.01, up $1.25, and after-hours trading was $101.70 as of 7:59 pm Eastern. The call was set for 1:30 pm Pacific, after that close, so the regular-session gain predates the call. The share also sits 21.8% under the 4 June high of $130.366. Next-quarter revenue guidance of $18.0 billion to $18.2 billion is under the $18.5 billion just reported, and both gross-margin measures were lower than a year earlier.
What would shift the base case on Cisco?
The $110 base case keeps the most weight while fiscal 2027 guidance stays at $74.8 billion to $75.8 billion of revenue and $5.47 to $5.53 of non-GAAP earnings per share, with the share between $88 and $121. A higher official AI revenue line, and non-GAAP gross margin nearer the year-ago 68.1%, would add weight to $121. Revenue at or under $18.0 billion next quarter, a lower $5.50 midpoint, or a cash close under $93 would add weight to $88.
This is analysis of published prices and company figures, not a recommendation to buy or sell Cisco or any other security. Guidance, multiples and scenarios can change, and capital is at risk.