I read IronFX off the CySEC register and off the firm's own schedule in the same sitting, before I treated the homepage as anything more than a door.
The register and the schedule do not name the same company.
On 3 October 2026 the site a non-EU visitor loads, ironfxglobal.com, says IronFX is a trade name of Notesco I Limited, registered in the Marshall Islands under number 120910, and that the services on that website are provided by Notesco I Limited and not by any affiliate. The CySEC register, opened the same afternoon, lists Notesco Financial Services Ltd under licence 125/10, dated 16 November 2010, at 2 Iapetou Street, Agios Athanasios, CY-4101 Limassol, company number 260651. Approved domains: www.fxlift.eu and www.ironfx.eu. ironfxglobal.com is not one of them.
Stop at the brand and the two pages look like one firm. They are not.
Key facts
- Global-site contract, 3 October 2026: Notesco I Limited, Marshall Islands 120910. Terms dated 11 August 2026, version 2026/002. Governing law: Marshall Islands.
- CySEC file: Notesco Financial Services Ltd, licence 125/10, 16 November 2010. Former names IronFX Global Limited and IronFX Limited. Domains: ironfx.eu and fxlift.eu only.
- EUR/USD on the global schedule: Standard 1.2 pips, no commission, $12.00 round turn per standard lot before swaps. ECN Raw: 0 pips, commission "Yes", no dollar rate.
- ironfx.eu: no longer accepting individual investors. Footer still says Notesco Financial Services Limited, CySEC 125/10.
- CySEC settlement: announced 2 April 2024, decision 29 January 2024, Regulation (EU) No 600/2014, "Settlement €100.000". Conduct not described.
- Pillar III, Cyprus firm, 31 December 2024, prepared 30 April 2025: own funds 3.177 (US$ thousands), ratio 373% vs a 100% minimum. Equity 3.236 after losses of 15.551.
- ECB reference via frankfurter.dev: EUR/USD 1.1225 on 2 October 2026. No newer fix on this Saturday. A standard-lot EUR/USD pip is $10 regardless of that rate.
The company named on the contract
The global footer does not hide behind "a member of the group". Services on that website, it says, are provided by Notesco I Limited and not by any affiliate. The same sentence and the same number run through the terms of business linked from the legal documents page. Clause 1 once spells the place "Marshal Islands", missing an l. The header spells Marshall Islands. Registration 120910 does not change.
The terms are version 2026/002, dated 11 August 2026. The agreement and all transactional relations are governed by Marshall Islands law, and the stated court is a Marshall Islands court. There is no licence number in the clauses I read, and no Vanuatu company as counterparty. Older write-ups that put this retail contract in Vanuatu, or with a British Virgin Islands firm, are not what the 2026 terms say.
EU residents are told the site is not directed at them and falls outside the European and MiFID II framework. Australian residents are excluded. So are residents of the USA, Cuba, Sudan, Syria and North Korea. A pop-up still offers a button to continue. A button is not a licence.
One dull infrastructure fact belongs beside that. On 3 October 2026 the public DNS answer for ironfx.com, www.ironfx.com and www.ironfx.co.uk was 127.0.0.1, and the connection was refused. The contract site that resolves is ironfxglobal.com. Neither name is a CySEC approved domain.
What the CySEC file actually contains
Notesco Financial Services Ltd is still an authorised Cypriot investment firm. Licence 125/10 dates from 16 November 2010. Previous names are IronFX Global Limited and IronFX Limited. Approved domains are only www.fxlift.eu and www.ironfx.eu. The address is in Limassol, and the register email is compliance@notesco.com.
The EU site matches that file, then narrows it. IronFX, the footer says, is a trade name of Notesco Financial Services Limited, authorised by CySEC under 125/10. A notice says that after a change in business strategy the company will no longer accept individual investors. Existing clients are pointed to support@ironfx.eu. An account-types URL on ironfx.eu did not load. The notice on the pages that did is enough.
Finance Magnates put IronFX on a list, in an interview with Dr George Theocharides published 18 December 2025, when he was chair of CySEC. The magazine named IronFX with Exness, FXTM and RoboMarkets as firms that had closed retail service in Europe. That sentence is the magazine's. It matches the firm's own notice.
In that interview he also spoke about investors who seek looser rules. "There's always the possibility that some investors, even when fully aware of the risks, still choose to take on higher levels of exposure," he said. "They can do so on their own – reverse solicitation is allowed; it's not prohibited. But when investors go to companies based in third-country jurisdictions where there are no such restrictions, they face greater risks." He was not, in those lines, judging Notesco I Limited.
He had drawn the limit more sharply in an interview published 18 July 2023, again as chair. "We don't have powers over the entity in the third country because there's a different regulator there." He added that if CySEC thought a group was using the MiFID licence to move European clients toward third-country entities, "we will take severe action." The quote is not a finding against this firm.
The sanction page is narrower than most retellings. The CySEC decision is an announcement of 2 April 2024 on a board decision of 29 January 2024, about Notesco Financial Services Ltd, under Regulation (EU) No 600/2014. The subject line is "Settlement €100.000", which is €100,000. The judicial-review field is blank, and the page does not say what the firm did.
The Cyprus balance sheet, on its own
The Pillar III disclosure, prepared 30 April 2025 for 31 December 2024, is solo. From 20 March 2023, after CySEC approval, consolidated reporting stopped. Subsidiaries still listed, all non-operational, are IRONFX Global NZ Limited, IRONFX Global (Ukraine) LLC, IRONFX Global (Russia) LLC and IRONFX Global Japan Limited. Notesco I Limited is not there. The capital figures are the Cyprus company alone.
Tables are in US$ thousands. Own funds, tier 1 and common equity tier 1 are each 3.177. Prose says own funds beat the regulatory minimum by $2.325K, at a ratio of 373% against a 100% minimum. 3.177 divided by 0.852 is about 3.73, so the 852 under that ratio is US$852,000 and the excess is US$2.325 million, not two thousand dollars. The firm also says own funds stay above a permanent minimum of US$852 thousand, "which corresponds to the PMCR of the Company (US$ 779 thousand)." Both figures are printed. I am not merging them.
The equity table shows share capital 7.460, share premium 11.327, retained earnings (15.551) and equity 3.236. 7.460 plus 11.327 minus 15.551 equals 3.236. Equity is positive because the premium covers the loss. Assets 7.576 minus liabilities 4.339 equal 3.237, one unit off that line. A second template shows retained earnings of (15.583). I cite 15.551, the figure that ties to published equity. None of it is Notesco I Limited's balance sheet, and none of it says the Cyprus firm is insolvent.
The legal entity identifier in that disclosure is 5493001Y4VOVDB4P8340. Company number HE 260651 matches the register. Incorporation was in Cyprus in 2010, under the Companies Law, Cap. 113.
EUR/USD, turned into dollars
The figure worth comparing is the published round-turn cost of one standard lot of EUR/USD. Spread in pips, times $10, plus any round-turn commission the same page states. The quote currency is the dollar, so a pip on 100,000 euros is $10 whether the ECB reference is 1.1225 or not. The spread is not doubled. A per-side commission is, because a round turn opens and closes.
The spread table on 3 October 2026 shows EURUSD at 1.2 pips Standard Floating, 1.2 Standard Fixed, 0 ECN Raw and 0.3 VIP ECN. Spreads are indicative. Live numbers are in the terminal. Zero fixed spreads on majors go to 3 pips from 11pm to 2am GMT+2, and live fixed spreads become floating in that window.
The account page adds commission. Both standard accounts: forex 1.2 pips, gold 2.5, "No Commission", leverage 1:2000, USD base, stop-out 20%, swap-free yes, minimum lot 0.01, MT4 and MT5. Raw ECN: forex 0, gold 1.1, commission "Yes", leverage 1:1000, stop-out 50%, no swap-free. VIP: forex 0.3, no commission, leverage 1:200, stop-out 50%. Standard rows include futures and shares. Raw and VIP stop at forex, metals, indices and commodities.
The standard account is the one a retail reader can price. 1.2 pips and no commission is $12.00 round turn on a standard lot. No minimum deposit is printed, so none is quoted here. No dollar rate sits beside the Raw "Yes", on the table or in the 2026 terms. A zero spread with a blank commission is not a cost. VIP stays off the chart: 0.3 pips would be $3.00, and the page never says who qualifies. Gold's 2.5 pips are not converted. A gold pip is not $10.
Two other schedules, read the same day
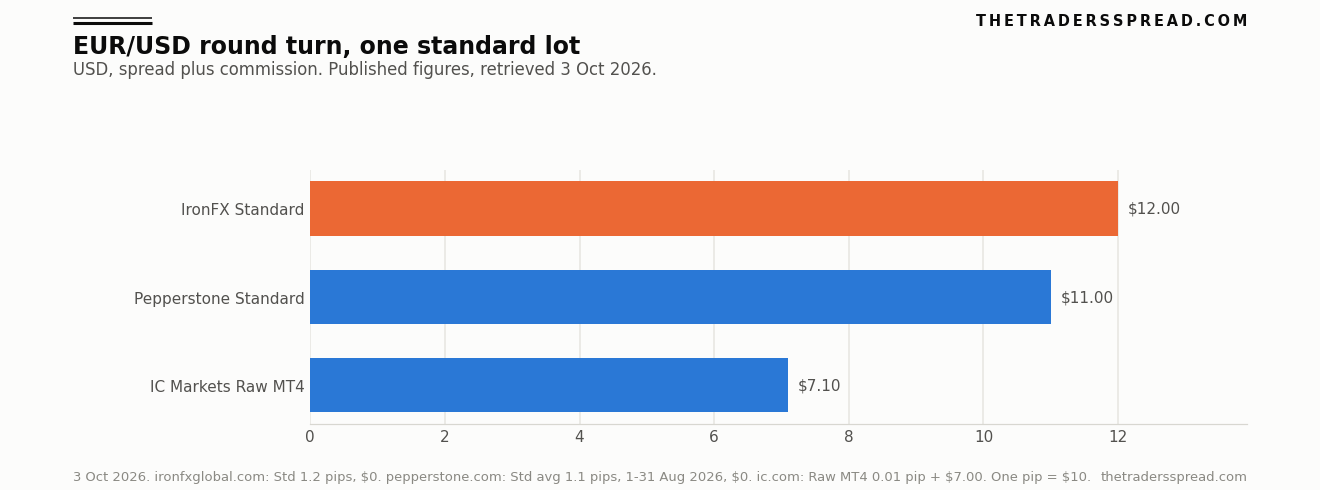 Orange is IronFX Standard at $12.00. Blue is two other published constructions, not one simultaneous test.
Pepperstone, Pepperstone Group Limited of Melbourne, AFSL 414530, shows EURUSD Standard minimum 1 pip and Standard average 1.1, from 1 to 31 August 2026, all sessions including rollover. It charges no forex commission on the Standard CFD account. 1.1 times $10 is $11.00. The average is not split by platform, and the row is in pips, so no Australian-dollar conversion applies. Razor, at a 0.1 average and with a commission, is a different account and is not charted.
IC Markets is the page www.icmarkets.com redirected to. IC and IC Markets Global are trading names of Raw Trading Ltd, Seychelles FSA securities dealer SD018. EU visitors cannot apply there. IC Markets (EU) Ltd is named as a separate CySEC firm. I did not lift a licence number for that EU company, so none is printed.
The EURUSD cells are raw minimum 0, raw average 0.01, standard minimum 0.8, standard average 0.1. An average under the minimum is unusable, so the standard column is not charted. An intro line claims an average EUR/USD spread of 0.1 pips, a third figure, not the raw cell. The bar uses the printed raw average, 0.01 pips, which is $0.10.
MetaTrader commission on that raw USD account is USD 3.50 a side, USD 7.0 round turn. The raw card says $3.5 per lot per side. The standard card says $0. Together with the spread, $0.10 plus $7.00 is $7.10. cTrader and TradingView charge $3 per 100,000 US dollars a side. An AUD account is quoted in AUD. Neither is the bar.
$12.00, $11.00 and $7.10 were built differently. IronFX is an indicative table and a stated zero commission. Pepperstone is a month of averages, rollover included, also zero commission. IC is a raw average plus a stated MetaTrader commission, on a Seychelles firm whose standard cells disagree with each other. The IC raw line is the cheapest on this method, and it is another legal person. IronFX Standard costs a dollar more than Pepperstone Standard and $4.90 more than that IC raw ticket.
Reading which account changes the EUR/USD cost is the same job as the XM review, where a bonus account widened the spread. Here the raw label looks cheaper, and the commission cell will not say by how much.
Client money, leverage, and which court
Clause 5.2 says Notesco I Limited applies negative balance protection, so losses are not supposed to exceed invested capital. That is a term of this contract. It is not the Cyprus Investor Compensation Fund, which sits with the CySEC firm.
Clause 17 is thinner than "segregated" sounds. No interest is paid on client money. Payment services may come from CIFOI Limited, 28 Irish Town, Gibraltar, wholly owned by Notesco Int Limited. The terms name Quandero Pay Ltd as a Canadian money-services business, licence M22168424, for digital-asset work. That number was not checked on the Canadian register. Clause 17.6 allows an omnibus account, says the sum may not be separable, and gives the client no claim on a specific sum in a specific account. The company also disclaims the holder's solvency, acts and omissions.
Disputes under the agreement go to Marshall Islands courts. A Cyprus client would be in another system. The global site tells EU residents it is not for them. The Cyprus site tells new individuals it has stopped taking them. I do not see a retail door into 125/10 between those two lines.
RelatedEquiti Review 2026: Seychelles Holds the Retail Book
Standard leverage is 1:2000, stop-out 20%. Raw is 1:1000 and VIP is 1:200, both with a 50% stop-out. Those are not European retail CFD caps. At 1:2000 a modest move against a full position spends the margin quickly. Negative balance protection, if 5.2 works as written, stops the loss at the cash in the account. It does not slow it.
The group page is a different list
notesco.com, fetched the same day, lists a group, not the ironfxglobal.com contract. Four names: Notesco UK Limited, said to be FCA 585561; Notesco Financial Services Limited, CySEC 125/10; Notesco (SA) Pty Ltd, said to be FSCA 45276; Notesco (BVI) Limited, said to hold BVI licence SIBA/L/24/1175. Vanuatu is absent. It shows up only as a country on a form.
Only 125/10 was read on the regulator's own register this sitting. The FCA page returned a script shell with no firm record in the HTML, so "authorised" is not my finding on 585561. FSCA and BVI were not opened on those registers. They remain the group site's sentences. ironfx.co.uk resolved to the same loopback address, so no UK IronFX site was there to read.
The ATFX review separated an FCA firm from a Mauritius contract, and the Equiti review found the retail book in Seychelles. Here the live contract is Marshall Islands, 125/10 is closed to new individuals, and the UK, South African and BVI names are unverified on those registers.
Verdict
I rate IronFX 2.8 out of 5.
The footer names the counterparty and says the affiliate is not the one providing the service. Licence 125/10 is on the register with domains attached. EUR/USD is published by account, standard commission is stated as zero, the terms state negative balance protection, and the Cyprus firm still prints a Pillar III ratio well above its own minimum.
It stays under 3 because the client on the live site does not get licence 125/10, the raw commission is a blank, and the Cyprus capital is not the Marshall Islands company's.
Pros
- ironfxglobal.com states that Notesco I Limited, not an affiliate, provides the services.
- Licence 125/10 remains on the CySEC register, with a Limassol address and two named domains.
- EUR/USD is published by account, and both standard accounts state no commission.
- The 2026 terms state a negative balance protection policy.
- Pillar III at 31 December 2024 reports a 373% capital ratio against a 100% minimum, for the Cyprus firm only.
Cons
- The live global contract is not the CySEC firm, and ironfx.eu is not taking new individuals.
- ECN Raw shows a zero spread and commission "Yes", with no dollar rate.
- Standard leverage is 1:2000, stop-out 20%, under Marshall Islands law.
- ironfx.com resolves to 127.0.0.1. The contract host and the CySEC domains differ.
- Client money may be omnibus, and the contract disclaims the holder's solvency.
- The April 2024 page records a €100,000 settlement and does not describe the conduct.
- Cyprus equity was positive at end-2024 only after netting $15.551 million of accumulated losses against share premium.
2.8 means the file can be read. It does not mean a new retail client is inside the licence the brand is known for. On 3 October 2026 the entity on the global contract was Notesco I Limited, and the standard EUR/USD indication was $12.00 round turn per standard lot.
FAQ
Is IronFX regulated by CySEC?
Notesco Financial Services Ltd, which uses the name IronFX, holds CySEC licence 125/10, dated 16 November 2010, on the domains ironfx.eu and fxlift.eu. That firm says it no longer accepts individual investors. The contract on ironfxglobal.com is with Notesco I Limited, a different company.
Who faces the client on ironfxglobal.com?
The footer and the 11 August 2026 terms name Notesco I Limited, Marshall Islands number 120910, and say an affiliate does not provide those services. Governing law is Marshall Islands law. The terms quote no regulatory licence number for that company.
What does a standard EUR/USD round turn cost?
On 3 October 2026 the global table showed 1.2 pips for Standard Floating and Standard Fixed, and the account page showed no commission. One standard lot is $12.00 round turn at $10 a pip, before swaps. The table is indicative. Fixed majors widen between 11pm and 2am GMT+2.
Is the raw commission published?
Not in dollars. ECN Raw shows a 0 pip forex spread, commission "Yes", and leverage of 1:1000. The account table and the 2026 terms give no dollars per lot. That account cannot be ranked against the $12.00 standard cost until the rate is printed.
Is the contract a Vanuatu company?
Not in the documents read for this review. The 2026 global terms name a Marshall Islands company. The group licence list covers UK, Cyprus, South Africa and the British Virgin Islands, and it does not name Vanuatu. The CySEC domain list for 125/10 does not either.
Can an EU resident open on the global site?
The global site says it is not aimed at EU residents and sits outside MiFID II, though a click-through is offered. The Cyprus firm, which holds the MiFID licence, says it will no longer accept individual investors. No third door into 125/10 turned up in this reading.
Disclaimer
This is analysis, not a recommendation. Spreads move, terms change, and capital is at risk. Figures are those printed on the named pages on the named dates. Nothing here is an invitation to open or fund an account.