The 0.0-pip line on a VT Markets RAW ECN card is not the price of a EUR/USD lot. On 16 October 2026 the firm's EU account page printed 0.0 pips for that tier and a commission of $6 per round turn. A standard lot on a US-dollar account is 100,000 euros, and one pip of EUR/USD on that lot is $10. That $10 is the contract size times 0.0001. It is not a live quote of the pair. A spread that traded at the printed floor would add nothing. The commission would still remove $6 on the round trip. Standard STP, on the same card, prints 1.2 pips and a $0 commission. That 1.2 is a card figure, not a measured EUR/USD average, so it should not be multiplied out and labelled typical. The myth is specific. A zero in the spread column does not make the lot free.
Two documents, set beside that card, decide who receives the $6 and what a deficit becomes. The footer of the same EU page names VT Markets Limited as the product supplier and says VT Markets (Pty) Ltd, FSP 50865, "is not the market maker or product issuer and acts solely as an intermediary." The Key Facts Summary of that Mauritius company, number 201902 GB, at The Catalyst in Ébène, says the agreement is with VT Markets Limited under FSC licence GB23202269. A separate agreement for VT Markets LLC in Kingstown says the St Vincent authority does not license margin FX. The $6 sits on the Mauritius product card. It is not a Kingstown licence, and it is not a fee of the Sandton firm.
Key facts
- RAW ECN on the EU account card prints spreads of 0.0 pips and a commission of $6 per round turn, with a $100 minimum deposit and a 0.01 lot minimum — VT Markets trading-accounts page, 16 October 2026.
- Standard STP on the same card prints 1.2 pips and a $0 commission, again with a $100 minimum and a 0.01 lot minimum — VT Markets trading-accounts page, 16 October 2026.
- The Key Facts Summary says the agreement is with VT Markets Limited under FSC Investment Dealer (Full Service Dealer, excluding Underwriting) licence GB23202269, company 201902 GB, The Catalyst, Ébène — Key Facts Summary read 16 October 2026. The FSC online public register did not return a matching row in this session.
- If the account has a negative balance, the client is required to fund it back to a zero or positive balance — Key Facts Summary, section 6, read 16 October 2026.
- VT Markets (Pty) Ltd, FSP 50865, is described on the EU footer as an intermediary, not the product issuer, with a Sandton address at Norwich Place West — VT Markets EU trading-accounts page, 16 October 2026. An FSCA search on 16 October 2026 returned no FSP 50865 record.
- Pepperstone's en-gb Razor table shows a EURUSD average spread of 0.1 pip from data for 1 to 31 August 2026, and an MT4/MT5 commission of $3.50 per standard FX lot per side, which is $7.00 round turn — Pepperstone pairs-and-spreads page, retrieved 16 October 2026.
- Tickmill's Europe raw-account page gives an explicit example: 1 lot of EURUSD costs $3 per side and $6 round turn, with spreads starting from 0.0, and states that 74% of retail CFD accounts lose money with Tickmill Europe Ltd — Tickmill raw-account page, 16 October 2026.
The name on the contract is not the brand
VT Markets is a label stretched across several companies. The EU trading-accounts footer, read on 16 October 2026, splits them in one block of regulatory text.
VT Markets Limited is the company that footer calls the product supplier: 40 Silicon Avenue, The Catalyst, Level 2, Suite 201, Ebene, licence GB23202269, Full-Service Investment Dealer, excluding underwriting. The Key Facts Summary, eight pages opened the same day, repeats company number 201902 GB, the Ébène suite, and the licence. Section 1 says the client is entering an agreement with VT Markets Limited and that the FSC governs dealings in the products. Section 2 says the summary is important and binding, with further terms in the Client Agreement.
The Mauritius client-agreement PDF did not open. A request on 16 October 2026 returned a Cloudflare interstitial and no clause text. This review does not quote that file. It uses the Key Facts Summary and the live footer.
VT Markets (Pty) Ltd is a different company: FSP 50865, South African registration 2015/072049/07, Norwich Place West, 2nd Floor, Sandown, Sandton. The footer says it is not the market maker or product issuer, acts only as an intermediary under the FAIS Act, and is not principal or counterparty. Stopping at "FSCA regulated" stops at the introducer. Its Dubai branch, CMA licence 20200000299, is Category 5 for introduction and promotion. The footer says that branch may not provide brokerage or execute trades.
VTMarkets Ltd in Cyprus, registration HE436466, 160 Archbishop Makarios III Avenue, Floor 1, 3026 Limassol, is on the same footer with a blunt line: it does not offer regulated financial products or trading services.
Kingstown is a separate contract. The VT Markets LLC agreement, read on 16 October 2026, is with company 673 LLC 2020 at the First St Vincent Bank Ltd Building, James Street. Clause 1.1(a) says the firm is registered with the Services Authority, then states: "The FSA does not regulate, monitor, supervise or license margin FX and contract for different issuers." The SVG FSA register was not opened.
The FSC Mauritius online public register was opened and returned no row for VT Markets Limited or GB23202269. The licence number is what the Key Facts Summary and the EU footer print. It is not a register confirmation from 16 October 2026. An FSCA search in this session also returned no FSP 50865 record. Both gaps stay open.
$6 is what the card actually charges
The comparison on vtmarkets.com/en-eu/tradingaccounts, retrieved 16 October 2026, is a set of cards, not a measured EUR/USD average. RAW ECN prints 0.0 pips, a $100 minimum, $6 per round turn, and a 0.01 lot minimum. Standard STP prints 1.2 pips, $100, and $0. Base currencies on both cards are AUD, USD, HKD, GBP, EUR and CAD. The page names MT4, MT5, the VT Markets app and WebTrader. It does not give each platform its own commission.
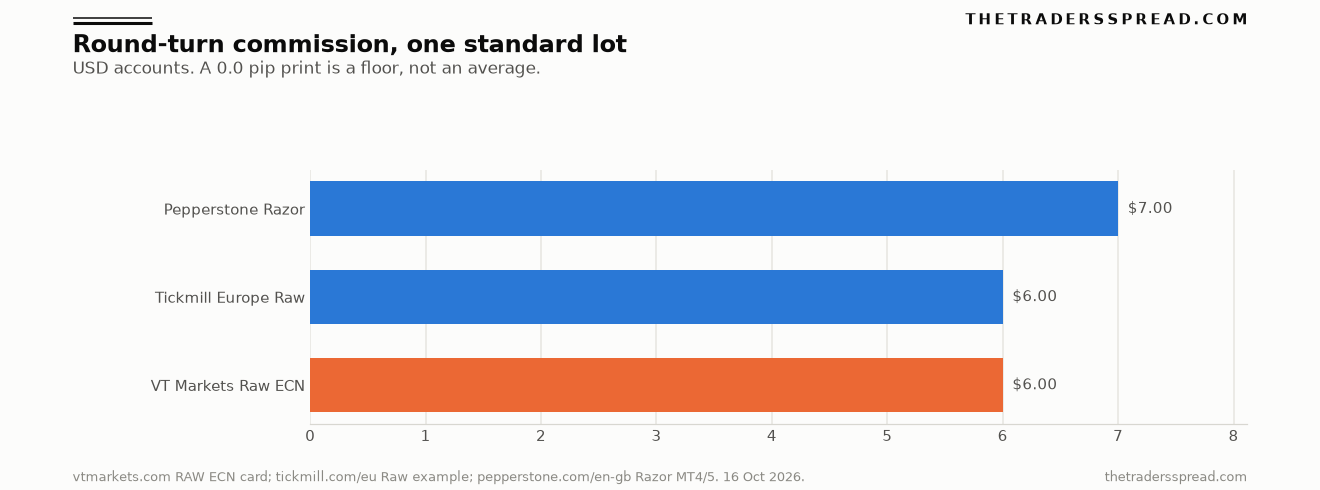
On a USD account the conversion is short. Zero pips times $10 is $0, and the round-turn commission is $6, so the published floor is $6 a standard lot. A wider spread than 0.0 costs more, at $10 a pip. The page prints no average EUR/USD spread for RAW ECN. Treating 0.0 as typical uses a floor as a mean.
Standard STP is the same trap in reverse. A $0 commission beside 1.2 pips is $12 a standard lot only if the ticket spread equals 1.2. The card does not say 1.2 is the EUR/USD average.
Swap-free rows repeat the prices and add a line the plain RAW ECN card lacks: leverage up to 1000:1, with swap set to none. That 1000:1 belongs on the swap-free rows only. Cent RAW ECN, limited to forex, gold, silver and oil, prints 0.0 pips and $6 per round turn, with a $50 minimum and a USC balance.
| Card on the EU page | Spread print | Commission | What the print is not |
|---|---|---|---|
| RAW ECN | 0.0 pips | $6 per round turn | Not a measured EUR/USD average |
| Standard STP | 1.2 pips | $0 | Not a named EUR/USD average either |
| Swap-free RAW ECN | 0.0 pips | $6 | Leverage up to 1000:1 is on this row |
| Cent RAW ECN | 0.0 pips | $6 per round turn | Minimum deposit $50, currency USC |
Peers, priced from their own pages the same day, put the $6 in a range. Pepperstone's en-gb table, data from 1 to 31 August 2026 including rollover, shows EURUSD on Razor at a minimum of 0 and an average of 0.1 pip. MT4/MT5 commission is $3.50 per standard FX lot per side in USD, or $7.00 round turn. At that average the spread is about $1, so all-in is about $8. The page says 73.6% of retail accounts lose money with this provider. An earlier Pepperstone note used an AUD schedule. These dollars are the en-gb USD card.
Tickmill's raw-account page, the Tickmill Europe Ltd schedule, says spreads start from 0.0 and commission is $3 per side per lot. The example: 1 lot of EURUSD is $3 a side and $6 round turn, on FX and precious-metals CFDs. The specification table rendered without an average, so none is invented. The page says 74% of retail CFD accounts lose money with Tickmill Europe Ltd. An earlier Tickmill note is a different page. This $6 is not a TradingView Raw tier.
IC Markets stays off the chart. The global raw-spread URL showed a visitor notice for Raw Trading Ltd and no commission table. The EU accounts URL returned a 404. An earlier IC Markets note discusses a platform split this session could not re-read.
A negative balance is an amount the client must fund
Section 6 of the Key Facts Summary is one sentence, and it is not a slogan. "If your account has a negative balance, you are required to fund it to return it to a zero or positive balance." The client must also keep enough for margin calls and watch the account.
Sections 4 and 5.3 sit beside that line. Clients top up or close out when margin is no longer met. Margin is usually the contract margin, plus cover for realised or unrealised loss on other positions, plus foreign-exchange adjustments. A miss, including at little or no notice, may close some or all contracts without notice. An imperfect hedge may not trigger a margin call, and it still gives the firm the right to close open positions.
Section 5.11 limits how far anyone can lean on the firm's close-out. VT Markets may liquidate positions without prior notice if account value hits the liquidation level. It does not assure the client that it will do so. The summary says that right is not a risk tool to rely on. Read with section 6, a deficit is the client's to fund. Automatic erasure is not what this document says.
Section 3 keeps the service execution-only. The summary is not a recommendation, and the client selects the product.
Section 8 lists charges the 0.0 card omits: a spread mark-up, overnight financing, and an introducer the firm may pay. Banks may charge for deposits and withdrawals. The firm says it does not. Swap-free accounts pay an administration fee of liquidity-provider costs plus about 10%. US share CFDs, in section 8.2, typically cost $6 per transaction. That is not the RAW ECN round turn.
The other side of the ticket can reprice it
Section 5.7 lists discretions in the Client Agreement. The price used to open and close is set with reference to hedging partners, and in stated cases it may differ from the market. The summary says the firm acts as a market maker, "mainly due to system failure," and sets the prices at which it will deal. If trading is limited, the price is the last one before the limit, or a price set in the firm's discretion, acting reasonably.
The same section lets the firm close part or all of a position, cap the value that can be opened, refuse an order, or end the agreement. One trigger is its own decision, with prior written notice. Another is a step it considers necessary to protect its rights. The client cannot direct those choices.
Stops do not close the gap. Section 5.4 says a stop-loss or take-profit is not guaranteed: it may be rejected, or fill at the next price. Section 5.8 says quotes are indicative. There is no assurance of a fill at the ordered price. The summary calls the difference slippage, most often around news or gaps, and ties it to the liquidity at each price.
Sections 5.5 and 5.9 put platform failure on the client. The firm disclaims losses from faults outside its control. In extreme conditions it may suspend the system, close contracts at prices it considers fair, and set volume limits. Section 7.1 lists margin FX plus index, energy, share, commodity, metal and cryptocurrency CFDs. The $6 card does not cap financing or a later wider spread.
RelatedMultiBank Review 2026: MEX Atlantic, Not a 0.0 Ticket
Section 9 states best execution for retail and professional clients. It does not make quotes guaranteed. Either party may end the agreement in writing. The EU footer withholds the service from residents of the United States, Singapore, India, Hong Kong, Russia, and FATF-listed jurisdictions. A separate notice refuses Singapore account requests.
What would change this reading
A 0.0 can appear on a EUR/USD ticket. The question that matters is what the client has agreed to pay, and to whom, when the ticket is round-turned and when the balance goes negative.
On the documents opened on 16 October 2026, the contracting company is VT Markets Limited in Ébène. The South African FSP is an intermediary. Dubai introduces. Cyprus does not offer the trading service. Kingstown's agreement says the FSA does not license margin FX. RAW ECN commission is $6 per round turn, and 0.0 is a spread floor. Section 6 requires a negative balance to be funded back. Stops are not guaranteed.
Three checks would move that reading. A live FSC Mauritius row for VT Markets Limited and licence GB23202269 would confirm what the Key Facts Summary only asserts. This session did not find it. An FSCA extract for FSP 50865 would do the same for the intermediary, and the search used here returned none. A RAW ECN page with a measured EUR/USD average, dated and named by platform, would turn the $6 floor into an all-in figure. That average is not on the card.
The peer commissions are the comparison that survives. Tickmill Europe's EURUSD example is also $6 round turn, with spreads from 0.0 and no average in the table that rendered. Pepperstone's Razor commission on MT4/MT5 in USD is $7 round turn, and the August 2026 average of 0.1 pip adds about $1. VT Markets is not an outlier on the commission. It looks cheaper only if the pip column is treated as the whole invoice.
The rating on this page is this desk's reading of those documents, on a scale of 0 to 5. It is a 3. The commission is printed in dollars, the issuer is named, and the intermediary is labelled as an intermediary. The register gaps, the deficit-funding clause, the unguaranteed stops, and the missing EUR/USD average hold it there. It is not a survey score. Nothing above is an instruction to open an account, to fund one, or to close one.
FAQ
Is a VT Markets EUR/USD lot free when the spread says 0.0?
No. On the RAW ECN card retrieved on 16 October 2026, 0.0 pips is the spread print and $6 per round turn is the commission. On a USD standard lot, one pip is $10, so a spread at that floor adds $0 and the commission still costs $6. If the spread received is wider than 0.0, the lot costs more. The page does not publish an average EUR/USD spread for this tier.
Which VT Markets company holds the client contract?
The Key Facts Summary says the agreement is with VT Markets Limited, company 201902 GB, at The Catalyst in Ébène, under FSC licence GB23202269 as the firm states it. The EU footer calls that company the product supplier. VT Markets (Pty) Ltd in Sandton is described there as an intermediary, not the issuer. The Kingstown LLC is a different company, and its agreement says the FSA does not license margin FX.
Was licence GB23202269 confirmed on the FSC register?
Not in this session. The FSC Mauritius online public register was opened and did not return a row for VT Markets Limited or for GB23202269. The number is taken from the Key Facts Summary and from the EU footer, both read on 16 October 2026. An FSCA search on 16 October 2026 returned no FSP 50865 record. The SVG FSA register was not opened.
Does a negative balance disappear on its own?
Not on the document that opened. Section 6 of the Key Facts Summary says a negative balance must be funded back to zero or to a positive balance. Section 5.11 allows the firm to liquidate at a set level and says the client should not rely on that right. The full Mauritius client agreement did not open past a Cloudflare check, so this review does not describe a protection clause it could not read.
How does the $6 sit next to Pepperstone and Tickmill?
Tickmill Europe's raw page, retrieved the same day, prices 1 lot of EURUSD at $6 round turn, with spreads from 0.0 and no average in the table that rendered. Pepperstone's en-gb Razor commission on MT4/MT5 is $3.50 a side in USD, or $7 round turn, and its EURUSD average for August 2026 was 0.1 pip, about $1 more. IC Markets is not in the comparison: its pricing page did not open past a visitor notice.
This is analysis of published schedules and legal summaries, not a recommendation to open, fund, or close an account. Margin foreign exchange and CFDs are leveraged products, and losses can exceed the sum deposited. Figures were taken from the brokers' own pages and from VT Markets' Key Facts Summary on 16 October 2026. Those pages can change without this article changing with them. A licence number printed by a firm is not a substitute for a row on the regulator's register.